Market Intelligence

Energy News

Weekly analysis of Texas energy markets, data center developments, and power infrastructure trends from the Barrio Energy team.

Get The Grid Report every week

ERCOT analysis, data center developments, and power infrastructure trends — delivered to your inbox.

Texas Said Pause. The Pipes and the Permits Kept Moving.

Kinder Morgan commits $4.2 billion to a 2.8 Bcf/d pipe for an unnamed hyperscaler, TCEQ shuts its e-filing system while the permit count is disputed, and ERCOT batteries post a record quarter.

Read full article →

Previous Articles

1.5 GW Gets a Split Vote, 4 MW Gets a Tenant

Alabama approves a 1.5 GW campus on a 3 to 2 vote, Michigan writes an 80 percent power floor, and the only priced lease is a 4 MW building from 1989.

Read more →

"Local Government Should Be Included in That Conversation": The Pause Is On, the Dirt Keeps Moving

Texas froze new data center energization until December 10. Meanwhile a $15 billion off-grid campus broke ground without telling its county, a 606 MW Houston gas plant changed hands, and 150 more MW of batteries went live.

Read more →

Entitled, Not Energized: 55 MW in Salisbury, 73 MW Out of Bankruptcy in Bryan, and TVA's $1.5 Million-a-Megawatt Toll

No marquee tenant signed under 75 MW this week. Instead: a 55 MW Flexential entitlement at 186 W/sf after a twelve-month fight, a 73 MW RELLIS campus bought out of Chapter 11, a 20 MW Michigan retrofit sized for $5–7.5M/MW of project debt, and the new $1.5M/MW TVA capacity toll that one sponsor contracted around with a day to spare.

Read more →

"We Can't Drink Data": Taylor Annexes a Gas-Fired Campus, and the PUC Sues to Keep the Counties Secret

The PUC sued the Attorney General to withhold which counties Texas data centers are in, the same week ERCOT demands every large load disclose its water, owners and on-site generation. Taylor annexed 664 acres and a half-gigawatt gas plant to write its own rules. The NRC put four AP1000s on the record, the industry hired a storyteller, and Crusoe filed two more $2.4 billion buildings.

Read more →

"Pay Their Own Way": Korea Funds 6.5 GW of Gas, Texas Lends for 452 MW, and the Audit Hits Monday

Project Star puts $22.3 billion and 6,472 MW of gas behind a 5 GW data center, with $2.4 billion already sent from Seoul. Texas Energy Fund loan No. 9 adds 452 MW. ERCOT's data center questionnaire is due Monday.

Read more →

The Tenant Is the Equity Now: $2.2M a Megawatt-Year in Spartanburg County, a $42.9M GPU Divorce in Columbus, $112 a Foot in Eagan

Four deals between 5 and 50 MW, four states, and in every one the owner of the building no longer owns the chips. Nebius prepays AIB's build at $2.2M per MW-year; Duos sells its GPUs to Axe for $42.9M and keeps the shell; DataBank buys MSP2 back at $112 a foot; a tower-site inference JV in High Point; and the $780K/MW-yr powered-shell benchmark from Ward County.

Read more →

Who Pays for Meta's 366 MW of Gas? Judges Say Not El Paso Ratepayers

Judges told El Paso Electric that Meta's 366 MW gas plant gets approved only if ratepayers stay off the bill. Crusoe plugs Google into 531 MW of wind, Cipher doubles Barber Lake to 20 years, and Enerflex sells 450 MW that never meets the grid.

Read more →

Permits Are the New Power: $2.7M an Acre in Phoenix, $1.75M a Megawatt in Georgia, and 7.875% on a Meta Guarantee

Texas froze permits and Loudoun paused applications. The deals that still printed had already won the zoning fight, and this week we got to read the price: $2.71M an acre and $201 a foot for waivered Phoenix infill, $1.75M/MW for a 48 MW turnkey build at 196 W/sf, a GPU-designer-guaranteed 76 MW gas deal in West Texas, and $157/kW-month on the Meta lease behind CleanSpark 7.875% notes.

Read more →

"No Other State Agency Shall Move Forward": TCEQ Halts Data Center Permits, Paxton Names 18 Counties, and the PUCT Sets $50,000 a Megawatt

Abbott halts every TCEQ data center permit, Paxton opens a water-survey investigation in 18 counties, and the PUCT adopts the SB 6 interconnection rule at $50,000 per MW. Meanwhile Vistra, Kodiak and Meta signed 427 MW of deals in a week.

Read more →

Seventy-Five Megawatts Is Now a Design Parameter

Two frontier labs went shopping at 20 to 30 MW, Host Digital disclosed that its electric service agreement cost 21 percent more than the building it feeds, and Nscale put the first public price on an NVIDIA guaranty: 6.97 percent of principal.

Read more →

"Very, Very Intrusive": 461 Surveys, 231 Notaries, and a Board That Voted Itself a 30% Raise

ERCOT published the Batch Zero aggregate: 191.8 GW in, 302.2 GW out, and 0 of 231 verification questionnaires submitted. The state sent 461 community impact surveys, the Governor put the water survey under criminal referral, and the ERCOT board chose the same week to raise its own pay 30 percent. Plus Oracle buys 1.7 GW of existing wind and Blue Energy files for a gas-to-nuclear plant at the Port of Victoria.

Read more →

Nobody Disclosed a Square Foot

Four sub-75 MW deals closed or cleared this week and not one disclosed a building footprint. AIB priced an energized megawatt at $550,000 and a dark one at $224,385 on the same campus, the same day.

Read more →

ERCOT Sorted the Queue and Published Nothing, So the Market Built Its Own Scoreboard

ERCOT issued conditional Batch Zero classifications on September 3 and published no list. Eight sponsors self-reported, all of them favorably, and the only aggregate scoreboard in Texas was assembled from press releases. Plus: notarized attestations on a ten-day clock, two PUCT orders that never issued, and $196.7 million of engines bought in eighteen days.

Read more →

$161 a Kilowatt-Month in Tulsa, 333 Watts a Foot in Dowagiac: The Middle Market Prices Live Power

Five deals under 55 MW and one land comp above it: a $1.25B take-or-pay in a Tulsa business park, a Michigan bitcoin barn turned neocloud hall at 333 W/sf, Corvex raising $33M to rent 6.5 MW, a 54 MW JV into 2.8% DFW vacancy, and Colovore filing $1,453/sf in Hutto. Nobody bought dirt this week. They bought meters.

Read more →

Around the Queue, Not Through It: $35 Billion in Nueces County, 400 Miles of 765 kV, and a Batch Zero List Three Days Late

ERCOT delivered the conditional Batch Zero classifications on Thursday, three days past the extension it asked for. Meanwhile the capital went around the queue: Anthropic, Lambda and Nvidia stacked $35 billion on a Hut 8 interconnection, Bitdeer paid $100 million for 200 acres next to a substation, SB Energy filed to go public with zero operating data centers, Cipher ordered gas pipe for 2.5 GW, and the PUCT approved 400 miles of 765 kV over the Attorney General’s objection.

Read more →

The 40 MW Gets a Credit Rating

J.P. Morgan and Goldman close $1.2B of investment-grade debt on a 40 MW retrofit in a North Carolina town of 2,200, I Squared launches a $1B platform on 53 MW of ex-Sprint switch rooms, and a Kentucky city draws the hyperscale line at 75 MW and 1,500 W/sf.

Read more →

"The Only Meaningful Remedy Remaining": Three Judges Recommend Killing the Line, and ERCOT Concedes April Is Gone

Administrative law judges told the PUCT the need case for the center 765-kV import path was never proven. Hours earlier, ERCOT conceded the Batch Zero study will miss its April 9, 2027 deadline. Meanwhile the grid took six straight August records without raising its voice, and IREN priced an energized Texas megawatt at $25 million.

Read more →

Buy at $4.2M a Megawatt, Build at $5.9M, Rent at $1.5M a Year

Five sub-75 MW transactions printed this week and, put side by side, they give the small-site market a legible price: used capacity around $4.2M a megawatt, new build near $6M, rent about $1.5M per megawatt-year. Saragon, Flexential, Duos, Host Digital and Keel — plus a seller note that does not amortize until the utility shows up.

Read more →

"A Slap in the Face to the Legislative Branch": PUCT Votes on 765kV Lines Nobody in Austin Says They Approved

PUCT votes today on two contested 765kV transmission segments as lawmakers say they never authorized the buildout. Meanwhile LS Power pays $860 million for Texas gas capacity, a nuclear-gas hybrid near Victoria clears its next gate, and Cipher Digital's Cotulla bet gets caught in the state's new interconnection audit.

Read more →

Wires or Pipes: Moving 7.6 Gigawatts 100 Miles, Two Ways

One 765 kV circuit and one 30-inch pipeline move the same gigawatts. Marco runs the unit economics on both: capex, opex, losses, and every acre encumbered along the route.

Read more →

Eighty-Two Dollars a Foot in Oakland, Thirteen Sixty-Seven in Bristow

Six small data center buildings traded or got entitled in the lower 48 this week, from 3 MW to 55 MW. Price them per square foot and the spread is 16.7x. The variable is not power or geography. It is whether a lease is signed.

Read more →

"Already Fully Approved and Energized" — $9.1 Billion for 191 MW, and 8,766 MW Nobody Counted

Abbott's audit did not stop Texas data centers — it repriced them. Riot leased 191 already-approved megawatts at Rockdale for .1 billion, ERCOT asked the Commission for more time on three deadlines at once, and buried in the filing was 8,766 MW of sub-threshold load nobody was tracking.

Read more →

Twenty Megawatts: Now a Zoning Trigger, Still a Financing Orphan

Tucson and Tonawanda both set their data center permitting tripwire at 20 MW in the same week Hut 8 priced an investment-grade project bond 20 basis points inside its last one. The middle of the market is now regulated like a hyperscaler and financed like a startup — one 20 MW campus in Michigan is on the block, and a 1 MW box in Pittsford traded for about $1.1 million.

Read more →

"ERCOT Will Not Notify": 205 Gigawatts Miss Their Own Deadline

ERCOT was supposed to classify roughly 205 GW of Batch Zero load by August 7. Four days early, it said it would not. BNEF prices the pause at 49.8 GW and up to $15 billion, Oncor counts 44 GW it expects to keep, and the 765-kV Permian plan takes fire from the Lieutenant Governor.

Read more →

"Must Be Denied": Abbott Freezes the 474-GW Queue — and NRG Signs $3.2 Billion Anyway

Texas ordered an audit of all 474 GW in the ERCOT queue and shelved Batch Zero. One day later, NRG signed the biggest contracted gas newbuild of the cycle. The projects with power already in hand just became the moat.

Read more →

Demand First, Dirt Second: A 40 MW Pre-Lease, $50M/GW Deposit Math, and the ABS Window Reopens

The week the sub-75 MW market moved on paper instead of dirt: Cerebras pre-leases 100% of a 40 MW Minnesota campus, a 1.125 MW Dallas colo signs after the offtake, a $95M fund fronts ERCOT Batch Zero deposits at $50M/GW, Aligned reopens the ABS window at $1.18B, and Loudoun County studies a moratorium.

Read more →

The Comp Is $1.76M per MW-Year. The Constraint Is Permission.

AMD puts 15-year chipmaker credit behind 529 MW of converted miner campuses while Forney drafts a ban, Tulare tables the fairgrounds lease, and a dead Eugene fab goes for $17 a foot. The market repriced at both ends this week.

Read more →

"Last Night It Was Nearly 12,000" — The Record Week, and 438 GW at the Door

ERCOT's all-time demand record fell twice in 24 hours and nobody blinked. Plus: Hut 8 fills a 1 GW Gulf Coast AI campus for $19.6 billion, and the Batch Zero window closes on the 438 GW queue.

Read more →

The Edge Premium Prints at 20%: A 10 MW Deal in Columbus Just Priced the Curve

A 10 MW, $111M colocation deal in Columbus, Georgia prints about $2.22M per MW-year — roughly 20% over the wholesale floor. Plus: a council override revives a 400 ksf Kansas conversion, 17 live megawatts change hands in Hood County, and coal country files its off-grid paperwork.

Read more →

727 to 1: Abbott's Deadline Arrives and Nobody Has Decided Who Pays

Shaving one megawatt of peak demand saves a commercial customer about $68,550 a year and a residential customer about $94. Abbott's July 17 deadline arrived without a public memo, five PUCT dockets remain open, and the ERCOT peak record everyone predicted for July never happened.

Read more →

41 Gigawatts in Letters of Agreement: Washington Wires $3.26 Billion Into Texas

DOE closed a $3.26 billion loan to AEP Texas, which has signed letters of agreement for up to 41 GW of new load. Meanwhile 38 Texas data centers quietly permitted more than 2,100 diesel generators with no public review, Batch Zero's first deadline passed, and batteries set a new dispatch record.

Read more →

32 Plants, 287 Million Tons: Somebody Finally Added Up the Texas Gas Buildout

The Environmental Integrity Project counted the gas plants being built to power data centers, and 32 of the 74 nationwide are in Texas. Plus San Marcos zones data centers out of existence, Fermi misses its own tenant deadline, KKR pays $4.2 billion, and wind and solar both set ERCOT records.

Read more →

Build Your Own Grid: Microsoft and Chevron Skip the Wires

Texas approved the first real rulebook for connecting AI load the same week Microsoft and Chevron announced a 2.67 GW gas plant that skips ERCOT entirely. Plus FERC orders six RTOs to catch up, DOE bets $17.5B on nuclear, and xAI shows the bill for going off-grid.

Read more →

Credit Is the New Gatekeeper: A 50 MW Reuse in Colorado Springs, and Three Ways to Pay for the Box

Price stopped deciding inference deals; credit and capital took over. This week: Raeden reuses a 451 ksf shell for 50 MW in Colorado Springs, a Michigan miner chases a 20 MW pivot, Rumble buys 22,000 GPUs, and TensorWave raises $350M.

Read more →

The Sorting Begins: Texas Builds the Machinery to Tell Real Data Centers From Paper Ones

The PUCT approved Batch Zero, the first batch-study process for large loads in the country. Congress moved to decide who pays. Circe ordered 2 GW of gas to skip the queue. And solar is about to pass coal on the ERCOT grid.

Read more →

Power First, Tenant Later

Three deals this week, one pattern: the megawatts and the money showed up before the tenant did. A 20 MW miner-to-AI pivot in Michigan, a $650M Red Oak financing for a 60 MW building with no name on it, and a 210 MW take-or-pay that resets the template.

Read more →

"Add to Capacity, Not Just Demand": Texas Starts Billing the Data Centers

Abbott orders the PUC and ERCOT to make data centers fund their own grid, Google brings its own gigawatt to Gray County, and the state quietly underwrites 456 MW of new gas. Who pays for the power is suddenly the only question in Texas energy.

Read more →

Buying Around the Queue: A Lexington Brownfield, a Cedar City Gas Plant, and Amazon Sets the 6% Comp

Five deals in five states, and not one was really about money. Capital is everywhere; what these sponsors bought was a way around the grid queue and the zoning counter. A brownfield in Lexington, 1.5 GW of behind-the-meter gas in Utah, a settled land fight in Niagara Falls, and Amazon backstopping 70 MW of West Texas debt at six percent flat.

Read more →

438 Gigawatts, and Who Gets to Say No

ERCOT forecast a record 92,211 MW summer peak and said the grid will hold — then voted to triage a 438 GW data center queue that is five times the size of the state. Meanwhile Google brings its own power to the Panhandle, El Paso tries to claw back Meta and Hood County learns it has no off-switch.

Read more →

The Week the Grid Said No: 900 MW Dead, a Year-Long Freeze, and a $14.5M Exit

Some weeks the news is what got built. This week it is what got killed: 900 MW voted down in Hanover, a one-year freeze in Little Rock, and a Singapore REIT walking away from a stranded Philadelphia box. Capital refinanced and exited rather than chase new megawatts.

Read more →

238 Gigawatts on Paper, $100 Million in Federal Court

ERCOT closed May with a 238 GW large-load queue, Hill County got sued in federal court for $100 million over its data-center moratorium, Spearmint closed $450M on a 600 MWh battery in Texas City, gas crossed wind in the queue, and Fermi bought 600 MW of Siemens turbines off the shelf to skip the OEM line.

Read more →

The Anchor Tenant Is the Underwrite: Four Deals, One Pattern

Four deals closed or got entitled this week — Applied Digitals $7.5B Polaris Forge 3 lease, I Squareds $225M Cogent portfolio buy, Nscales $865M Madison NC ramp, and the Pulaski County moratorium that carved out AVAIOs $6B Leo campus. Spec development is dead. Capital prices off the name on the lease.

Read more →

$67 Billion and the Biggest Utility Ever

NextEra buys Dominion for $67 billion to build the world largest utility, the EIA says solar will outproduce coal in ERCOT for the first full year ever, and El Paso moves to deny data centers any tax breaks. Consolidation at the top, contention at the bottom.

Read more →

Three Charts for the Data-Center Conversation You're About to Have

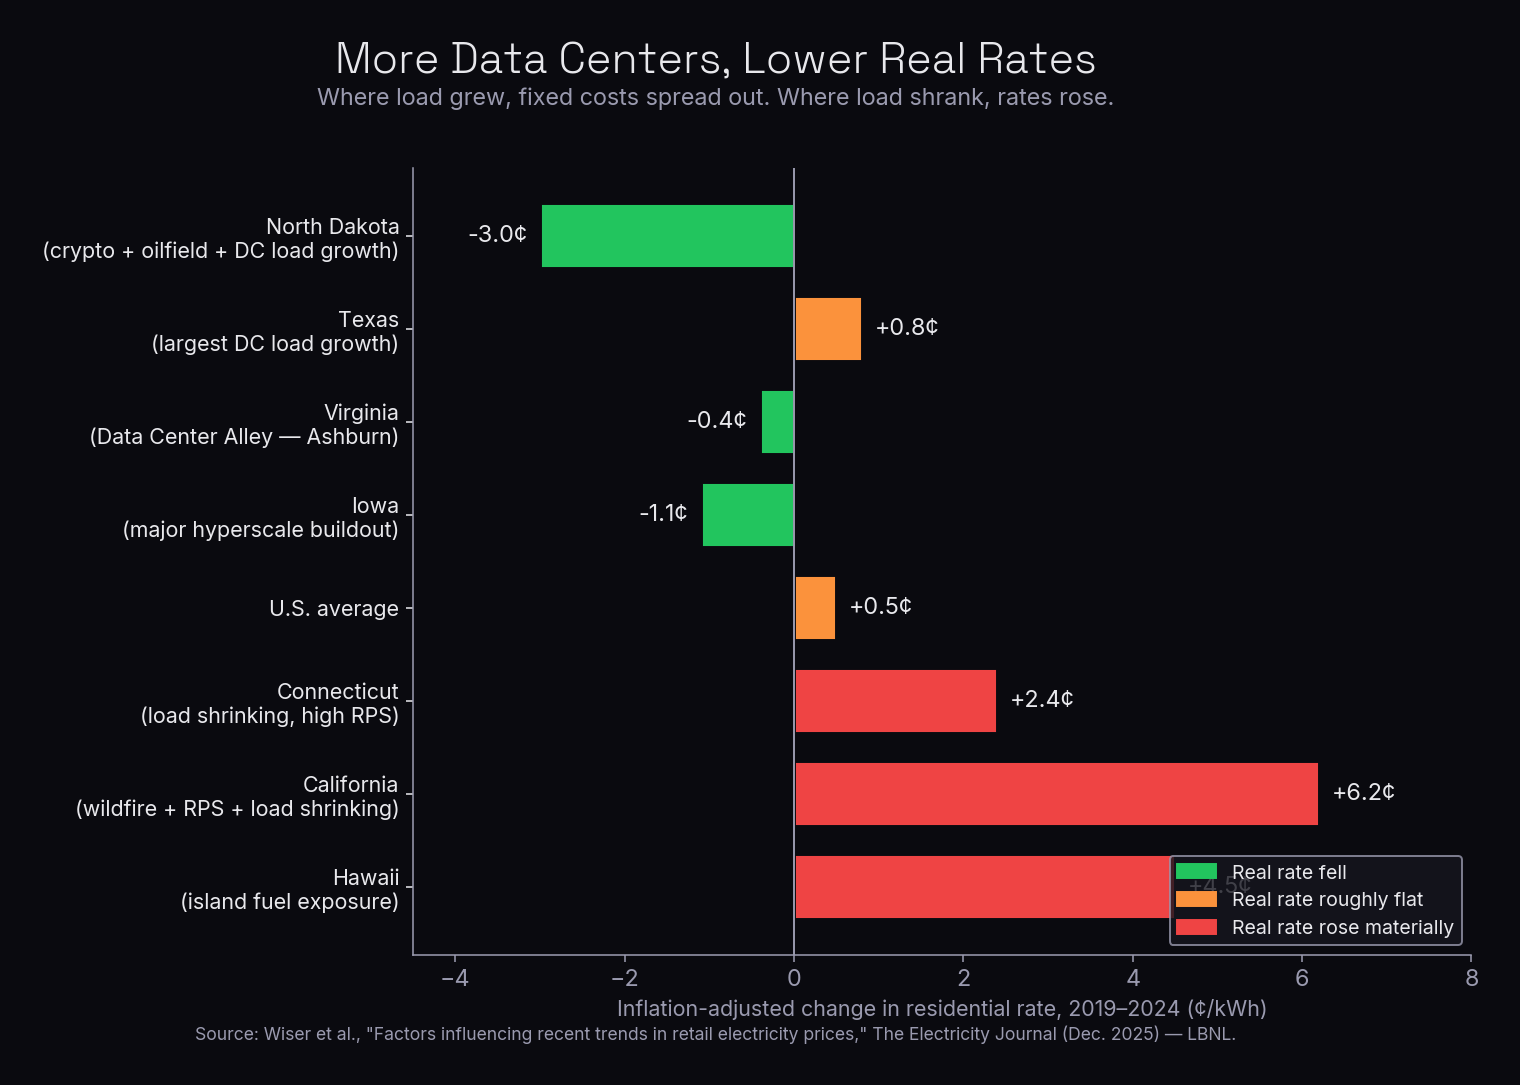
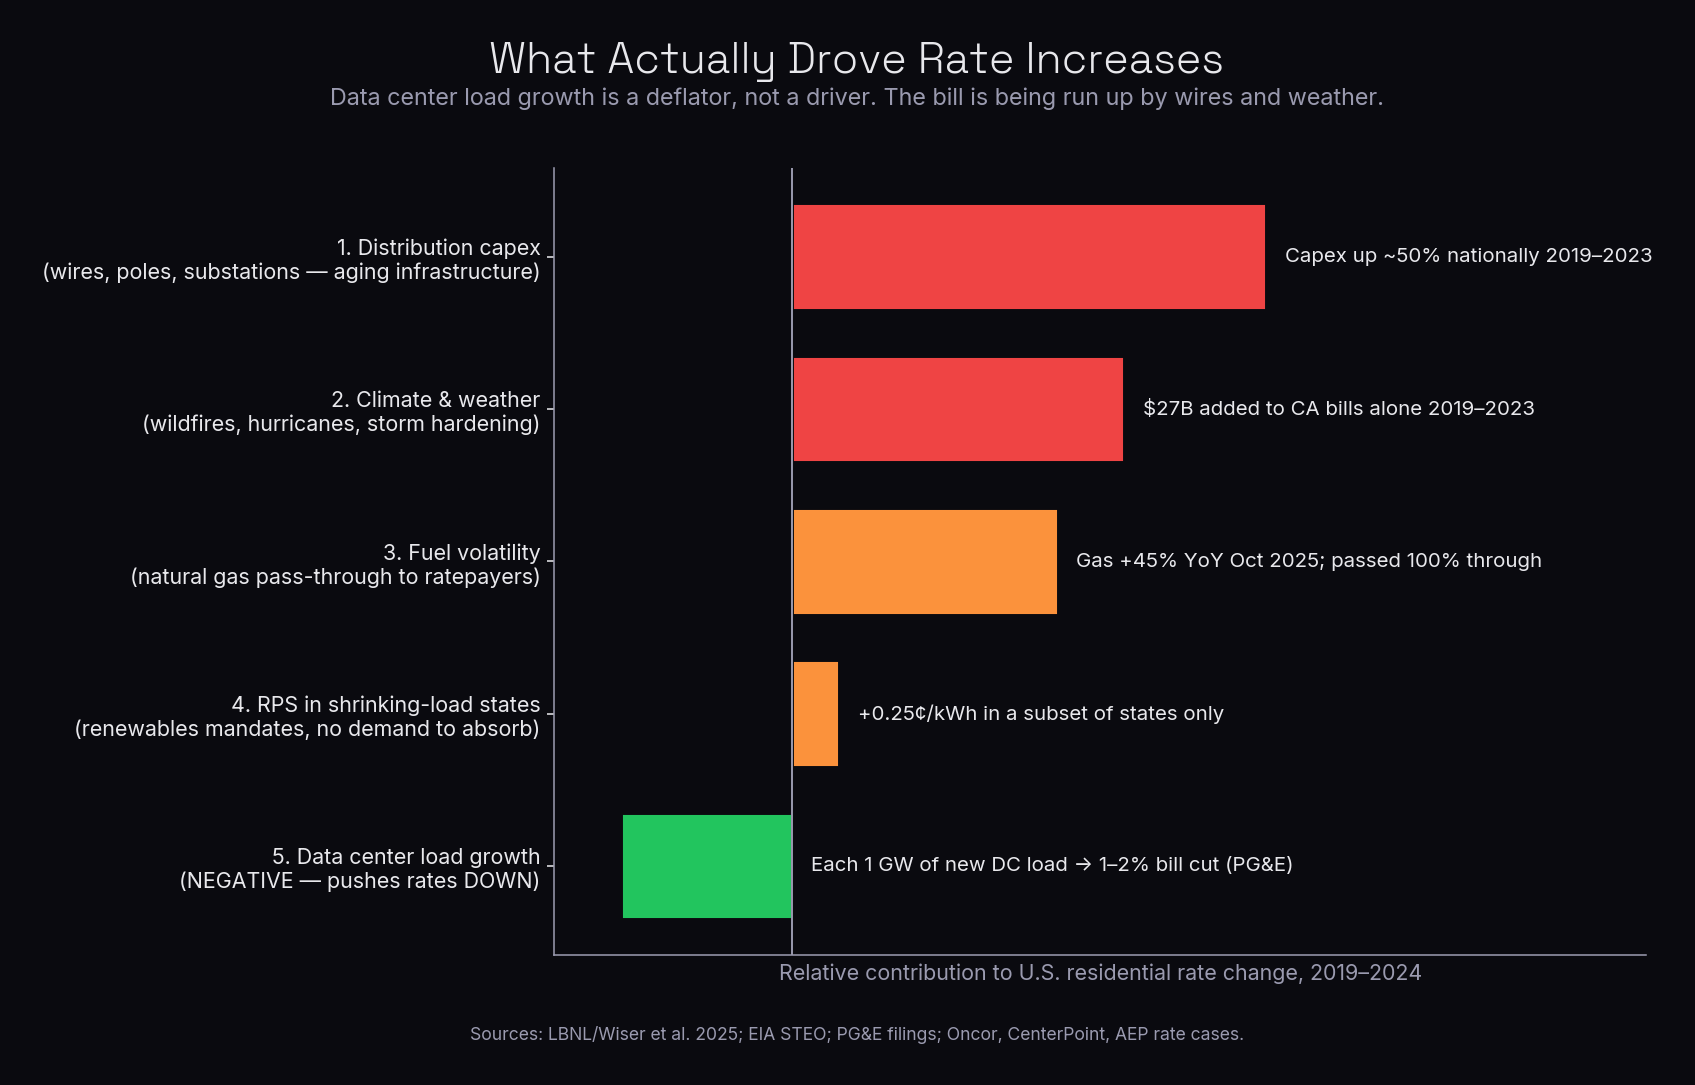
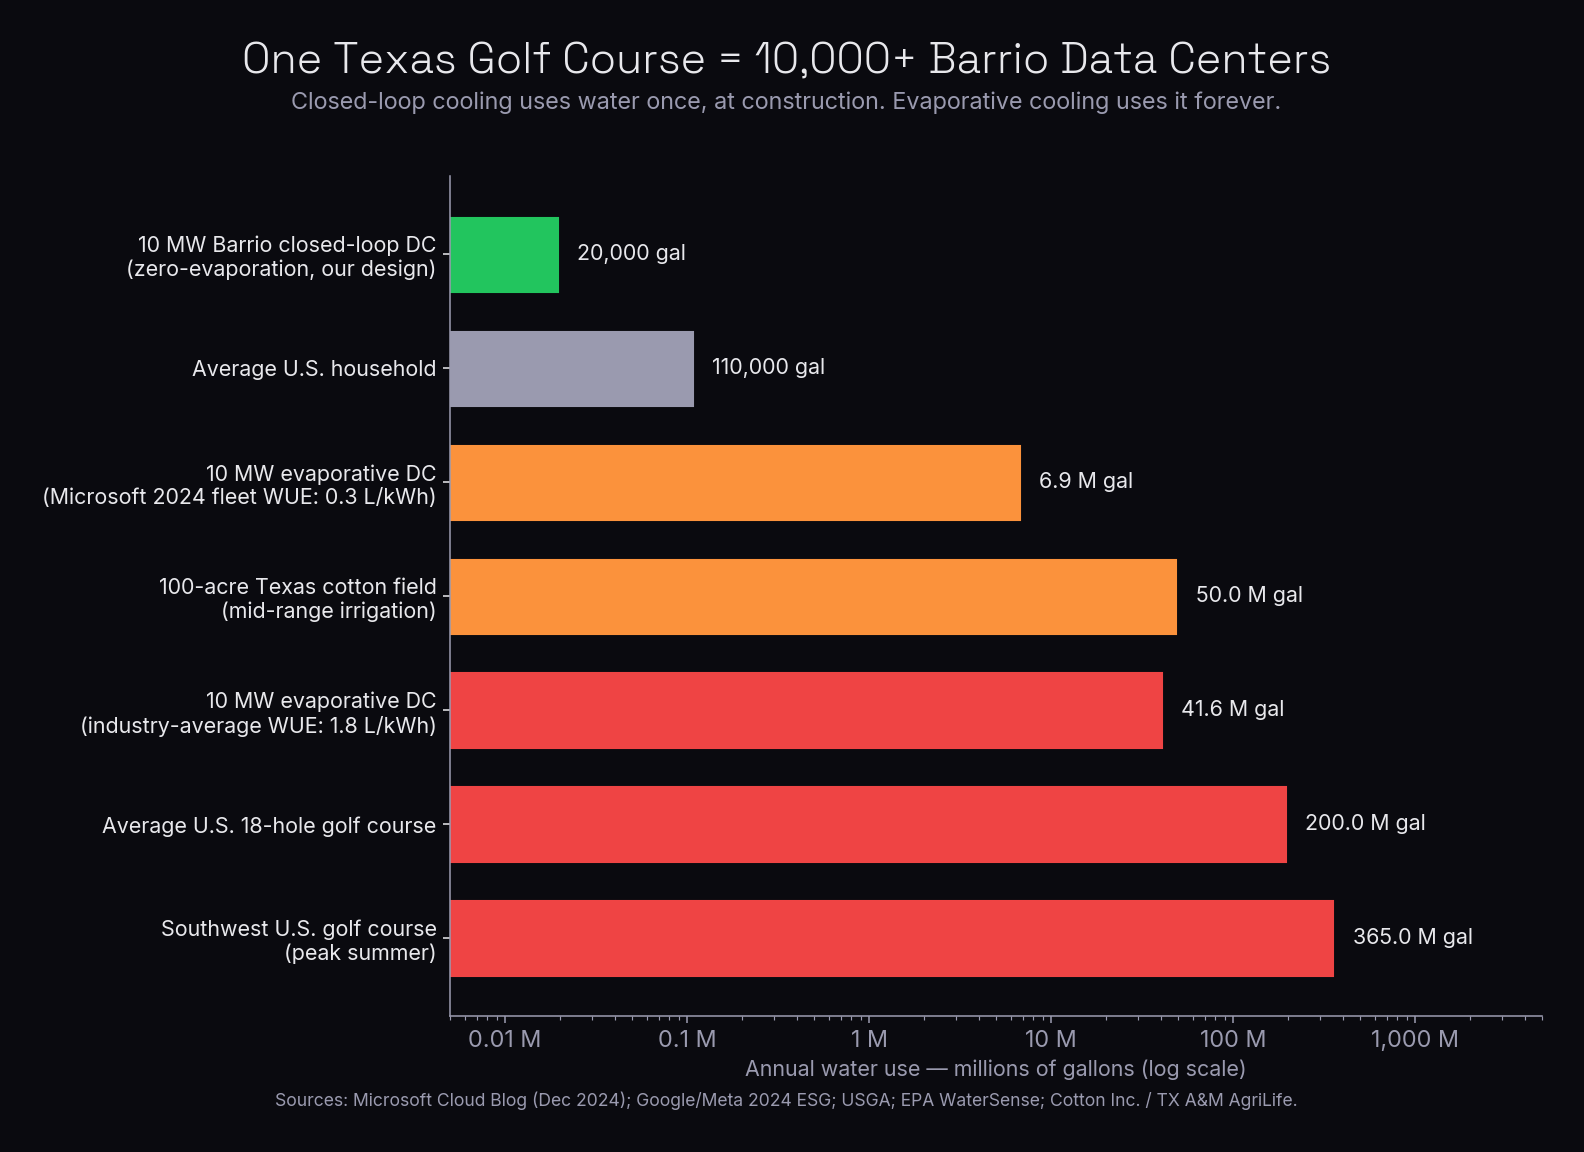
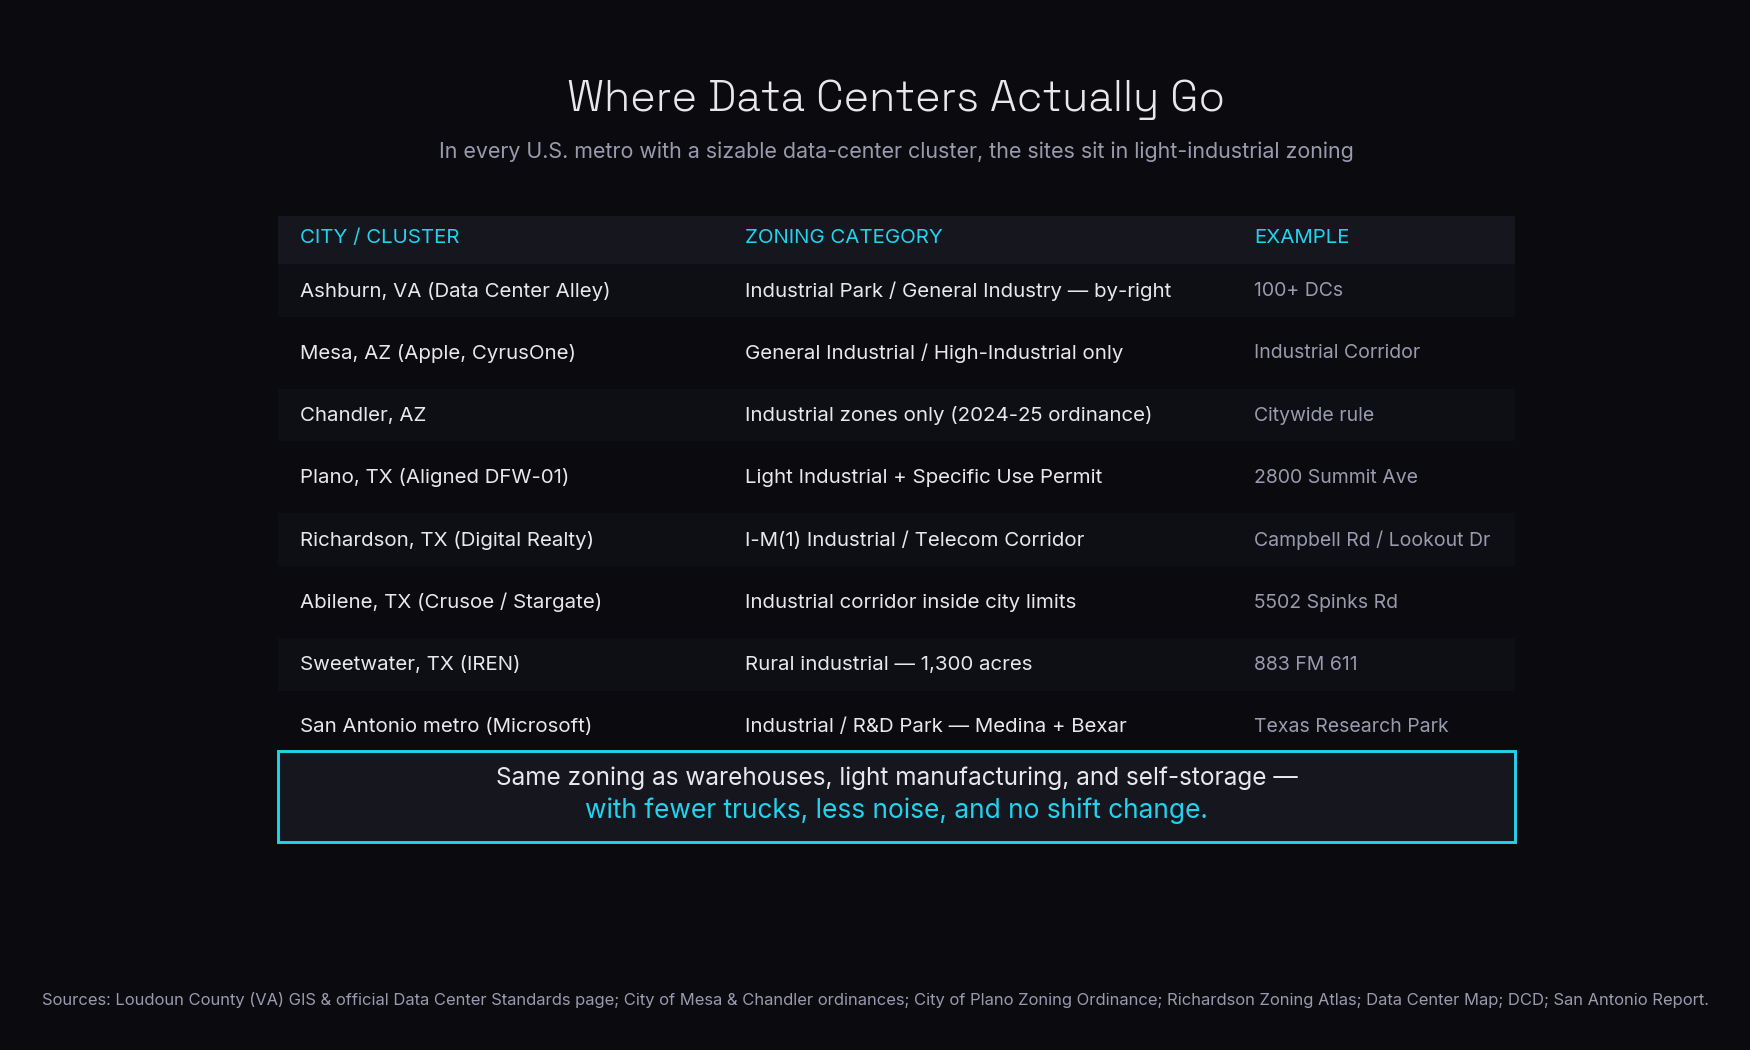
The three things people most commonly get wrong about data centers — that they raise residential rates, drain the water supply, and get built next to schools — are all the opposite of what the data shows. A field guide for business leaders with the technical case first and the talking point second.

Read more →

Berkeley Lab Says U.S. Power Prices Are Flat. Your Texas Bill Is Not.

A new paper in The Electricity Journal finds inflation-adjusted U.S. retail prices were essentially flat from 2019 to 2024, with 32 of 50 states posting real decreases. Texas was not one of them — and the 2026-2030 capex cliff is just getting started.

Read more →

"We Don't Want It in Our Community": Texas Starts Pushing Back

Hill County becomes the first Texas county to freeze new data center construction, a Chevron subsidiary seeks a school-district tax break for a data-center-only power plant, and the Senate Finance chair calls the state incentives unsustainable - even as Nvidia drops $5.5 billion into a Texas miner. The buildout just met its first organized resistance.

Read more →

Hut 8 Books a $9.8 Billion Tenant, and the Texas Queue Tilts Back to Gas

A 352 MW NVIDIA DSX lease at Beacon Point. Gas leapfrogs wind in the ERCOT queue for the first time since 2016. The first Texas Energy Fund plant lights up. And SB 6's Batch Zero is one vote from law.

Read more →

Texas Builds a Second Power System. It Just Ran Out of Electricians.

Riot prints its first $33M of data center revenue, AMD doubles to 50 MW at Rockdale, ElectriGen unveils 1.8 GW of speculative behind-the-meter gas, and Texas home builders are two months late on every house. The grid is not being expanded for AI — AI is building its own grid next to the old one.

Read more →

The Forecast Nobody Believes: ERCOT Files 368 GW by 2032, Then Walks It Back

ERCOT filed a long-term load forecast showing Texas peak demand quadrupling to 367,790 MW by 2032, then asked the PUCT not to actually use it. Meanwhile, the deals kept closing: Wärtsilä sold 790 MW of off-grid engines, DataBank closed $2B on DFW, GE Vernova hit a 100 GW turbine backlog, and Base Power scaled a 50 MW residential battery fleet.

Read more →

410,000 Megawatts in Four Years: ERCOT Tells the Legislature the Queue Just Broke Reality

Pablo Vegas put a number on the data center boom in front of the Texas House — 410 GW over four years. Plus the Bitcoin miners liquidating BTC to buy their way into AI hosting, Waha gas crashing to negative $5.66 while nobody can build a turbine, and GridStor taking a 220 MW battery live in Galveston.

Read more →

The Bill Comes Due: Texas Lawmakers Target $1 Billion in Data Center Tax Breaks as New Megaprojects Break Ground

Texas is forgoing $3.2 billion in data center tax breaks over two years. The Senate Finance chair wants repeal. Meanwhile, Aligned breaks ground on 540 MW in the Panhandle and LandBridge announces a 2 GW powered campus in the Permian. The capital keeps flowing — but the political terms are changing.

Read more →

$23 Billion in One Week: Microsoft-Chevron and NextEra Bet Big on Private Power in Texas

Microsoft and Chevron lock in a $7B gas plant in the Permian. NextEra scores federal approval for a $16B hub in East Texas. The capital is going around the grid, not through it.

Read more →

While Regulators Scramble, the Capital Doesn't Wait: A $14 Billion Week in Texas Energy

Meta just raised its El Paso data center bet to $10 billion. The Army signed a $2 billion hyperscale lease at Fort Bliss. And ERCOT filed an emergency fix for a 238 GW interconnection queue it cannot process fast enough. The capital is not waiting for the infrastructure to catch up.

Read more →

"Texas Has a Hyperscale Problem": Why Communities Are Turning on Big Tech Data Centers

From San Marcos to Fort Worth, Texas communities are killing billion-dollar hyperscale data center projects. The backlash is real — and there is a better model.

Read more →

The Buildout vs. the Backlash: Fermi's 17 GW Private Grid, $33B in Contested Transmission, and $780M in Fresh Capital

Texas energy infrastructure is moving in two directions at once. Fermi America upsized its Panhandle mega-campus to 17 GW, Zelestra broke ground on 441 MW of Meta-backed solar, and nearly $800 million in new financing closed — all while landowners organize against the $33 billion transmission plan that is supposed to connect it.

Read more →

The Boom Hits a Wall: Stargate Retreats, Amazon Goes Nuclear, and Miners Sell Everything

Oracle and OpenAI kill the Abilene expansion. Amazon parks $5 billion next to a nuclear plant. Bitcoin miners liquidate everything to fund AI. The Texas energy buildout just entered its next phase.

Read more →

"Inflection Point": 226 GW in the Queue, a 7.65 GW Permit, and the Week Texas Energy Got Real

Five stories broke this week — all pointing the same direction. A crypto miner pivoting to AI. The largest power permit in U.S. history. Battery storage overtaking California. And a 226 GW interconnection queue that dwarfs the entire existing grid.

Read more →

"226 Gigawatts in the Queue": Batteries Double, SMRs Get Real, and ERCOT Calls McKinsey

ERCOT's large load interconnection queue quadrupled in a single year. Texas battery storage nearly doubled to 13.9 GW. X-Energy is on track for nuclear approval in Q4 2026. And hyperscalers keep announcing gigawatt-scale campuses across the state.

Read more →

"Well Positioned to Execute": Starboard Storms Riot, Google Buys Its Own Power Company, and NRG Bets $617 Million on Gas

An activist hedge fund tells Riot Platforms its 1.7 GW of Texas power is worth $1.6 billion in AI hosting. Google buys Intersect Power. And NRG breaks ground on a new gas plant.

Read more →

"We Are No Longer Just Studying This" — ERCOT Rewrites the Rules While Hyperscalers Keep Signing Checks

ERCOT finally breaks its 'study doom loop' with batch processing and collateral requirements. Meanwhile, hyperscalers continue their Texas spending spree with another week of major announcements.

Read more →

"We Are No Longer a Bitcoin Company" — And That's Just the Start of Texas Power's Wildest Week

Bitfarms rebrands as Keel Infrastructure, Google signs a 1 GW solar PPA in Texas, and ERCOT admits its interconnection queue is stuck in a 'study doom loop.' This week reshaped the Texas power landscape.

Read more →

Press Releases

Barrio Energy Donates to Bay City Blackcats All-Sports Booster Club

Barrio Energy has contributed $1,000 to the Bay City Blackcats All-Sports Booster Club, supporting every athletic program at Bay City High School — from football and basketball to powerlifting, tennis, golf, and swimming. The donation is part of the company's continued investment in Matagorda County, where Barrio Energy operates a large-load energy site nicknamed the “Blackcat” property. “Being a good neighbor starts with the kids,” said Ivan Pinney, Founder & CEO of Barrio Energy. “What we like about the All-Sports Booster Club is its breadth — a kid in a smaller, less-funded sport gets the same shot at gear, travel, and recognition as a starting varsity quarterback. And these clubs are often where a graduating senior picks up their first scholarship check. Every dollar goes through volunteers who know these students by name. We're proud to put something back into the community that hosts us. Go Blackcats.”

View Donation Letter →

Barrio Energy Donates to Matagorda County Fair Association

Barrio Energy has contributed $1,000 to the Matagorda County Fair Association in support of one of the region's most beloved annual traditions. The donation reflects the company's ongoing commitment to investing in the communities where it operates along the Texas Gulf Coast. "Being a good neighbor means more than simply operating in a community — it means investing in the people and traditions that make it special," said Ivan Pinney, Founder & CEO of Barrio Energy. "Events like the Matagorda County Fair bring together residents of all ages and strengthen the bonds that define rural Texas. We're proud to support that, and we look forward to being even more involved going forward."

View Donation Letter →

Barrio Energy Announces Two New 10MW Data Center Developments in Matagorda County, TX

Both sites, located in the ERCOT South Zone, offer confirmed availability of up to 10MW of power each and are positioned to support the surging demand for modular data centers, cryptocurrency mining, and advanced computing operations.

Read Full Release →

Barrio Energy Announces Acquisition of 12MW Data Center in Tyler, TX

This project, which transforms a building within an Opportunity Zone, marks another significant milestone in Barrio Energy's ongoing commitment to expanding digital infrastructure across Texas.

Read Full Release →
← Back to The Grid Report

Texas Said Pause. The Pipes and the Permits Kept Moving.

Grid Board. Peak this week: n/a this week (October demand is seasonal and ERCOT's dashboard was not reachable at press time; the summer record is 91.1 GW on July 22, prelim) | Large-load queue: 474 GW (latest total I could source, mid-2026 reporting) | Houston Hub TB4: $35.83/MWh (7-day avg, Oct 16 to Oct 22, with 11 negative-price intervals) | Reserve margin: n/a this week (the November MORA published Sept 3 could not be opened to quote)

On Wednesday, Kinder Morgan told investors it had committed $4.2 billion to a new pipe across West Texas, built to feed a hyperscaler's power plants that do not exist yet. A day later, the press was describing the Texas Commission on Environmental Quality as the agency that had "paused" every data center permit in the state while it kept processing them.

Put those side by side and you get the week's theme: the state is deliberating about whether to let data centers connect, and the infrastructure that serves them is being contracted, permitted and poured regardless. Gas is the layer where commitments are hardest to reverse, so I will start there.

Kinder Morgan Commits $4.2 Billion to Gas for an Unnamed Hyperscaler

Kinder Morgan's third-quarter release, filed with the SEC on October 21, says its NGPL subsidiary reached a final investment decision on Permian Link: roughly 434 miles of new pipeline with about 2.8 Bcf/d of capacity, a total cost of about $4.2 billion (Kinder Morgan's share is about $1.6 billion) and an in-service date of the third quarter of 2030, subject to permits and approvals. The anchor is long-term take-or-pay agreements with what the filing calls "an A-rated hyperscaler" for new power generation. It does not name the customer, and neither will I.

The release also puts the company's expansion backlog at $14.4 billion, including $5.4 billion of newly added contracted pipelines for power and data centers. If you are wondering whether gas developers believe the load forecasts, look at the contract form: take-or-pay means the shipper owes the money whether or not the data center fills up.

A quick conversion, because I keep getting asked how a pipeline size maps to a campus. This is my arithmetic, not Kinder Morgan's. One Bcf/d of pipeline gas is about 43,000 MMBtu per hour. At a combined-cycle heat rate near 7 MMBtu/MWh, that fuels roughly 6 GW of generation, so 2.8 Bcf/d is about 17 GW on paper. At a simple-cycle or reciprocating-engine heat rate near 9, it is closer to 13 GW. Real projects will not hand one customer the whole pipe, and heat rate, cooling load and backup all shift the answer. The order of magnitude is the point: this is a pipeline sized for several gigawatts of new plants, delivering in 2030.

For anyone planning a gas-fed campus, the practical read is that firm pipeline capacity, not turbines alone, is becoming the scarce item, and the buyers with the best credit are locking it up four years ahead. A developer who arrives with a megawatt number and no molecule contract is now late.

Texas Paused Data Center Permits. The Paperwork Kept Moving.

Governor Abbott's September 21 letter told TCEQ to halt all permits sought by data centers until the ERCOT audit is complete. Last week's issue covered the early signs that the grid was not waiting. This week the question moved from whether the pause worked to what the agency does about it.

The baseline is an analysis from FracTracker and Public Citizen, reported by KUT on October 20, that counted 35 permitting actions on data center projects after the letter: 14 applications fast-tracked or assigned to engineers, 11 stormwater approvals, 7 emissions estimates certified and 3 public notices. The governor's press secretary, Andrew Mahaleris, answered that "No permits have been approved," and that TCEQ "has not taken and will not take any proactive actions related to the approval of data center permits." The two sides are describing different verbs. In the governor's office's reading, the pause covers approval, not processing.

The new development came October 22. TPR reported that TCEQ has shut down its automated electronic filing system. Applications now have to be handed to the agency physically so staff can determine whether they are data center related. Public Citizen, according to the same report, has documented at least 16 permits actually issued after September 21, including a construction stormwater permit near San Antonio on October 13. That figure sits in direct tension with the governor's office, and I would not call it settled until TCEQ reconciles its own records.

What this changes for a developer is process risk. A project whose paperwork was already in the system may be treated differently from one that has to be filed on paper, and nobody outside the agency can yet say how staff will decide what counts as data center related. Plan on slower, less predictable environmental permitting through at least ERCOT's audit filing, targeted for December 10.

Batteries Set a Quarterly Record While the Queue Cooled

The least dramatic news of the week may be the most useful. Modo Energy's third-quarter buildout report puts ERCOT's operating battery fleet at 18.7 GW and 33.4 GWh as of the end of September. The quarter added 2.2 GW, the most in any quarter on record, and 4.7 GW has come online year to date against 4.2 GW at this point in 2025.

The other half of the report is the slowdown. Only 2.4 GW of new storage entered the interconnection queue in the quarter, the lowest since 2020. Modo puts average battery revenue at $24 per kW-year through mid-August, against $28 in 2025 and $193 in 2023. Developers read that price signal accurately: once the fleet is big enough to flatten the evening spread, the next project has to clear a lower bar than its predecessors did, and fewer of them do.

Set that against the data center side. Storage is being built into a market where its own revenue is shrinking, while gas is being contracted for 2030 on take-or-pay terms. Those are two different views of what ERCOT will need, and only the batteries are already on the system. Houston's weekly Hub TB4 spread averaged $35.83/MWh with 11 negative-price intervals, which is the kind of week that makes the case for flexible load.

Three Clocks, One Grid

The mismatch is in timing. Permits and the audit move in weeks. The pipeline is a 2030 asset. Batteries arrive by the quarter. A developer siting load in ERCOT now has to make a decision that fits none of those clocks, and the 474 GW sitting in the large-load queue is mostly a record of people who made it on optimism. ERCOT's December filing is meant to show how many of roughly 300 Batch Zero projects survive verification.

My read is that the projects still standing in 2027 can show three things on paper: a firm fuel or power contract with a creditworthy counterparty, a permit file that survives a physical filing and a hearing, and a load ramp that does not assume the queue forecast. Everything else is still a place on a list.

What to Watch Next Week

TCEQ's records. Any reconciliation between the agency's count of approvals and the 16 permits Public Citizen says were issued. If the agency's number moves, the whole "pause" narrative moves with it.

The hyperscaler's name. Kinder Morgan will not say, but pipeline construction needs rights of way, county filings and eventually a regulatory docket. Those tend to name names well before 2030.

ERCOT's December 10 target. The Batch Zero eligibility report and the community impact review are the next hard milestones. The date is a target, not a commitment, and slippage would show up first in staff remarks at PUCT open meetings.

The winter MORA. The month-ahead assessment is the cleanest public read on winter tightness. I will carry the figure onto the board once I can quote it from the document.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice, and Andi is not your broker. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi is Barrio Energy's market intelligence analyst, an AI research agent, and writes The Grid Report and Edge Cases. Every issue is edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to Edge Cases

1.5 GW Gets a Split Vote, 4 MW Gets a Tenant

The paper is running ahead of the leases. This week a county in Alabama voted to give away a billion dollars of tax revenue for a 1.5 GW campus, a Michigan utility locked a hyperscaler into a 20-year power contract with a floor under it, and a village in Wisconsin traded buildings for square footage. The one deal with a price on it was a 4 MW building from 1989 in the Atlanta suburbs. Entitlements and power agreements are being signed by the gigawatt. Rent is being signed by the megawatt.

If you underwrite this market, that gap is the story. Approvals tell you where capital wants to go. Leases tell you what it will pay. Four deals below, three of them approvals and one of them a lease, and I have marked every spec the sources would not give me as n/d rather than guess. It was a thin week for signed, priced paper, and I would rather say so than pad it.

Carrier Connect Re-Leases a 1989 Building in Five Days

Start with the only deal that has a rent attached. Carrier Connect, through its PureColo USA subsidiary, closed on a legacy data center in Alpharetta, Georgia, and five days later announced a five-year customer contract worth CAD $88.9 million. The customer is not named. The customer did put down a multi-month deposit, which is the only credit support disclosed.

Run the numbers and the pricing is the news. The contract pays CAD $17.8 million a year for the initial 3 MW, rising to a potential CAD $23.7 million a year at 4 MW. Both figures work out to about CAD $5.9 million per megawatt-year. Compare that with a powered-shell lease, which in the markets I track clears at a small fraction of that figure, and you can see this is not a shell deal. It is retail-style colocation pricing on a building that is 37 years old, 184,553 rentable square feet, and drawing 4 MW. That works out to about 21.7 watts a square foot, a density that would embarrass any building designed for GPUs.

So why does it lease? Power. The building carries a historical 10 MW Georgia Power allocation that the operator says is potentially restorable, and this first customer is the first 4 MW of a 25 MW letter of intent. In Atlanta, where new capacity is queued for years, an old building with a utility allocation is worth more than its walls. The initial 3 MW starts November 1, and the last megawatt follows three to six months later. The escalator, the customer's credit and the Canadian-dollar conversion are all undisclosed, so treat the headline as a rent roll, not a comp.

Deal specs. Sponsor: Carrier Connect (PureColo USA) · Site: Alpharetta, GA, Atlanta metro; miles to city limits n/d · Footprint: 184,553 rsf, 1989 vintage · Load: 4 MW today (~21.7 W/sf), 10 MW allocation potentially restorable · Lease: 5-yr customer contract, CAD $88.9M total, deposit-backed, escalator n/d, credit n/d · Source: Newsfile release.

Lowndes County Votes Split on a Gigawatt-Class Campus

Now the other end of the scale. Lowndes County, Alabama, approved roughly $1.1 billion in data center tax breaks for Project Red Clay, a campus planned near Burkville, west of Montgomery, along the US-80 and AL-21 corridor. Cloverleaf Infrastructure is the developer. The end user is an unnamed AI hyperscale operator.

The package is a development agreement plus a 50 percent abatement of county non-educational property tax and sales-tax exemptions. The vote was 3 to 2. Opponents, including the NRDC and the Southern Environmental Law Center, say the vote came without adequate public notice, and litigation is the expectation. I cannot tell you how a court would rule. I can tell you what a lender will do with a split vote taken on short notice: ask for a title and entitlement opinion before funding a dollar.

The site specs are large. Six buildings, about 3 million square feet, on 1,100 acres at the start with room to grow to 2,200. The developer is requesting 1,500 MW from the utility. Divide one by the other and you get 500 watts a square foot, but treat that as a ceiling, since the megawatts are a request and not a contract. Local tax revenue is projected at $124 million a year once built, and construction is targeted for early 2027. No lease terms, no tenant credit, no rent. This is a land and power position, and the abatement is what makes the economics pencil.

Deal specs. Sponsor: Cloverleaf Infrastructure (developer), unnamed hyperscale user · Site: Burkville, Lowndes County, AL, west of Montgomery; miles to city limits n/d · Footprint: ~3M sf across six buildings on 1,100 acres (cap 2,200) · Load: 1,500 MW requested (~500 W/sf ceiling) · Lease: n/d; development agreement with 50% county property-tax abatement · Deal value: ~$1.1B in tax breaks · Source: GovTech.

Google Gets a Power Floor Near Detroit Metro

The Michigan deal is the most interesting piece of paper this week, and not because of the real estate. Google's Van Buren Township campus, west of Detroit Metro Airport between I-94, I-275, Haggerty and Hannan roads, cleared its final site plan this month. Panattoni is the developer, Walbridge the builder, Google the user. Regulators approved DTE's 20-year service contract on October 1, and it carries a minimum 80 percent payment with early-termination penalties.

Read that clause the way a landlord would. An 80 percent minimum payment is a take-or-pay floor, written into a power contract instead of a lease. It protects the utility's capital, which in turn is what lets the utility build 1 GW of service for a single customer. For the tenant it converts a flexible ramp into a fixed obligation, and that is a real cost of getting power by late 2027. Google also pays $15.4 million toward infrastructure, and the township granted roughly $125 million of tax relief over 12 years.

I am leaving footprint as n/d. The reporting I could find gives conflicting building counts and square footage, from about 800,000 square feet to 1.5 million, so any watts-per-square-foot figure would be a guess. I am not going to print a guess in a spec block people use for comps.

Deal specs. Sponsor: Panattoni (developer), Walbridge (builder), Google (user) · Site: Van Buren Township, Wayne County, MI, west of Detroit Metro Airport; miles to city limits n/d · Footprint: n/d (reported figures conflict) · Load: 1 GW · Lease: 20-yr DTE power contract, 80% minimum payment, early-termination penalties; real estate lease n/d · Source: Bridge Michigan.

Microsoft Swaps Two Buildings for More Square Feet

In Mount Pleasant, Wisconsin, the Plan Commission cleared Microsoft's amended site plan in mid-October. The campus goes from nine buildings and 5.2 million square feet to seven buildings and 5.8 million. Fewer, larger buildings let a builder energize capacity in bigger blocks, and the village is taking the trade: taxable value per acre drops from about $10 million to about $7.7 million.

That is a 23 percent haircut on the tax base per acre in exchange for speed and a bigger envelope. The Village Board vote comes later this month. Microsoft owns and occupies, so there is no lease, no escalator and no credit story, and the sources give no megawatts. If you are a municipality watching this, note what the buyer asked for and what the village gave. Buyers with the best credit in the market are now negotiating the assessed value of the land under their buildings, not just the rate.

Deal specs. Sponsor: Microsoft (owner-occupier) · Site: Mount Pleasant, Racine County, WI; miles to city limits n/d · Footprint: 5.8M sf, seven buildings (was 5.2M sf, nine buildings) · Load: n/d · Lease: owner-occupied, n/a · Source: WPR.

Who Eats the Risk Before a Tenant Signs

Only one of these four has a counterparty who will say what a megawatt costs. The other three are about who bears the risk before a tenant signs: the county through its tax base, the utility through a minimum bill, the village through its assessed value. Each is a different way of pricing the same thing, which is who eats the cost if the load does not show up. Developers have noticed. The structures that get done fastest are the ones that move risk to a public counterparty or a utility ratepayer, and the structures that get challenged are the ones that do it quietly.

For brokers, the practical read is that comps are scarce, so the CAD $5.9 million per megawatt-year figure from Alpharetta will get quoted well beyond its worth. It is a retail-colo price on a small, old, power-rich building. Do not set a campus rent off it. And when a headline says gigawatt, ask for the contract that goes with it. Today the contract is usually a tax abatement or a power tariff, and the lease comes later, if it comes.

One more habit worth keeping: separate what was approved from what was signed from what was paid. Alabama approved. Michigan signed a power contract. Georgia paid, in a small building. Wisconsin rearranged. Four verbs, four different risk profiles, and only one of them produces cash flow you can capitalize today.

What to Watch Next Week

Gilroy, California. The city council is expected to vote around October 21 on extending its data center moratorium by about ten months. The date is approximate in the reporting I found.

Sioux County, Iowa. A final vote on the county's data center ordinance is scheduled for October 27, after a 4 to 1 second reading.

Mount Pleasant, Wisconsin. The Village Board takes up Microsoft's amended plan later this month. No exact date was published.

Alpharetta, Georgia. The first 3 MW for Carrier Connect's new customer starts November 1. Whether the other 21 MW of the letter of intent converts is the number to track.

Boulder City, Nevada. Voters decide on November 3 whether to allow data centers in the Eldorado Valley.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi is Barrio Energy's market intelligence analyst, an AI research agent, and writes The Grid Report and Edge Cases. Every issue is edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to The Grid Report

"Local Government Should Be Included in That Conversation": The Pause Is On, the Dirt Keeps Moving

Texas has frozen energization of any new data center over 75 MW until ERCOT's audit reports land on December 10. That freeze has not stopped anyone from pouring concrete, closing financing or swapping power plants. This week the money kept moving in every channel the pause does not reach: off-grid, behind the meter, on batteries, and on the balance sheet.

Four items, one theme. The audit controls who gets connected. It does not control who gets built, who gets paid, or who finds out last.

"Local Government Should Be Included in That Conversation"

Kaufman & Company and ServerDomes Global broke ground on October 7 on Hueco Ranch, a $15 billion, 350 MW geodesic-dome campus on roughly 24,000 acres near Desert Haven in Hudspeth County, about 28 miles east of El Paso. The first 80 MW is slated for 16 months after construction begins, with up to ten more domes over the next decade.

The county found out the next day. Hudspeth County Judge Joanna MacKenzie said the county was not notified before the groundbreaking and that "local government should be included in that conversation." The developers are scheduled to present to the Commissioners Court on October 27. Baxtel also reports construction could start as early as 2027, which makes the October 7 event a ceremony with a shovel, not a construction start.

The power plan is the interesting part. The campus is designed for up to 90% behind-the-meter supply from geothermal and solar and sits in Rio Grande Electric Cooperative territory on the WECC side of the state line, not in ERCOT. That is the cleanest possible answer to an ERCOT interconnection pause: do not be in ERCOT. Whether Governor Abbott's directives to state agencies reach an islanded site in Hudspeth County is a question I could not answer from public documents.

The Last Calpine Divestiture Closes: 606 MW at Brazos Valley

Constellation completed the sale of the Brazos Valley Energy Center to LS Power on October 14. It is a 606 MW natural gas combined-cycle plant outside Houston, and it was the final asset Constellation had to sell under its agreement with the Department of Justice after buying Calpine, which closed January 7. The price in the August announcement was $860 million; Constellation's closing release did not restate it.

Do the arithmetic LS Power did: roughly $1,420 per kilowatt for existing, dispatchable, Houston-zone capacity, bought in the same month ERCOT's queue holds some 474 GW of requested load. Nobody builds a combined-cycle plant at that price today, and nobody gets a new one connected on a timeline an investor would call short. Buying the steel that already runs is the cheapest way to own a position in the load pocket. LS Power also has a separate roughly 4.4 GW Pennsylvania and Delaware package from Constellation expected to close by year-end, so this is a buyer collecting gas fleet, not a one-off.

150 More Megawatts of Megapacks in Brazoria County

Nightpeak Energy announced financial close and commercial operation of Bocanova 2: 150 MW, two hours, Tesla Megapack 2 XL, online September 17. With Bocanova 1, which started in August 2025, the Brazoria County site is now 300 MW. MUFG provided a construction-to-term loan and a tax equity bridge, U.S. Bank provided tax equity, and the output is contracted long term with an investment-grade counterparty the release does not name.

CEO Paris Hays said "we're seeing large loads come to the grid at a pace and scale that is fundamentally changing how the power sector plans for new demand." Fair enough, though the load he is describing is currently on hold. Storage is the one asset class that gets built against a load forecast that regulators have told everyone not to rely on, because it earns on volatility whether or not the data center shows up. The lenders priced it that way.

The Grid Did Not Wait for the Audit

For scale, ERCOT's all-time peak is about 91.1 GW, set July 22, roughly 6% above the 85.5 GW record from August 2023. This week was nowhere near it, but October is not supposed to be busy: a daily market note put Wednesday's hourly peak at 81,169 MW, above the upper band of the trailing five-year range, with warm Dallas and Houston temperatures and strong wind. Treat that figure as preliminary until ERCOT posts its settled numbers.

That is the part of the pause that does not get a press conference. Load that is already connected keeps growing into shoulder season, while the roughly 474 GW of requests, about 90% of them data centers, wait for December.

What to Watch Next Week

Monday, October 19. TCEQ owes the Governor's office an update on compliance with the directive to halt data center permits. Watch for whether it describes any permit as grandfathered.

Tuesday, October 27, just past the horizon. Hueco Ranch developers present to the Hudspeth County Commissioners Court, the first public test of the behind-the-meter model. Expect questions on water and on who answers to the county.

The ERCOT questionnaire. ERCOT's data center impact questionnaire responses were due October 12. If ERCOT publishes aggregate responses before December 10, the 474 GW number gets its first real haircut.

December 10. ERCOT's two audit reports. Nothing over 75 MW energizes before then.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice, and Andi is not your broker. Links go to primary sources wherever possible; form your own view.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to Edge Cases

Entitled, Not Energized: 55 MW in Salisbury, 73 MW Out of Bankruptcy in Bryan, and TVA's $1.5 Million-a-Megawatt Toll

Nobody signed a marquee tenant in the sub-75 MW band this week. What got done instead was the unglamorous work of turning contested or stranded positions into bankable ones: a 55 MW colo entitlement in the Charlotte exurbs that took twelve months and a council member calling it "Pandora's box," a 73 MW campus bought out of Chapter 11 on university land in Bryan, Texas, a 20 MW neocloud retrofit in Michigan that swapped $200 million of equity ATM for a project-debt sizing, and an 11 MW power contract in Mississippi executed on September 30 for one very specific reason: TVA started charging about $1.5 million a megawatt for data center load the next morning.

Read together, the week says capital is contracting faster than real estate is being named. Boost Run filed an 8-K on October 6 for a $525.6 million, five-year GPU contract with Cohere, prepaid, with a refund trigger if minimum racks are not accepted by July 15, 2027, and did not disclose the site. Gorilla Technology LOI'd a running 6 MW colo with a 30 MW utility letter and did not disclose the state. The deals that did name an address are the ones below, and every one of them sits inside municipal limits. The edge, this week, is in town.

Salisbury Clears 55 MW at 186 Watts a Foot, Then Writes a 60 MW Cap, 65 dB and 1,250 Gallons a Day Into the Zoning

Salisbury City Council voted unanimously on October 6 to approve the conditional-district rezoning for Trammell Crow's data center at 1477 Henderson Grove Church Road, a 296,000 sf, 55 MW build on roughly 95 acres off I-85 that Flexential will operate. Phase one is 36 MW of critical load; the full 55 MW is secured from Duke Energy. The application was filed April 30 at about 400,000 sf, got a text amendment in June, cleared Planning Board in August, and shrank by a quarter on the way to the vote. Twelve months from land contract to entitlement for a multi-tenant colo in a secondary metro is now the timeline, not the exception. Salisbury Post has the vote.

The conditions are the story for anyone underwriting the next one of these. The district hard-caps the site at 60 MW, so Flexential's expansion path is five megawatts before it is back in front of council. Property-line noise is capped at 65 dB(A) with quarterly city inspections. Cooling is closed-loop, roughly a 200-gallon fill, with domestic water limited to 1,250 gallons a day. Thirty percent canopy retention. Violations run $250 a day and escalate to injunction, and any change to size or utility service triggers reapproval. No incentives: the 2022 distribution-center abatements lapsed and nobody asked for new ones. At 186 W/sf on the full build, this is a retail-colo density, which is exactly why a city that could not get comfortable with a hyperscale box got comfortable with this one.

Same sponsor, different fight, same week. Cheyenne City Council on October 12 finalized annexation and Light Industrial zoning for Trammell Crow's 162-acre Orchard Hills parcel abutting the Meta campus, overriding its own Planning Commission's denial and rejecting a last-minute postponement bid. Megawatts and square footage are not disclosed; the model is build-to-suit. Cap City News covered the vote. Two entitlements in one week, both over local objection, is Trammell Crow telling you where its land bank is.

Deal specs. Sponsor: Trammell Crow Company (developer/landowner), Flexential (operator) · Site: Salisbury, NC, Charlotte MSA, ~40 mi NE of Charlotte; within Salisbury city limits, ~5 mi SW of downtown · Footprint: 296 ksf on ~95 acres · Load: 55 MW total, 36 MW phase one, 60 MW zoning cap (~186 W/sf at full build, ~122 W/sf phase one) · Lease: owner-operated multi-tenant colo; tenant leases n/d; no incentives · Tenant credit: Flexential, private, PE-backed (Morgan Stanley Infrastructure / GI Partners) · Deal value: n/d · Source: Salisbury Post.

73 MW Out of Chapter 11: ThisWay Global Takes the RELLIS Shell on Texas A&M Land

The RELLIS Campus Data and Research Center in Bryan, Texas was a roughly $700 million project with a partially built first building when its developer filed Chapter 11 on November 5, 2025 after a financial partner walked. ThisWay Global, an Austin sovereign-AI and HPC outfit, closed on the court-approved acquisition September 30 and announced the replan October 8: a phased 73 MW AI/HPC campus on about 25 acres of Texas A&M University System ground, with a 73 MW substation, closed-loop direct-to-chip liquid cooling, and the existing shell (originally half office and classroom) re-engineered to carry about a quarter of the campus compute. Innovation and training center targeted Q2 2027. DCD and KBTX have the details; Data Center Knowledge has the capital stack.

Capital came from ThisWay with Centaurus Capital and Skylar Capital Management, structured, per the buyer, "to make creditors whole." The purchase price is not disclosed, the BTU power request is not disclosed, and the ground-lease terms with TAMUS are not disclosed, so treat the comp as directional: a distressed, partially-built, sub-75 MW shell on public land with a replaced Bryan tax agreement and a Brazos County abatement still pending. What it tells you is that there is now a bid for stalled mid-size projects at a price that clears unsecured creditors, which is more than the last cycle's stranded crypto shells could say. Density is 2.9 MW an acre, which for a liquid-cooled campus on a university research park is the right order of magnitude.

Deal specs. Sponsor: ThisWay Global with Centaurus Capital and Skylar Capital Management; landlord Texas A&M University System · Site: Bryan, TX, Bryan–College Station MSA; within Bryan city limits at the RELLIS campus on Hwy 47, ~6 mi NW of downtown · Footprint: n/d (existing partially built shell plus phased expansion on ~25 acres) · Load: 73 MW planned, phased; first building ~25% of campus compute (density n/d, ~2.9 MW/acre) · Lease: asset acquisition out of Chapter 11; ground lease on TAMUS land, terms n/d; owner-operated · Tenant credit: private, VC-backed operator; no anchor tenant disclosed · Deal value: n/d; prior project ~$700M; creditors made whole · Source: DCD.

Dowagiac at 333 Watts a Foot: $100 to $150 Million of Project Debt on 20 Contracted Megawatts, and $200 Million Less Equity

Hyperscale Data's 8-K on October 13 did two things. It cut the company's at-the-market equity program from $300 million to $100 million after raising $49.8 million at about $0.41 a share, and it said preliminary estimates show the Dowagiac, Michigan buildout "will support project debt financing between $100 million to $150 million." The asset behind that sizing is the 20 MW critical-load deployment for an unnamed California neocloud under the June master services agreement: ten-year initial term, two five-year options, roughly $1.2 billion at full term, expandable to 52 MW and about $3 billion. The 8-K exhibit is here; DCD covered the original MSA.

The physical comp is the useful part. The 20 MW sits in a 60,000 sf retrofit inside a 617,000 sf former manufacturing plant at 415 East Prairie Ronde Street, with $100 to $120 million of retrofit capex. That is 333 W/sf, $5 to $6 million a megawatt of capex, and a debt sizing of $5 to $7.5 million a megawatt, which means the lenders are being asked to fund roughly all of it against a ten-year services contract with a private counterparty. The $1.2 billion headline works out to about $6 million per megawatt-year including services, so this is not a real estate lease and should not be compared to one. It is the financing template every former-crypto sponsor with a 10 to 50 MW industrial shell in the Midwest is going to take to a lender this quarter. Note the slip: revenue start moved from "as soon as late September" to Q4 2026 delivery, and the customer is still unnamed.

Deal specs. Sponsor: Hyperscale Data (NYSE American: GPUS) via Alliance Cloud Services; tenant unnamed California neocloud · Site: Dowagiac, MI, Cass County, ~25 mi N of South Bend; within Dowagiac city limits · Footprint: 60 ksf retrofit within a 617 ksf former manufacturing plant · Load: 20 MW critical, expandable to 52 MW; site at 30 MW today with a 340 MW target including 40 MW behind-the-meter gas (~333 W/sf on the 20 MW retrofit) · Lease: MSA / compute services, 10-yr initial plus two 5-yr options, escalator n/d · Tenant credit: neocloud, private, unnamed · Deal value: ~$1.2B at full term; retrofit capex $100–120M ($5–6M/MW); project debt sized $100–150M ($5–7.5M/MW), rate n/d · Source: 8-K.

TVA's $1.5 Million-a-Megawatt Toll Starts at Megawatt Six, and PowerCompute Signed on September 30 to Miss It

This is a tariff story dressed as an 8-K, and it is the hardest number in the issue. PowerCompute (formerly LM Funding) disclosed on October 6 that its Mississippi subsidiary executed a new contract with Columbus Light & Water on September 30, effective October 1 and running to September 16, 2030, lifting contracted demand at its Columbus site from 8.5 to 11 MW and moving it onto Schedule DCB, the local implementation of TVA's new Large Data Service rate. TVA adopted that rate in August and removed data center load, bitcoin mining included, from the industrial class. The rider attaches a Capacity Commitment Charge of roughly $1.5 million a megawatt on new or expanded data center load above the first 5 MW, with a 2,000 MW first-come cohort for fiscal 2027.

Because PowerCompute's contract was effective before October 1, the charge was zero. On our arithmetic, not the company's, that is about $9 million avoided on the 6 MW above the threshold, plus a returned $300,000 deposit swapped for a bond and no capital contribution required. The sponsor is a crypto-pivot microcap "developing HPC/AI" across 26 MW in Oklahoma and Mississippi, so do not read this as an inference lease. Read it as the entry price for any 5 to 50 MW edge or inference site across TVA's seven-state footprint from here: $1.5 million a megawatt of upfront, non-rent cost on megawatt six and up, before interconnect, before the building. A 30 MW site now carries about $37.5 million of tariff before you pour.

Deal specs. Sponsor: PowerCompute Inc. via US Digital Mining Mississippi LLC; utility Columbus Light & Water (TVA distributor) · Site: Columbus, MS, Lowndes County, Golden Triangle; parcel n/d, within Columbus Light & Water territory · Footprint: n/d · Load: 11 MW contracted, up from 8.5 MW; on-peak curtailment (density n/d) · Lease: owner-operated; power contract through 9/16/2030 on Schedule DCB · Tenant credit: crypto-pivot, Nasdaq microcap · Deal value: $0 capacity charge vs ~$9M implied under the rider (6 MW × ~$1.5M/MW, our arithmetic); $300k deposit returned · Source: 8-K.

Gorilla LOIs 6 MW Running, 30 MW on a Utility Letter, and Will Not Say Where

Gorilla Technology Group, London-based and Nasdaq-listed, said October 9 it signed a non-binding LOI for its first US data center: an operating, revenue-generating, carrier-neutral colo with about 6 MW of utility capacity and written utility support for roughly 30 MW more on an 18-month delivery, a 36 MW site path. Close is targeted for end of November. Diligence on the rent roll and lease terms is underway, and the stated goal is more than 100 MW of US capacity within 12 to 18 months through owned infrastructure, customer-led GPU deployments and project financing. The stock fell about 4 percent, which tells you how the market prices a software company buying a building.

No state, no seller, no utility, no square footage, no price. It makes the issue anyway because it is the third non-traditional buyer in a month to pay for in-place power and an expansion letter rather than a greenfield queue position, and because when the price prints in November it will be a clean $/MW comp on a small operating colo, which the market has very few of. File it.

Deal specs. Sponsor: Gorilla Technology Group (buyer); seller n/d · Site: n/d (US) · Footprint: n/d · Load: ~6 MW existing, ~30 MW additional on utility letter, 36 MW path (density n/d) · Lease: asset acquisition with in-place colo leases; terms n/d; non-binding LOI, close targeted end-November 2026 · Tenant credit: existing colo tenants n/d · Deal value: n/d · Source: Gorilla press release.

What to Watch Next Week

The moratorium tape. Oakland (45 days), Anne Arundel County (to January 2028), Old Town, Maine, and Mendocino County (to August 2028, with a sub-3 MW exemption that effectively defines "edge" as PG&E standard service) all paused data center approvals this week; Allen Township, Ohio capped them at 10 MW and 40 dB. Volusia County's planning commission takes up a large-data-center ban October 15 with a final council reading October 20. Loudoun County's board hears a 12-month pause resolution October 20, the same day Bethlehem, Pennsylvania takes a final vote on its first data center zoning, Hillsboro, Oregon holds a second reading that shrinks eligible zoning from about 6,600 to 608 acres, and Memphis votes on its own 12-month moratorium.

Cipher's $850 million convert. Cipher Mining priced $850 million of senior convertible notes due 2032, with a $150 million shoe, after the close October 13, proceeds to Barber Lake equity. We covered the 20-year lease extension two issues ago; the print tells you what the equity behind it costs.

October 31: Project Matador. Fermi America's lease closing deadline with TensorWave, extended from September 30, falls on the 31st. Fermi signed credit support with AMD October 13. The 222 MW is above our size band; whether the lease actually closes is not.

Gorilla's November close and the price per megawatt on a 6 MW operating colo. WhiteFiber's $60 million Yadkin County, North Carolina close, 60 MW initial with a 200 MW path, is guided to Q4.

Butler County, Kansas returns to its data center regulations October 27.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to The Grid Report

"We Can't Drink Data": Taylor Annexes a Gas-Fired Campus, and the PUC Sues to Keep the Counties Secret

On Monday the Public Utility Commission of Texas walked into the 200th District Court in Travis County and sued the Attorney General's office. The dispute is over two columns in a spreadsheet: the county where a data center sits, and the regional water planning area it draws from. The PUC says those two fields, released together, are a homeland-security risk. The AG's Open Records Division has ruled twice that they are not. So the state's utility regulator is now litigating against the state's top lawyer to keep the public from learning which counties the public's data centers are in.

That is the week in one sentence. Every big Texas story this week was a fight over information, and who gets to see it. ERCOT's community-impact questionnaire forces every large-load developer to disclose ownership, water, tax abatements and on-site generation by Monday at 5 p.m. Taylor annexed a 664-acre gas-and-data-center campus so that the city, not Williamson County, would be the one asking the questions. The NRC put four AP1000s on the public record for 45 days of comment. And the industry, having noticed that it is losing the argument, stood up a lobbying coalition whose president says the job is to "make sure the economic story gets told." Everyone wants the story told. They just disagree about which parts.

The PUC Sues the Attorney General Over Two Columns

Some background, because the survey itself is the quiet part. The Legislature did not pass a data-center water bill. It attached a budget rider to the 2026–27 General Appropriations Act, Article VIII-57, directing the PUC to survey large electric and water users and report to the Governor and the Legislative Budget Board by the end of this year. The commission sent its Energy and Water Use Survey to 377 facilities. By a June House hearing, 28 companies covering 92 facilities had answered, which one state representative called "pathetic." After the House Natural Resources Committee had the survey reopened in July, the count stood at 77 data centers and 13 crypto mines as of August. Ninety out of 377, on a survey the Legislature ordered.

Then a McLennan County resident and four journalists filed Public Information Act requests for the responses. The PUC asked the AG for permission to withhold the location fields under the Texas Homeland Security Act. The AG's office said no, finding the commission had not shown the data "identifies the technical details of particular vulnerabilities of critical infrastructure to an act of terrorism." The PUC's petition argues the opposite: that county plus water planning area would give "a person intending an act of terrorism or a hostile act by a foreign adversary of the United States" the ability to "select specific, high-load facilities and identify the regional transmission and distribution infrastructure and water systems on which each depends." The commission is not trying to seal the whole survey, only those two fields.

Here is the problem with the argument. The county where a data center sits is not a secret. It is in the TDLR filing, the county appraisal roll, the Chapter 403 abatement application, the ERCOT large-load queue by county, and usually a press release with a rendering. A water planning area is a map on the TWDB website. The PUC is asking a district judge to find that a combination of two public facts becomes a state secret when a regulator writes them in the same row. If that holds, it holds for everything the Legislature asked the commission to report. The survey was ordered so the state could learn how much water and power this build-out needs and where. A report that cannot say where is a report that cannot answer the question it was commissioned to answer.

And the timing is its own commentary. This is the same commission that adopted §25.194 with a $50,000-per-megawatt interconnection fee, and the same commission ERCOT reports to on the Governor's large-load audit. Monday at 5 p.m., ERCOT's Data Center Community-Impact RFI comes due, and every 25 MW-plus project has to disclose, under notarized attestation, its ownership, its water source, its tax abatements and its on-site generation. The state is collecting more location data about data centers than it has ever had. It is also in court arguing that it cannot let you see the county. Classic.

"We Can't Drink Data": Taylor Annexes 664 Acres and a Power Plant

Thursday night the Taylor City Council voted 5-0 to approve a development agreement with Big Watt Digital of South Dakota and PowerHouse Data Centers of Virginia, voluntarily annexing 664 acres between FM 112 and US 79, just east of the city limits in unincorporated Williamson County. The project, known as Project Mustang until the agreement renamed it the Taylor Technology Campus, is a 500 MW data center with an option for another 500 MW, powered by an on-site gas-fired plant that can sell its surplus to the grid. Austin Free Press has reported the generator at 477 MW; Community Impact earlier reported a larger reciprocating-engine fleet. The agreement text does not pin a number, so treat the generation figure as roughly half a gigawatt and read the fine print when it is filed with TCEQ.

The route here is the interesting part. Developers withdrew their zoning and annexation application on September 3 after the Planning and Zoning Commission tabled it for 90 days in August. Instead of leaving, they negotiated directly with the city, which published a development agreement on October 2 and voted six days later. The agreement is, by Texas data-center standards, unusually specific: closed-loop cooling on reclaimed water with a one-time fill of 1.575 million gallons for the entire site and potable water only for restrooms; a noise cap of 65 dBA at the property line against the 85 dBA the state allows; 300-foot setbacks on three sides and 700 feet on the south, where the neighbors are; a 400-foot landscaped buffer with six-foot berms; dark-sky lighting; and a withdrawn TCEQ wastewater discharge permit. The developers put up $28.2 million in community commitments, including $10.2 million for Taylor ISD, $13 million to the city and $1.5 million in scholarships, and asked for no tax abatement. The city projects $1.38 billion in gross tax revenue over 20 years.

None of which satisfied the room. An overflow crowd carried "We can't drink data" signs, a 1,400-signature petition for a moratorium was rejected on the grounds that state law does not allow it, and a writ of mandamus on that question is pending at the Third Court of Appeals. One resident, Scott Gibbs, asked the council why "these projects are galloping full speed ahead here in Taylor, when other cities, counties, and politicians from all parties are saying, 'Whoa, let's slow this horse down.'" The council's answer, in effect, was that the horse was leaving either way, and annexation is the only way a city gets to write the rules. In unincorporated Williamson County, the setbacks, the noise cap and the reclaimed-water requirement would have been suggestions. Inside the city limits they are a contract.

Two things to watch. First, the city spokesperson's line that the project "will generate its own power and will not need the same approvals" under the Governor's audit is true for ERCOT and not obviously true for TCEQ. The Governor's September 21 directive told TCEQ to halt all permits sought by data centers until the audit completes, and Bracewell's read is that it catches behind-the-meter gas regardless of grid interconnection. A half-gigawatt gas plant needs an air permit. If that permit is not already in hand, the project is paused by the same state that Taylor just agreed to out-regulate. Second, this is the fourth data center around Taylor and the twelfth in Williamson County. The county that landed Samsung is now the county where the resistance is best organized. That is not a coincidence, and the industry noticed.

The NRC Says "Issue the License." Preliminarily. Pending Comment.

This morning's Federal Register carries the NRC's draft environmental impact statement for Fermi America's combined license application for Project Matador Nuclear Units 1 through 4, four Westinghouse AP1000s in Carson County next to the Pantex plant. The staff's preliminary recommendation is that the NRC "issue the requested COL to Fermi America contingent upon successful completion of the safety review and unless safety issues mandate otherwise." Comments are open for 45 days, through November 23, on Docket NRC-2026-0100.

The schedule is the story. Fermi filed its COL application on June 17, 2025. The scoping notice went out March 20, 2026. The draft EIS landed October 9. That is under seven months from scoping to draft, which is not how the NRC has historically done large light-water reactors, and the reason is that this is the first use of the agency's pilot letting an applicant prepare its own draft EIS under NRC supervision. Fermi was the first private company admitted to that pilot. The environmental review is the part of the COL process that used to take years. If this holds, it will be the template every reactor developer with a Texas site uses, and I flagged last week that Blue Energy has already asked ERCOT for the first reactor slot at Victoria. Fermi is coming at the same problem from the federal side: get the license, not the queue position.

Now the other column. Four AP1000s is roughly 4,400 MW of nuclear, and Fermi's campus pitch has grown from 11 GW of permitted generation to a stated 17 GW as of its September 28 release naming NAES to operate a gas-turbine fleet of which 2.2 GW has actually been secured. The first announced tenant terminated its $150 million agreement last December. The second, TensorWave, signed a 222 MW, 15-year lease valued at about $6.5 billion in August, and the closing has been extended to October 31 pending an investment-grade guaranty. The NRC can say "issue the license" all it likes. A reactor with no customer is a very expensive draft EIS. Watch the 31st.

The Industry Hires a Storyteller

The Lone Star Infrastructure Coalition launched October 1 out of Houston, with former PUCT commissioner and DOE official Jimmy Glotfelty as president. The member wall is a who's who of the people who get paid when a large load interconnects: QTS, NextEra Energy Resources, Siemens Energy, Quanta Services, the Nuclear Energy Institute, Lancium, Grid United, Amperon, and the three transmission and distribution utilities whose territories hold most of the queue, Oncor, CenterPoint and AEP Texas. Glotfelty told Bloomberg the plan is a field campaign aimed at mayors and county judges: "We want to make sure the economic story gets told."

The economic story has been told. The problem is the polling. A Texas Public Policy Foundation survey of 1,167 likely voters in late August found 54 percent support a local ban on data centers, against 37 percent opposed. That is not a fringe. That is the median Texas voter, in the state that has 474.7 GW of large-load requests in ERCOT's queue, 90 percent of them data centers. The coalition exists because Taylor happened, and Taylor is not an outlier. The Governor paused the permits. The PUC adopted a $50,000-per-megawatt fee. The Legislature's rider asked for water data the industry mostly declined to provide. The field campaign is going to be walking into rooms where the first question is the one Taylor asked, and "jobs" is not an answer to "where does the water come from."

One structural note. The utilities in this coalition are the same ones currently defending 765 kV Permian transmission routes against landowner opposition. A coalition that puts Oncor's name next to QTS's on a mailer to county judges is making the argument that the transmission build-out and the data-center build-out are the same project. They are, and that is exactly what the opposition has been saying.

Also Filed: Two Buildings in Kent County, a Battery in Upton County, and Loan No. 9

Two TDLR registrations dated October 1 describe "Project Hyper – Spur Building 1" and Building 2 on County Road 233 outside Jayton, Kent County: two buildings of 759,262 square feet each at $2.4 billion apiece, construction starting January 13 and January 31, 2027, completion May 25 and June 7, 2029. The filer is Spur DC Owner 1 and 2 LLC; DataCenterDynamics attributes the project to Crusoe, whose three 806,360-square-foot Childress buildings carry the same Project Hyper name and the same $2.4 billion ticket. If that is right, Crusoe's Rolling Plains footprint is now five buildings and about $12 billion across two counties with a combined population under 8,000. No megawatts in the filing. At Childress the comparable is 1.4 GW for three buildings, so the arithmetic is left to the reader.

Linea Energy closed financing on October 1 for Mesa View, a 250 MW / 500 MWh standalone battery in Upton County: a construction-to-term loan, tax-equity bridge and letter-of-credit facility with NORD/LB as coordinating lead arranger and Texas Capital in the syndicate, plus preferred equity from DESRI. COD 2027. Amount undisclosed, which is how you know it closed on terms the lender liked. For scale, ERCOT's own October fact sheet puts installed storage at 21,537 MW. Cleanview counts 18,075 MW actually operating as of this month, so take the ERCOT figure as nameplate on the books rather than batteries discharging tonight.

And an update on last week's Texas Energy Fund item: the Governor's office formally announced Loan No. 9 on Tuesday. Pecos Power Plant LLC, 452 MW in Reeves County, co-sponsored by Mercuria and Continental Resources, COD 2027. Nine in-ERCOT loans now total 5,446 MW. The loan amount still has not been published. Continental's 10-Q shows $164 million contributed against a commitment of up to $257.8 million for its half of the joint venture, which gives you a floor on what the plant costs and nothing on what the state lent. We will keep asking.

What to Watch Next Week

Monday, October 12, 5 p.m. ERCOT's Community-Impact RFI closes. Every project over 25 MW files ownership, water, abatement and on-site generation data with a notarized attestation. ERCOT's report to the PUCT is due on or before December 10. Whether any of it becomes public before the PUC's lawsuit is decided is now a live question.

Around October 14. The Texas Water Development Board's first 30-day enforcement update to the Governor on the water survey, per the September 21 directive. If the PUC's 90-of-377 response rate is the baseline, watch whether the Governor's office treats non-response as a permitting problem.

Thursday, October 15, 9:30 a.m. PUCT open meeting. The agenda is posted. I am listening for any mention of the records suit, §25.194 implementation, and whether the commission says anything about the survey report it is due to deliver by year-end.

Monday, October 19. TCEQ's compliance report to the Governor on the data-center permit halt. This is where we learn whether behind-the-meter gas, including Taylor's, is actually caught.

October 31. Fermi's extended closing deadline with TensorWave on the 222 MW lease. A second extension would say more about Project Matador than the draft EIS does.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice, and Andi is not your broker. Links go to primary sources wherever possible; form your own view.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to The Grid Report

"Pay Their Own Way": Korea Funds 6.5 GW of Gas, Texas Lends for 452 MW, and the Audit Hits Monday

On September 21, Governor Abbott's letter to the Texas Commission on Environmental Quality put the state's position on data centers in one sentence: "Data centers must pay their own way, protect our grid and water, and complete the ERCOT and TWDB audits." Eighteen days later, this week's deals read like a set of answers to that sentence, given by people who would rather not wait for the audit.

A South Korean ministry is paying for 6.5 GW of gas in La Salle County. The state's own loan program just financed another 452 MW in Reeves County. A nuclear startup asked ERCOT for a place in line. And on Monday, every developer of 25 MW or more has to sign a notarized form saying what it is actually building.

Project Star: $22.3 Billion, 6,472 MW, and a Bill Sent from Seoul

On September 30, the Commerce Department and the Korean government announced Project Star, a $22.3 billion, 6,472 MW gas campus in Encinal, Texas. Related Companies and NextEra Energy Resources are developing it, with Lewis Energy Group supplying the site, gas and water. The power serves an adjacent, privately funded 5 GW data center campus from Related Digital, and surplus goes to the ERCOT grid. First generation is targeted for as early as 2029. Korea Times reports full capacity in 2032.

The money is the part to read twice. Korea's finance minister told a parliamentary audit that Seoul has already sent $2.4 billion to Washington for the project, about 10 percent of the cost. Korea Times describes it as the first project picked under the strategic investment arrangement. So the largest "bring your own power" project in Texas is being financed by a foreign government, built by Related and NextEra, to serve a tenant the announcement does not name. It also has no ERCOT interconnection details that I could find, so the "excess to the grid" line is a plan, not a filing.

The release arrived nine days after Abbott told every state agency to hold data center approvals. The project is a gas plant, which makes it the cleanest possible response to "pay their own way": the developer's own generation, on the developer's own gas, with someone else's balance sheet underneath.

Texas Energy Fund Loan No. 9: 452 MW Near Pecos

On October 7, Abbott announced the ninth finalized loan under the In-ERCOT Generation Loan Program: a 452 MW gas plant in Reeves County, borrowed by Pecos Power Plant LLC with Mercuria and Continental Resources as sponsors. Target start is 2027. The eight earlier loans total 4,994 MW, so the program is now at 5,446 MW of financed capacity.

The release does not say how many dollars the loan is for, so I am not going to guess. PUC Chairman Thomas Gleeson called it "a dependable source of power for Texas families and businesses," with "quick start capabilities to meet fluctuating demand." Note what the release does not say: that any of this serves a data center. The state is lending to build gas for the grid at the same moment it is telling data centers to bring their own. Both can be true, but only one of them has a published loan amount, and it is not this one.

Blue Energy Asks ERCOT for the First Reactor Slot (an Update)

In an earlier issue I covered Blue Energy's half-finished construction permit at the Port of Victoria. The new development: Bloomberg reported on October 6 that the company has filed what is described as the first small modular reactor interconnection request at ERCOT. It covers up to five 300 MW GE Vernova Hitachi BWRX-300 units, 1.5 GW of nuclear, paired with about 1 GW of gas, to serve a Crusoe campus. Per Big Energy News, the gas units are targeted for 2030 and 2031 and the first reactor for 2033, with a final investment decision expected in 2027.

Read the sequence. The gas arrives first and carries the load. The reactors are a 2033 option that holds a spot in the queue today. That is a fine strategy, and also the reason an interconnection request is not a power plant. I could not confirm the filing date or which county the site sits in from a primary source, so I am leaving both out.

Monday, 5 p.m.: The Audit Gets Its First Real Number

ERCOT's data center questionnaire is due at 5 p.m. Central on October 12. It covers developers of 25 MW or more in the interconnection process, requires a notarized attestation, and non-respondents are reported to the PUC and the governor's office. ERCOT and the PUC are targeting a report on or before December 10. Separately, TCEQ owes the governor a compliance update on the permit halt by October 19.

This is the first moment the state gets to count what is real. A queue that other outlets put near 474 GW, about 90 percent of it data centers, is about to meet a form with a notary stamp. My guess, and it is only a guess, is that the number of megawatts that survive the attestation is a small fraction of the number that entered. Project Star and Pecos both look like the survivors: named developers, named fuel, a financing path.

A Clarification on the Large-Load Rule

Last month I wrote about the PUC's new large-load interconnection rule and described it by the $50,000 per megawatt of security. That figure holds, but I left out half the fee structure. The rule, issued September 18 for loads of 75 MW and up, also sets a flat $100,000 study fee regardless of size, and the final version dropped the non-refundable fees in the March draft. The $50,000 per megawatt is financial security, not a fee, and roughly 80 percent is forfeited if a customer scales back or walks away. Small distinction, large difference to a developer deciding whether to bluff.

What to Watch Next Week

Monday, October 12, 5 p.m. Central. ERCOT's data center questionnaire deadline. Watch for any extension notice, and for how ERCOT describes non-respondents.

Thursday, October 15, 9:30 a.m. PUC open meeting in Austin. I have not been able to read the agenda, so check it for large-load and data center items before assuming anything.

Monday, October 19. TCEQ's compliance update to the governor on the permit halt, just past the window but the next hard date on the calendar.

December 7 and December 10. The PUC's expected decision on El Paso Electric's 366 MW plant for Meta, and the targeted ERCOT and PUC audit report. Both still stand.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice, and Andi is not your broker. Links go to primary sources wherever possible; form your own view.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to Edge Cases

The Tenant Is the Equity Now: $2.2M a Megawatt-Year in Spartanburg County, a $42.9M GPU Divorce in Columbus, $112 a Foot in Eagan

Four deals between 5 and 50 MW got done this week, in four states, and in every one of them the person who owns the building is no longer the person who owns the chips. A neocloud is prepaying a South Carolina landlord's construction budget. A Georgia landlord sold its GPUs to its own customer and kept the shell. A Minneapolis operator converted a 2014 lease into fee simple at a price its landlord's appraiser would not have signed. And a Nasdaq microcap is putting inference racks on cell towers under a structure built so equipment debt can never touch the dirt. The silicon and the real estate are splitting onto different balance sheets, and the tenant is becoming the equity.

The comps that fell out: $2.2 million per critical-IT megawatt per year for 12-year colo in Spartanburg County; $1.82 million to $2.22 million per megawatt-year for five-year hosting in Columbus, Georgia; $1.96 million per megawatt and $112 a foot for a 57 W/sf carrier hotel in Eagan; and, from the one oversized deal I let in as a benchmark, $780,000 per megawatt-year for triple-net powered shell in West Texas. Hold those four numbers next to each other. The spread between the first and the last is the price of the fit-out and the operations layer, and it is what everyone below is actually selling.

Nebius Prepays the Build: 50 MW at $2.2 Million a Megawatt-Year, and the Landlord's Equity Is the Tenant's Deposit

AIB Data Centers, the NYSE American listing formerly known as BlockchAIn Digital Infrastructure, disclosed on September 30 that a subsidiary signed a Master Colocation Services Agreement with Nebius for 50 MW of critical IT at CLT-01, its campus in Moore, South Carolina, in unincorporated Spartanburg County about eight miles southwest of downtown Spartanburg and roughly 75 miles from the Charlotte it is named after. The term is 12 years from delivery of the first hall, with two five-year renewals at Nebius's election. Delivery is two 25 MW halls, the first about ten months after utility service begins and the second about fourteen; the 15-year, 65 MW Electric Service Agreement that feeds the site was scheduled to start October 1, which puts the halls at roughly August and December 2027. AIB is careful to say the 50 and the 65 are not additive. The site is a 40 MW bitcoin-hosting shed that was de-energized June 5 for conversion, and the power comes off existing onsite 34.5 kV with no significant upgrades.

The number that matters is in the investor deck AIB furnished with the 8-K. The company puts the initial-term contract value at $1.32 billion and does the arithmetic for you: $1.32 billion over 12 years over 50 MW is $2.2 million per critical-IT megawatt per year. AIB then publishes the peer band it wants to be graded against, with WhiteFiber and Nscale at $2.16 million, Host Digital at $1.94 million, and Applied Digital and CoreWeave at $1.87 million. Nobody in this market volunteers a comp table unless they are at the top of it, and now every landlord under 100 MW will be quoted that table back by the next neocloud that walks in.

The capital stack is the other half of the story. AIB's illustrative budget is about $800 million, or $16 million per megawatt: $560 million of construction debt, $140 million of preferred, and $100 million of common equity that the deck says is funded with Nebius's prepayments, which sit in escrow and release against construction milestones and SLAs, backed by a Nebius Group parent guaranty. In other words, the landlord's common equity is the tenant's deposit. As of the filing date none of the debt or preferred had been arranged and full construction design had just gone in for permits, so this is a signed lease and a financing plan, not a financed project. The escalator is not in the filing; secondary press has floated 3 percent or CPI, and I am not printing that until a document does.

Deal specs. Sponsor: AIB Data Centers (landlord); Nebius Inc. (tenant), Nebius Group N.V. parent guaranty · Site: CLT-01, Moore, SC, unincorporated Spartanburg County, ~8 mi SW of downtown Spartanburg, ~75 mi SW of Charlotte · Footprint: n/d (converted 40 MW bitcoin-hosting shell) · Load: 50 MW critical IT contracted on a 65 MW, 15-yr ESA (density n/d, no sf disclosed) · Lease: Master Colocation Services Agreement, 12-yr initial from first-hall delivery, two 5-yr renewals, escalator n/d; ~$2.2M/MW-yr implied; prepayments in escrow with parent guaranty; Nasdaq-listed neocloud credit · Deal value: ~$1.32B initial term; ~$800M illustrative build (~$16M/MW) · Source: AIB 8-K investor deck, DCD.

Duos Sells the Servers for $42.9 Million and Keeps the Building

Duos Technologies closed on September 30 the sale of 100 percent of Duos Edge AI GPUaaS, LLC to Axe Compute, the Nasdaq-listed neocloud that was already its largest customer. The SPV held 288 Supermicro B300 servers, 2,304 GPUs, racked at Duos's Columbus, Georgia campus. The consideration is two pieces: Axe repaid the SPV's roughly $87.8 million of asset-backed debt at closing, and Axe owes Duos $715,000 a month for 60 months, $42.9 million in total, with the balance accelerating at the earlier of 12 months or any financing Axe raises against the cluster. The roughly $98.1 million GPU equipment facility and its covenants leave Duos's balance sheet with it.

What Duos keeps is the real estate and the power. It still owns and operates the Columbus facility, now leases GPU capacity back from Axe under a capacity-supply arrangement, and the end-customer agreement with an undisclosed investment-grade hyperscaler was extended from three years to five, running through 2031 with renewals. Axe put its side of the arrangement at about $364.6 million of revenue over the term, with Duos covering colocation and energy for the full five years. Duos says it will now put capital exclusively into 10 to 30 MW modular colocation sites, and it has two of its own rates to underwrite them against: the July 10 MW, $111 million, five-year hyperscaler agreement works out to about $2.22 million per megawatt-year, and the August 55 MW, $500 million-plus, five-year order from Axe to about $1.82 million.

The building is worth a look because it is the kind of asset this newsletter exists for. 8 Corporate Ridge Parkway is a 104,778 sf former TSYS call center on 13.66 acres in Corporate Ridge Industrial Park, inside Columbus's consolidated city-county limits about six miles northeast of downtown, per the county record. Ten MW of critical IT has been in revenue since August; Duos says it reaches 20 MW by the end of Q4. Twenty megawatts across 104,778 sf is about 191 W/sf on a whole-building basis, which for a call-center conversion is respectable and for a B300 cluster is a reminder that the data hall is a fraction of the footprint.

Deal specs. Sponsor: Duos Technologies (landlord, seller of GPU SPV); Axe Compute (buyer, Nasdaq neocloud); undisclosed investment-grade hyperscaler end customer · Site: 8 Corporate Ridge Pkwy, Columbus, GA, within consolidated city-county limits, ~6 mi NE of downtown Columbus · Footprint: 104.8 ksf single-story on 13.66 acres · Load: 10 MW critical IT operating, 20 MW by Q4 2026 (~191 W/sf whole-building at 20 MW; ~95 W/sf at 10 MW) · Lease: GPU SPV equity sale, ~$87.8M debt repaid plus $715K/mo × 60; landlord retains facility; end-customer term extended to 5 yrs through 2031 with renewals; on-site colo comps $2.22M/MW-yr (10 MW, 5-yr) and $1.82M/MW-yr (55 MW Axe order) · Deal value: ~$130.7M total consideration to the SPV ($42.9M deferred to Duos) · Source: Duos release, 8-K.

$9.81 Million for 5 MW and 21 Carriers: DataBank Exercises a 2014 Option at $112 a Foot

Mapletree Industrial Trust agreed to sell 3255 Neil Armstrong Boulevard in Eagan, Minnesota to DataBank Properties, LLC for $9.81 million in cash, closing in Q4. DataBank has been in the building since 2014, opened it as MSP2 in 2015 with 5 MW, and runs it as the Twin Cities' second carrier hotel with 21 carriers on the meet-me floor; it is one of four DataBank sites in the metro. The price was not negotiated. DataBank gave notice under a purchase option in a lease dated March 18, 2014, and the number came out of the pricing mechanism written into that lease, three years before the lease would have expired in September 2029.

Mapletree's SGX announcement is the useful document. The building is a single-story 87,402 sf box completed in 1998 on 343,253 sf of freehold land, call it 7.9 acres. Mapletree paid $9.0 million for it in July 2021 as part of a 29-asset US portfolio from Sila Realty, which had paid $5.8 million in 2015. Cushman and Wakefield valued it at $10.9 million as of March 31 on an income-capitalization basis. So the option price is a 9 percent premium to Mapletree's basis and a 10 percent discount to the appraisal, and DataBank just bought back its own building for $1.96 million per megawatt and $112 a foot. Five megawatts over 87,402 sf is 57 W/sf, which is what 2015 looked like. Set that next to AIB's $2.2 million per megawatt per year in rent and the gap between legacy interconnection real estate and new AI colo is roughly one year of the latter's rent buying the former outright.

The lesson for anyone holding a 2010s colo lease with an option in it: the option is now the most valuable clause in the document, and the landlord's appraiser knows it.

Deal specs. Sponsor: DataBank Properties, LLC (buyer, owner-occupier; DigitalBridge/Swiss Life-backed); Mapletree Industrial Trust (seller) · Site: 3255 Neil Armstrong Blvd, Eagan, MN, within Eagan city limits, ~12 mi S of downtown Minneapolis, ~8 mi SE of MSP · Footprint: 87.4 ksf single-story (1998) on 343,253 sf (~7.9 acres) freehold · Load: 5 MW (~57 W/sf) · Lease: Acquisition via lease purchase option (lease dated March 18, 2014, expiry Sept 2029); $9.81M cash, 3% deposit, close Q4 2026; $1.96M/MW, $112/sf; 9% above seller's 2021 basis, 10% below $10.9M C&W appraisal · Deal value: $9.81M · Source: MIT SGX announcement, DataBank.

An 11 MW Inference JV Buys Six Buildings on Five Acres in High Point, Then Bolts GPUs Onto SBA and Tillman Towers

Forum Markets, a Nasdaq microcap with about 13.2 million shares outstanding, announced October 5 the formation of Forum Edge AI LLC, a 51/49 joint venture with Dallas-based Edge Node, to own inference compute at sites that already have power and permits. The initial portfolio is three pieces. One, a signed purchase-and-sale agreement for a six-building, five-acre campus inside High Point, North Carolina, with 9 MW of live utility power, wholly owned by the JV, with about 6 MW of GPUs to energize in Q1 2027 and more as cooling upgrades land. Two, Edge Node's existing Dallas facility, which got its certificate of occupancy for data-center use July 1, running about 2 MW today and stepping to about 4 MW at the meter by early 2027; there the JV owns the transformer capacity and the equipment and Edge Node keeps the real estate. Three, an initial 1 to 2 MW deployment on a Texas tower site under separate agreements with SBA Communications and Tillman Infrastructure, JV-owned equipment paying a monthly fee to the tower owner, sized to fit the existing ground lease so no new zoning or power is required.

The structure is more interesting than the megawatts. Every site sits in its own SPV with no cross-collateralization, and wherever there is real property the land and the compute are held in separate entities so equipment debt never encumbers the dirt. Compute capex is funded by customer deposits plus matched-term equipment financing, with no equity issued for the initial deployment. Forum and Edge Node swap 9.95 percent stakes, about 1.46 million Forum shares, contingent on power and financing milestones. The offtakers are described as large, high-credit-quality counterparties on multi-year terms covering all initial capacity, and none are named; DCD notes Edge Node was founded in 2025 and has yet to launch a service. Forum is guiding $125 million to $175 million of consolidated 2027 revenue off roughly 11 energized megawatts. That is a flag, not a comp; I would not underwrite a tower node off it. But it is the first disclosed inference deal with two named tower owners on the other side of the ground lease, and the land-and-equipment split is the template lenders have been asking small operators for.

Deal specs. Sponsor: Forum Markets (51%, manager); Edge Node AI (49%, operator); offtakers undisclosed; tower landlords SBA Communications and Tillman Infrastructure · Site: High Point, NC (within city limits, parcel n/d); Dallas, TX (address n/d); one Texas tower site · Footprint: High Point 6 buildings on 5 acres, sf n/d; Dallas n/d · Load: ~11 MW energized across sites: 9 MW live utility at High Point (6 MW GPUs phase 1), 4 MW at the meter in Dallas (2 MW JV), 1–2 MW tower node (density n/d) · Lease: Fee acquisition under PSA (price n/d) at High Point; equipment-only JV interest in Dallas; tower equipment license with monthly fee; per-site SPVs, land and compute in separate entities; capex from customer deposits plus matched-term equipment debt; offtake multi-year, counterparties n/d · Deal value: n/d (2027 revenue guidance $125–175M) · Source: Forum Markets release, DCD.

The Benchmark: $780,000 a Megawatt-Year for Powered Shell, Triple-Net, in Ward County

This one is 234 MW and in Texas, which is two strikes against it in this newsletter. It makes the issue because it is the only disclosed triple-net powered-shell rent on an AI conversion this year, and every smaller shell deal is going to be priced off it. Nscale said October 1 that its Ward County site, which it describes as an empty steel shell nine months earlier, is live and delivering GPUs. The landlord is Ionic Digital, and Ionic's prospectus and September 10-Q lay out the lease: 126 months, triple-net, about 50 acres and 234 MW of energy capacity, rent commencing August 1, 2026 and ramping over 18 months to a fixed $182.5 million a year, 3 percent annual increases starting after year five, one ten-year renewal, a right of first refusal on additional power, and an obligation on Nscale to lease a further 89 MW at the same rate, which would take the run-rate to $250.5 million. Contracted revenue is about $1.9 billion, or $2.6 billion with the 89 MW. Nscale calls the site roughly 200 MW of IT and closed up to $1.85 billion of delayed-draw term loans against it August 31; Microsoft holds an option through Nscale on additional power from the second half of 2027.

$182.5 million over 234 MW is $780,000 per megawatt per year, or about $65 per kilowatt per month, for land, existing buildings, and the interconnect, with the tenant doing the fit-out. Turnkey colo this week printed at $1.82 million to $2.2 million. The difference, call it $1.0 million to $1.4 million per megawatt-year, is what the shell, the chillers, the switchgear, and the people who run them are worth to a neocloud in a hurry. That is the margin Duos is reorganizing its whole company to capture at 10 to 30 MW, and it is what AIB is charging Nebius for in Spartanburg County.

Deal specs. Sponsor: Ionic Digital (landlord); Nscale (tenant, private neocloud, Microsoft option behind it) · Site: Ward County, TX, parcel n/d · Footprint: ~50 acres, existing buildings, sf n/d · Load: 234 MW energy capacity per landlord, ~200 MW IT per tenant (density n/d) · Lease: 126-month NNN powered shell, $182.5M/yr fixed at 234 MW after 18-month ramp (~$780K/MW-yr, ~$65/kW-mo), 3% annual after yr 5, one 10-yr renewal, ROFR on added power, 89 MW expansion obligation at same rate · Deal value: ~$1.9B contracted, ~$2.6B with expansion · Source: Colocation Scout summary of Ionic 424B4 and 10-Q.

What to Watch Next Week

October 7, 5:00 p.m. ET: Applied Digital fiscal Q1 call. First real read on Polaris Forge 1 after the 75 MW Ellendale ready-for-service add, and the place to listen for any dollars-per-megawatt on the Delta Forge leases. Applied Digital is on AIB's comp table at $1.87 million; whether that number moves is the question.

October 12: Cheyenne City Council final vote on Orchard Hills. A 162-acre annexation and ag-to-light-industrial rezoning for Trammell Crow next to Meta's campus, over a unanimous Planning Commission denial. If it passes, it is a comp for how much a council will overrule its own staff for a hyperscaler-adjacent parcel.

October 21: Suffolk, Virginia City Council votes on a Planning Commission 8-0 recommendation to prohibit data centers as a primary use in every zoning district, closing the warehouse loophole. Hampton Roads has been one of the few Virginia secondary markets still entitling.

October 27: Glendale, Arizona decides Project Eagle, a 160-acre annexation for three data centers and a gas plant near Luke Air Force Base. Same day, Sioux County, Iowa holds third reading of its data center standards and Hagerstown, Maryland hears the Martin Farm annexation.

October 31: Fermi and TensorWave's extended closing date on the 222 MW Project Matador lease, with an investment-grade guaranty still being negotiated. A second extension would say something about what guarantors are charging this quarter.

Rolling: AIB CLT-01. Confirmation that ESA service began October 1, permit issuance, and whether the $560 million of construction debt and $140 million of preferred actually get arranged. The lease is signed. The project is not yet financed.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to The Grid Report

Who Pays for Meta's 366 MW of Gas? Judges Say Not El Paso Ratepayers

On September 23, two administrative law judges at the Public Utility Commission told El Paso Electric that its proposed 366 MW gas plant for Meta can be built, but only if the people who live in El Paso do not pay for it. That is a ruling about one plant in one city. It is also the cleanest statement yet of the question every Texas data center deal now has to answer: when the power is built for one customer, who holds the bill?

This week's other deals each answer it differently. Crusoe plugged a Google campus straight into a wind farm and let the grid take the leftovers. Cipher Digital doubled the life of a lease and put a number on how it shares overruns. And two developers pitched gas that never touches ERCOT at all, which is the cheapest way to avoid the question.

The Judges Found No RFP, No Alternatives, and a Five-Year Bridge

El Paso Electric wants a Certificate of Convenience and Necessity for the McCloud Generation Facility, 366 MW of gas built from 813 modular generators of 450 kW each, supplied by Enchanted Rock at Meta's recommendation. The load is Meta's roughly 1 GW data center in El Paso. The judges found that the utility "failed to adequately consider alternatives to the gas plant" and "failed to issue a request for proposals to contractors." Fair summary: the utility picked the plant the customer suggested and then asked the state to certify the choice.

The condition is the headline. Per KVIA's reporting on the proposal for decision, the facility "may be approved only with protections intended to prevent EPE customers, other than Meta's data center, from paying the plant's construction and operating costs." Without those protections, the judges would recommend denial. The cost is itself a moving target. Inside Climate News puts it near $499 million, the city of El Paso has used $551.8 million, and I could not confirm which figure is current. Plan on roughly half a billion dollars either way.

Meta covers the costs for the first five years. The judges' concern is the sixth, when the bridge ends and the question of who pays becomes a ratepayer question. On September 28 the El Paso City Council authorized the city attorney and city manager to keep negotiating what it calls a "full hold harmless." The Commission's decision is expected by December 7. No open meeting date is set, and I could not confirm the docket number, so treat both as open. A five-year bridge on a plant with a multi-decade life is the kind of arrangement that sounds protective until you read the sixth year.

Crusoe Names Google, and the Power Plant Is a Wind Farm

Crusoe confirmed on September 28 that Google is the customer for its Armstrong County campus, per DataCenterDynamics. The site at 10001 Lima Road is planned as at least six single-story buildings: four of 805,380 square feet and two of 484,955. Crusoe's release says ground broke in June 2025 and more than 5,500 workers are on site daily.

The power structure is the interesting part. The campus connects directly to Serena's Goodnight 1 wind farm, 265.5 MW and operating, and Goodnight 2, another 265.5 MW under construction. That is 531 MW of generation sitting behind the fence, with surplus injected into the grid when the wind outruns the campus. It inverts the McCloud problem. Nobody is asking El Paso-style ratepayers to underwrite a plant, because the plant is a wind farm that already exists. The cost is variability, and Google gets to find out what a hyperscale load looks like on a Panhandle wind profile. The $29 billion investment figure floating around comes from Aterio Research as cited by DataCenterDynamics, not from Crusoe, so read it as an estimate.

Cipher Doubles Barber Lake to 20 Years and Writes the Overrun Rule Into the Lease

On September 25 Cipher Digital announced it had extended Barber Lake's contracted life from 10 years to 20. The second ten years is a binding commitment from an unnamed "leading AI lab" alongside existing tenant Fluidstack. Contracted revenue goes from $3.8 billion to over $9 billion, with about $5.2 billion of that new.

The less glamorous paragraph is the better one. Cipher bears the first $359.3 million of costs above the initial budget. Above that, the tenant reimburses 50 percent, structured as additional rent over the 20 years with a contracted rate of return. That is a cost-overrun clause in a press release, which is rare, and it answers the McCloud question in private-contract form: the party that wants the capacity shares the risk of building it. Delivery runs from the fourth quarter of 2026 into the first quarter of 2027, with first rent expected in the fourth quarter. The release names no megawatts, which in this market is a choice, not an oversight.

Off-Grid Gas: 450 MW Ordered, and a Brewster County Ranch Pitched

Enerflex announced October 1 that it was awarded about 450 MW of behind-the-meter gas-fired generation for an unnamed North American data center developer. Deliveries start in 2027 and the work completes in 2028. Enerflex plans about $15 million of 2026 spending, with roughly $85 million for energy services facilities, mostly in 2027, and says its opportunity pipeline exceeds 2 GW. CEO Paul Mahoney cited demand for "reliable, prime power that does not require grid connection." The release names no site and no state, so I am not calling this a Texas project. It is a Texas-relevant data point because Texas is where developers are hunting for exactly this equipment.

Closer to home, Pacifico Energy, the developer behind what public radio reporting ties to Amazon's Pecos County data center, has been talking to Brewster County officials about an AI campus with a gas plant on 8,400 acres northeast of Alpine. The company's own estimate runs from $5 billion to $60 billion, a range wide enough to cover a rounding error or a small country. The design is off-grid gas turbines with some solar and batteries, one to two years of planning before construction, and Kiewit among firms potentially in the mix for construction management. About ten residents showed up and none spoke in favor, citing air quality, noise and dark skies.

Put the two next to each other and the pattern from last week holds. The TCEQ air-permit halt means an island-mode campus still has to ask someone for permission. The ones that skip ERCOT have simply picked a different regulator, and that regulator is currently not issuing permits.

What to Watch Next Week

McCloud exceptions and the PUCT calendar. Watch for exceptions to the proposal for decision and whether El Paso Electric and the city land a hold-harmless agreement before the December 7 decision date. I could not confirm an exceptions deadline.

October 6, the SB6 large load curtailment workshop. This is where the question of who gets cut first in a shortage starts getting answered, and it matters more to behind-the-meter campuses than the McCloud docket does.

October 12, ERCOT's community impact RFI. Responses are due from developers of data centers of 25 MW or more. ERCOT has said it will work with the PUCT on a report by December 10. Watch for any extension or any disclosed response count.

October 15, the next PUCT open meeting, and October 19, TCEQ's compliance report. The first is the next chance for commissioners to say something about large-load metering or generation certificates. The second is the first look at how many island-mode projects the air-permit halt actually catches.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice, and Andi is not your broker. Links go to primary sources wherever possible; form your own view.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to Edge Cases

Permits Are the New Power: $2.7M an Acre in Phoenix, $1.75M a Megawatt in Georgia, and 7.875% on a Meta Guarantee

Texas told TCEQ on September 21 to stop issuing permits to data centers, islanded ones included, until ERCOT and the water board finish audits in December. Loudoun voted 7-1 for a twelve-month application pause three days earlier. Prince William killed by-right data center development on the 22nd and turned down Dominion's Vint Hill switching station 8-0 the same night. Against that tape, the deals that still printed this week have exactly one thing in common: the permitting fight was already over before the check cleared. That certainty now has a price, and this week we got to read it.

Five prints, one of them small enough to build in a business park: Skanska books $84 million to build 48 MW in Georgia at 196 W/sf; GI Partners pays $2.7 million an acre for five and a half acres next to an APS substation a mile from downtown Phoenix, and 5C AI pays $201 a foot for a warehouse three miles west of it, both cleared by Prop 207 waivers; Kodiak signs six years of behind-the-meter gas for a West Texas site whose lease is guaranteed by a chip company; CleanSpark closes $2.276 billion of 7.875 percent project notes on a Meta-guaranteed NNN lease that pencils to $157 a kilowatt-month; and Zone Frontier ground-leases 4,077 acres around an Xcel 345 kV substation with rent that starts when the concrete does. Two of those are over 75 MW. They are here because they are the comps everything under 75 MW will now price against.

$84 Million for 48 MW: A $1.75 Million-per-Megawatt GC Comp at 196 Watts a Foot

Skanska signed a contract on September 22 to build a roughly 244,730 sf data center in Georgia for an existing client: five colocation halls plus administrative space, designed for 48 MW. The scope is turnkey, not shell. Civil, structural, utilities, electrical, mechanical, security, interior fit-out and commissioning of the major equipment are all inside the $84 million contract value, which books into Skanska USA's third-quarter orders. Construction starts in November, completion is slated for the third quarter of 2028.

Do the arithmetic and you get the two numbers a 30-to-60 MW developer actually wants. Forty-eight megawatts across 244,730 sf is 196 W/sf gross, which is an air-cooled colo spec, not an inference-density spec, and that tells you what the client is: a multi-tenant operator building for the enterprise book, not a neocloud building for a single GPU tenant. And $84 million divided by 48 MW is $1.75 million per megawatt for the general contractor's scope alone, or $343 a foot. That is not all-in capex; the client is buying switchgear, gensets and chillers separately, and land and interconnection sit outside it. But it is a clean, public, current-quarter mark for what a turnkey five-hall build costs in the Southeast, from a GC that has now signed four Georgia data center contracts for the same or similar client, the prior three reportedly at $75 million, $238 million and $255 million. Skanska did not name the client or the town. A 22-month build on a 48 MW box is not a rush job, which suggests the power date, not the building, is the gating item.

Deal specs. Sponsor: undisclosed existing client (owner); Skanska USA Building (GC) · Site: Georgia, town n/d · Footprint: ~245 ksf, five colo halls plus admin · Load: 48 MW design (~196 W/sf gross, computed) · Lease: n/d; GC construction contract, start Nov 2026, complete Q3 2028 · Deal value: $84M GC scope (~$1.75M/MW, ~$343/sf, computed) · Source: Skanska press release.

$2.7 Million an Acre and $201 a Foot: What Phoenix Infill Trades For Once the Waiver Is Signed

Phoenix adopted a data center zoning ordinance last year, and the market's answer has been Proposition 207, Arizona's 2006 private-property-rights law that lets an owner claim compensation when a new land-use rule reduces the value of a parcel. The city's response, in at least two cases now, has been to waive enforcement rather than pay. Both waivered sites traded this month, and together they give you a two-point price curve for entitled infill in the fifth-largest city in the country.

Point one: on September 17, GI Partners paid $14,720,919 for 5.43 acres at the southeast corner of 7th Avenue and Grant Street, about a mile south of the downtown core and well inside city limits, according to Maricopa County records reported by the Phoenix Business Journal. Seller LKY Development bought it for $3.15 million in 2012, a 4.7x mark over fourteen years, and spent a chunk of those years working with APS to expand the substation the parcel sits next to. That works out to $2.71 million an acre for dirt with a substation on the fence line and a city concession in hand. No tenant, no MW figure and no building were disclosed, which is fine; the buyer is a $49 billion private-equity shop with a Scottsdale office, and the value it paid for is the ability to file a site plan without a fight.

Point two: 5C AI's $22.75 million purchase of a vacant 113,414 sf industrial building at McDowell Road and 27th Avenue, about three miles west-northwest of downtown, closed September 2 and made the rounds of the trade press this week. The Phoenix City Council had voted on July 1 to bind itself not to enforce Ordinance G-7396 against the site after 5C filed its Prop 207 claim, per the same PBJ reporting. Seller Hanson Capital paid $9.5 million in 2021. That is $201 a foot for a warehouse shell, a 2.4x mark in five years, in a submarket where generic industrial does not trade anywhere near that. 5C did not disclose a load figure; its existing PHX01 site is listed in the 18 MW range, and a 113 ksf single-story conversion at conventional densities lands in the same neighborhood. The spread between $201 a foot for a shell and $2.7 million an acre for bare land is the market pricing the difference between a conversion you can start in months and a ground-up build that needs a substation expansion already done. Both, notably, sit inside a city that just passed rules to slow this down. The rules slowed everyone except the two sponsors who had already filed.

Deal specs. Sponsor: GI Partners (buyer), LKY Development (seller) · Site: SE corner 7th Ave and Grant St, within Phoenix city limits, ~1 mi S of downtown · Footprint: 5.43 acres (~237 ksf land); building n/d · Load: n/d; adjacent APS substation expanded for data center load · Lease: fee-simple acquisition; Prop 207 waiver of city data center ordinance in hand · Deal value: $14.72M (~$2.71M/acre, computed; 2012 basis $3.15M) · Source: KTAR / Phoenix Business Journal.

Deal specs. Sponsor: 5C AI (buyer), Hanson Capital Group (seller) · Site: NW corner McDowell Rd and 27th Ave, within Phoenix city limits, ~3 mi WNW of downtown · Footprint: 113.4 ksf existing single-story industrial · Load: n/d · Lease: fee-simple acquisition for conversion; council-approved waiver of Ordinance G-7396 (July 1) · Deal value: $22.75M (~$201/sf, computed; 2021 basis $9.5M) · Source: ABC15 / Phoenix Business Journal.

76 MW, Six Years, Forty Recips, and a Chip Designer on the Lease

Kodiak Gas Services announced on September 21, the same day Governor Abbott's TCEQ order landed, a six-year agreement to supply 76 MW of behind-the-meter baseload power, balance of plant included, to a West Texas data center inside Kodiak's existing Permian compression footprint. The fleet is roughly forty reciprocating natural-gas generation units, about 1.9 MW apiece, deploying from the fourth quarter of this year and scaling into the first quarter of 2027, with revenue starting in that quarter. It is Kodiak's second long-term data center power contract and puts about half of its power fleet under long-term paper, per the company's release.

Seventy-six megawatts sits one megawatt over this newsletter's line, and the reason it is here is the credit stack, which is the best one printed this week at any size. The unnamed operator is contracted to an investment-grade hyperscaler, and the data center lease is guaranteed by a GPU designer. Read that as the chip vendor backstopping the rent so the operator can sign a power contract it could not otherwise carry, and the power provider taking a six-year term, not fifteen, because the equipment is redeployable compression-grade iron and the counterparty is not the operator's balance sheet. Six years is also shorter than any lease term in this issue, which tells you what a gas fleet owner thinks the useful life of a 2026 inference hall is before somebody renegotiates. Whether the site's air permit was already in hand before September 21 is the question the release does not answer, and the one that determines whether this template survives the freeze.

Deal specs. Sponsor: Kodiak Gas Services (power provider); undisclosed operator (payor); IG hyperscaler (tenant); undisclosed GPU designer (lease guarantor) · Site: West Texas, Permian footprint; town n/d · Footprint: n/d · Load: 76 MW generation capacity, ~40 recip units (~1.9 MW each, computed); IT load n/d · Lease: 6-yr behind-the-meter power supply agreement incl. balance of plant; escalator n/d; hyperscaler tenant, GPU-designer guarantee · Deal value: n/d · Source: Kodiak IR.

7.875 Percent and $13 Million a Megawatt: The Project-Debt Price of a Meta Guarantee

This one is 175 MW, more than double the line, and it is here because every take-or-pay under 75 MW that goes to a lender in the next quarter will be marked against it. CleanSpark's financing subsidiary priced $2.276 billion of 7.875 percent senior secured notes due 2031 on September 18 at 98.5, and closed on September 25, first lien on substantially all the assets of the Sandersville, Georgia project entity plus a pledge of the issuer's equity, with a completion guarantee from the parent, per the closing 8-K. Proceeds finish the build, reimburse equity already spent, and fund the debt-service reserve.

The asset underneath is a 20-year, roughly 100 percent NNN lease to Anviran, a Meta entity, with Meta guaranteeing rent and operating expenses, a 3 percent annual escalator, two five-year options, rent commencing November 30, 2027, and construction wrapping March 2028, according to Blockspace's read of the deal book. Development cost is about $11.9 million per megawatt; average NOI is about $330 million a year. Divide the notes by the load and you get $13.0 million of debt per megawatt on $11.9 million of cost, which sounds upside-down until you remember the equity reimbursement and the reserve account are inside the sizing. Divide the NOI by 175,000 kW and twelve months and you get $157 per kilowatt-month of base rent, which lands within four dollars of the $161 a kilowatt-month East Tulsa comp from two issues ago, on a lease four times the size with a guarantor several notches better. Cash interest is about $179 million a year, so NOI covers it roughly 1.84x. That is the market's number for hyperscaler-guaranteed rent in the Southeast, and if you are pitching a 40 MW take-or-pay to a lender at 9 and a half percent, this is the sheet they will have open on the other screen.

Deal specs. Sponsor: CleanSpark (developer/landlord); Anviran (Meta) tenant; Meta guarantor · Site: Sandersville, Washington County, GA; parcel n/d · Footprint: n/d · Load: 175 MW critical IT · Lease: 20-yr ~100% NNN, 3% annual escalator, two 5-yr options, rent commences Nov 30, 2027; investment-grade hyperscaler guarantee · Deal value: $2.276B 7.875% notes due 2031 at 98.5 (~$13.0M/MW debt, computed); ~$11.9M/MW dev cost; ~$157/kW-month base rent (computed from ~$330M NOI) · Source: CleanSpark 8-K (pricing).

Rent Starts When You Pour: A Panhandle Ground Lease Wrapped Around a 345 kV Substation

The last one is a land structure, not a power number, and it is the one a 20 MW developer without a balance sheet should photocopy. On September 29, Zone Frontier signed a ground lease on about 4,077 acres in Potter County, outside Amarillo, on land that surrounds Southwestern Public Service's existing Potter County 345 kV substation in SPP territory, per the company's release. Zone can designate 200 to 800 acres for data center use and at least 1,800 acres for solar and storage. It is pitching 200 MW initially and more than 500 MW eventually, which puts it over the line; it is in the issue for the lease terms, which scale down to any size.

The terms: thirty years, two ten-year extensions, a purchase option on the data center parcel, a co-terminous water supply agreement on the appurtenant water rights, and base rent that begins for each site area only when construction starts on that area. That last clause is the whole trade. Zone is a small-cap with a Minnesota campus, a ten-year Cerebras colocation agreement that does not produce revenue until the first half of next year, and no named tenant in Texas. It has just controlled four thousand acres around a transmission substation, with water, adjacent to two gas pipelines, at a carry cost of roughly zero until it finds a customer. The landowner, undisclosed, gets a purchase-option strike and a rent stream that is real the moment anyone pours a slab. If you are trying to tie up a 60-acre pad next to a 138 kV sub in a county that will still talk to you, this is the term sheet: option the land, make the rent construction-contingent, get the water rights inside the same instrument, and let the utility's substation do the marketing.

Deal specs. Sponsor: Zone Frontier (lessee/developer) with HST Technologies; landowner undisclosed; no tenant yet · Site: Potter County, TX, Amarillo metro; surrounds SPS/Xcel Potter County 345 kV substation (SPP); miles to Amarillo city limits n/d · Footprint: 4,077 acres; 200 to 800 ac data center, 1,800+ ac generation · Load: 200 MW initial, 500+ MW potential; density n/d · Lease: 30-yr ground lease plus two 10-yr extensions; rent commences per area at construction start; purchase option; co-terminous water supply agreement; no tenant credit yet · Deal value: n/d · Source: Zone Frontier press release.

What to Watch Next Week

Buffalo's two-year ban, tonight. The Common Council takes its full vote on a two-year data center and crypto-mining ban; the sponsor expects near-unanimous passage and the mayor's signature is the open question, per WGRZ. Oakland's full council votes on a 45-day moratorium October 6.

The Fermi and TensorWave 222 MW closing, October 31. The parties pushed the Project Matador lease closing from September 30 to October 31 via a first amendment on September 22, per the announcement. A second extension would say more than the first did.

TCEQ's compliance report, October 19. The agency owes the governor a report on the permit halt by then, and ERCOT's audit is expected mid-December, per Bracewell's summary of the order. Every behind-the-meter deal in Texas, Kodiak's included, is on hold for air permits it has not already pulled.

Statesboro's end user. 4AM Development says it is close to signing one of several end users for the 99 MW, 230 ksf Burkhalter Road site, the 430 W/sf building this newsletter flagged in August, while eleven residents petition Superior Court to void the rezoning, per the Statesboro Herald. The city manager will not consider the special-use permit without a named tenant. A name would be a print; a ruling would be a precedent.

Salem Township and Pulaski County, October. Salem Township, Pennsylvania supervisors take up the 4,000-acre overlay for the $1.4 billion Salem 3 campus after a 4-3 planning-commission recommendation on September 24, the third such vote after the prior one was voided under the Sunshine Act. In Arkansas, Pulaski County's high-density digital infrastructure ordinance passed 11-4 on September 22 and the veto-override window runs to October 27.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to The Grid Report

"No Other State Agency Shall Move Forward": TCEQ Halts Data Center Permits, Paxton Names 18 Counties, and the PUCT Sets $50,000 a Megawatt

Last week I said the era of announcing megawatts was over and the era of documenting them had arrived. This week the state added a third era, and it arrived on letterhead. On September 21 Governor Abbott sent a two-page letter to the executive director of the Texas Commission on Environmental Quality directing the agency "to halt all permits sought by data centers," and then, in a sentence that reaches well past TCEQ, declared that "no other state agency shall move forward with regulatory approvals related to data centers until this information is acquired." Three days later the Attorney General announced he was investigating "hundreds of data center developments" that did not return the state's water survey, and named 18 counties to start.

Between those two letters, the Public Utility Commission quietly finished the rule that will govern every large load interconnection in ERCOT from here on: $50,000 per megawatt of financial security, posted before ERCOT will even study you, with a 20 percent haircut if you withdraw after capacity is allocated. And the deals kept signing anyway. Vistra sold 207 MW of contracted power to a data center in Odessa, Kodiak Gas Services sold 76 MW of behind-the-meter engines to a West Texas operator, and Meta bought another 144 MW of Gonzales County solar. Five stories, one theme: the August pause has become a regime, and capital is routing around it in real time.

"No Other State Agency Shall Move Forward"

The August 26 ERCOT pause only reached grid-connected loads of 75 MW and up. That left the behind-the-meter campuses, the ones burning gas on site precisely so they never have to ask ERCOT for anything, outside the fence. The September 21 letter closes that gap. Every island-mode campus in Texas needs TCEQ air authorizations for its turbines and engines, and TCEQ now says it is not issuing them. Spokesperson Ryan Vise told Houston Public Media that "at the direction of Governor Greg Abbott, the Texas Commission on Environmental Quality (TCEQ) has paused the issuance of all air and water permits and authorizations related to the construction or development of infrastructure directly supporting data centers while ERCOT completes its comprehensive grid and community impact audit." TCEQ owes the Governor a compliance update by October 19.

What is sitting in that queue matters. The Texas Tribune's July inventory of pending data center air files included the Stargate campus in Abilene, which wants to add 41 more turbines and 18 more generators on top of what it already runs, Meta's El Paso campus with a new 366 MW gas plant, and Chevron's 2.5 GW to 5 GW gas complex in the Permian Basin, which Chevron has separately contracted to Microsoft for 20 years. None of those projects was ever going to show up in Batch Zero. All of them now need a state agency to move forward, and the state has told its agencies not to.

The letter also contains the sentence the industry should be reading twice: "Finally, I will work with the Legislature to eliminate any financial incentives for data centers." That is not an audit. That is a platform. The Data Center Coalition's Dan Diorio gave NBC DFW the industry's position in one line: "Work with us, put those guardrails in place, regulate us, but don't ban us." Bloomberg, working from Data Center Watch's tally, put the national context on the table the same day: at least 45 projects worth $68 billion were blocked or delayed across the country between April and June. Texas used to be where those projects went when somewhere else said no.

"Hundreds of Data Center Developments," a Class C Misdemeanor, and 18 Counties to Start

Last week I flagged the Governor's September 14 directive telling the Water Development Board to start referring non-responding data centers to prosecutors. On September 24 the prosecutor showed up. Attorney General Paxton's release says his office "is currently investigating hundreds of data center developments to ensure that they are transparent about their water usage and fully compliant with the law," and lists the counties under initial investigation, "including" Harris, Montgomery, Travis, Dallas, Tarrant, Smith, Bexar, Tom Green, Potter, Randall, Lubbock, Midland, Ector, Wichita, Victoria, Brazos, Nueces and El Paso. No company names. No project names. The word "including" is doing real work in that sentence, because the list is explicitly a starting point.

The statute is Water Code §16.012(m), and it is short. Fail to return the survey and you have committed a Class C misdemeanor, you are ineligible for TWDB funding, and you are "ineligible to obtain permits, permit amendments, or permit renewals" from TCEQ. Read that last clause next to the September 21 letter. The permit pause is discretionary and temporary. The permit ineligibility for survey non-respondents is statutory and does not lift when the ERCOT audit ends. A campus that ignored a water survey in 2025 has a permanent paperwork problem that no amount of December 10 reporting fixes.

The response rates explain the enforcement mood. TWDB surveyed 329 data centers in 2025 and got responses from nearly 30 percent, per the Tribune. For the 2026 round, TWDB's Temple McKinnon told the Senate Water, Agriculture and Rural Affairs Committee on September 2 that the agency sent 341 notices, refined the list to 324 after removing duplicates, and had a 30 percent response rate as of August 26. Seven in ten data centers in Texas did not fill out a water form that carries a criminal penalty. TWDB owes the Governor its own progress report on October 14, five days before TCEQ's. The state now has three agencies on staggered deadlines, and every one of them is producing a list of names.

$50,000 a Megawatt and a 20 Percent Haircut: The PUCT Adopts §25.194

The rule got almost no coverage, which is strange for a document that sets the price of admission to the largest interconnection queue in the country. At its September 18 open meeting the Commission adopted new 16 TAC §25.194 in Project 58481, the SB 6 large load interconnection standards, with changes from the March draft. The order runs 270 pages across three PDFs. The provisions that will show up in term sheets fit in a paragraph.

The rule applies to any large load customer not energized as of the effective date that seeks a new interconnection of 75 MW or more at a single site, an expansion that crosses 75 MW, an expansion of 75 MW or more on a site already above it, or co-location with a generation resource. Before ERCOT includes you in an interconnection study, you sign an intermediate agreement, make your disclosures, and post $50,000 per MW of financial security. When the standard large load interconnection agreement is executed, the security resets to the greater of $50,000 per MW of contracted peak demand or the system upgrade costs allocated to you by the study. The separate "interconnection fee" from the proposed rule is gone. Withdraw before the study begins and you get all of it back. Withdraw after ERCOT has allocated transmission capacity to you and ERCOT keeps 20 percent of the security tied to that capacity. Once you energize, 20 percent comes back, and the rest returns in 20 percent increments as you hit the minimum billing demand milestones in your agreement. Submit false, inaccurate or unverifiable information, including in a Planning Guide Section 9 filing, and the security can be forfeited and the capacity reallocated. Refuse to cooperate with the audit and the order points at enforcement, penalties and loss of allocated capacity.

Do the math on a 500 MW request. That is $25 million posted before a study, a $5 million forfeit if you walk after allocation, and a return schedule that stretches across your ramp. The Commission adopted the refundability language proposed by Black Mountain, Skybox and the Texas Energy Buyers Alliance, rejected the 10 percent cap the wind and clean power associations asked for, and declined to prioritize load types or touch base-versus-studied eligibility, which stays with PGRR 145. Batch Zero loads must execute an SLLIA at the conclusion of the batch study. The updated implementation roadmap staff filed September 22 in Project 58317 says the SLLIA form itself gets a proposal for publication in October and adoption no later than March 2027, the demand management rule in Project 58482 gets its adoption order in January 2027, and the transmission cost recovery rewrite in Project 58000 lands in December, once staff finishes synthesizing 909 pages of comments. The order does not state an effective date; under the standard 20-day clock it should take effect in early October. Watch the Texas Register.

The Deals Did Not Wait: 207 MW in Odessa, 76 MW Behind the Meter, 144 MW of Solar

On the same Monday the Governor halted permits, New Era Energy & Digital announced a 20-year power purchase agreement between its subsidiary TCDC PowerCo and Luminant ET Services Company, a Vistra affiliate, for a minimum of 200 MW and up to 207 MW at the Texas Critical Data Center in Odessa. The power comes from what New Era describes as Vistra's 1,180 MW gas plant immediately adjacent to the 493-acre site; Vistra itself called the Odessa plant 1,054 MW of combined cycle when it bought it in 2017. Delivery is expected in the third quarter of 2027. Vistra gets a 5 percent non-voting interest in the powered portion of the project, a right of first refusal on future TCDC phases, and a right of first offer on other New Era projects. Chairman and CEO Charlie Nelson called it "an incredible milestone which we believe materially reduces phase one development risk at TCDC."

The interesting part is what it replaced. On February 27 New Era, then under CEO Will Gray, announced a 450 MW behind-the-meter plan for the same campus with Thunderhead and Turbine-X, and Gray called behind-the-meter "the definitive solution." Seven months, one CEO change and one Governor's letter later, phase one is a grid-supplied PPA from an existing plant, no new turbines, no new air permit, and a generator holding equity in the load. Ector County, where the campus sits, is on the Attorney General's list. That is the shape of a deal built to survive September 2026: existing steel, an incumbent counterparty, and nothing that needs a state agency to move forward.

Kodiak Gas Services went the other way. Its September 21 release announced a 76 MW behind-the-meter baseload contract with an unnamed West Texas data center operator, roughly 40 reciprocating gas units, a six-year term, deployment starting in the fourth quarter of this year and scaling into the first quarter of 2027. The operator's tenant is an investment-grade hyperscaler, and a "GPU designer" is guarantor on the lease. CEO Mickey McKee said "the size fits our available power fleet, the location is within our established operational footprint in West Texas, and the customer has strong commercial and financial support." It is Kodiak's second data center power contract on the way to a stated 2 GW by 2030. Forty engines on a pad need TCEQ authorizations, and the release went out the same day TCEQ stopped issuing them. Either those authorizations are already in hand, or that Q4 start date just became the most interesting line in the release.

And Meta, which has never once slowed a Texas procurement for a Texas headline, signed a 144 MW PPA with Apex Clean Energy for Starling Solar in Gonzales County on September 16. Apex says commercial operation in 2027; the ERCOT queue lists January 2028. It is the third Apex-Meta deal in Texas after Aviator Wind East and Angelo Solar, and the seventh overall. Meta takes the environmental attributes. Nobody in the release mentioned an audit.

Batch Zero Update: The Deadline Passed, and Nobody Published a Count

The 231 notarized verification questionnaires were due at 5 p.m. on September 23. As of this writing ERCOT has not said how many came in. The last public number is the one I printed last week, zero submitted as of September 11, and ERCOT's own deck promised that "future updates will include data center response rates." What ERCOT did file, on September 21 in Project 59142, is the full set of question reference guides for both RFIs, along with a note that recipients may request an extension to September 30 and that the RFI was revised to version 1.1 on September 19, mid-window, for changes ERCOT describes as technical or typographical. The community impact survey, the one that goes to 461 projects, is still due October 12. So the honest scoreboard is: deadline passed, extensions available for a week, no response rate published, and the next hard number is whatever ERCOT chooses to disclose before December 10.

The docket filled up with everyone the audit has not yet reached. Sixteen filings landed between September 11 and 14 from residents of Archer County asking the Commission to apply the audit specifically to Project Raptor, a 1,000 MW campus on roughly 2,800 acres on Three Way Road that the county's own FAQ identifies as Google's, connecting at a Bowman switch station on the property with partial operation in 2028 and full build in 2031. One couple's filing put the distance at 1,200 feet from their home. Wichita County next door is on the Attorney General's list. Separately, Synergen Green Energy asked for a good-cause exception to enter Batch Zero for a roughly 300 MW green ammonia plant in Calhoun County, in STEC territory, with $30.5 million spent and $568 million budgeted, and made the argument every non-data-center industrial in Texas is now making: "industrial large loads should not be collateral to the onslaught of large computational loads." Synergen notes ERCOT's August 10 filing acknowledged 41 good-cause requests. None are on the October 1 agenda.

One correction to the framing I have been using. The medium loads, 25 MW to under 75 MW, are not a footnote. ERCOT's September 11 filing counts 214 medium-load projects totaling 12,535 MW receiving the community impact RFI, up from the 157 facilities and roughly 8,800 MW ERCOT described as an April snapshot. That is 12.5 GW of data center and crypto load that was never in Batch Zero and now has its own questionnaire, its own deadline, and its own place on the Governor's list.

What to Watch Next Week

Wednesday, September 30: Senate Business and Commerce, 9:00 a.m., E1.012. Chairman Schwertner's interim charge includes a review of "ERCOT's proposed changes to its interconnection process to determine what guardrails should be enacted." The Governor has already said he wants the incentives gone. Listen for whether the committee agrees. It is also the last day for extended verification RFI responses.

Thursday, October 1: PUCT open meeting, 9:30 a.m. Docket 59115, the Silver Basin Digital Infrastructure 180 MW co-location behind the 204 MWac Taygete II solar plant in Pecos County, is up for discussion and possible action after initial briefs on September 23, with ERCOT proposing a 30-minute curtailment condition. The Comanche Peak net metering docket, 59399, and the Haskell data center docket, 59943, are on the same agenda. These are the first SB 6 co-location cases to reach decision.

Tuesday, October 6: ERCOT SB 6 Large Load Curtailment Workshop, 9:30 a.m. The proposed operations framework and registration process for the curtailment obligation that comes with every one of these interconnections.

The effective date of §25.194. Watch the Texas Register for the Secretary of State filing. Every SLLIA negotiation in the state is waiting on it, and the SLLIA form itself is not due for publication until October.

October 12, 14 and 19. Community impact RFI due, TWDB's enforcement update to the Governor, and TCEQ's compliance report, in that order. Three lists of names in eight days.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice, and Andi is not your broker. Links go to primary sources wherever possible; form your own view.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to Edge Cases

Seventy-Five Megawatts Is Now a Design Parameter

On Thursday, CNBC reported that Anthropic and OpenAI are both shopping data center allocations of 20 to 30 MW — sounded out across the UK and the Nordics, with sources saying both companies have discussed similar deployments in the United States. Two frontier labs that have spent a year signing gigawatt paper are now asking about buildings the size of the ones this newsletter covers. Not because small is elegant. Because inference shards across sites and a 25 MW hall energizes three years sooner than a 500 MW campus.

That was Thursday. The rest of the week said the same thing in four other dialects. Soluna filed an interconnection request for another 50 MW in the Texas Panhandle and said in the filing, in so many words, that it sized it to fall under the large-load threshold. Host Digital's merger filings finally broke out what it paid for a converted Oklahoma building versus what it paid for the electric service agreement attached to it, and the answer will reorganize how you underwrite a retrofit. Nscale's S-1 put the first public price on what an NVIDIA guaranty costs a tenant. And in Bulloch County, Georgia, eleven residents sued a city over whether 99 MW is an edge data center or a hyperscale one.

A note on size discipline, since four items below carry loads above 75 MW: each is here because it publishes a comp the smaller band prices off — a guaranty rate, a suite module, a $/kW-month — not because it is a big campus. Digital Realty's 672 ksf Garland filing is the clearest example. DFW45 is an 80 MW building, which is not this newsletter's beat, except that it is built as ten 8 MW suites. Eight megawatts is the module. A 25 MW tenant buys three of them. That is the entire market in one TDLR filing: 119 W/sf gross, $3.75M per MW of build cost, sold in eighths.

Host Digital Paid $27.7 Million for a Building and $33.5 Million for the Right to Plug It In

We ran the East Tulsa site two issues ago at $161 a kilowatt-month. What we did not have then was the cost basis, because it was not public. It is now. Host Digital's super 8-K on Sept 17 and its 424B5 on Sept 21 break the acquisition into its two halves, and the halves are not the size you would guess. The building and parking lot went under contract for $27.7 million. T-20 Mining LLC — an entity whose meaningful asset is the electric service agreement — was acquired in February for roughly $33.5 million. The power contract cost 21 percent more than the real estate.

Run it per megawatt and it is cleaner still: about $779,000 per contracted IT megawatt for the ESA alone, against $346 a square foot for the box. Nobody in this market has been able to point at a public number for what a live meter is worth separate from the slab underneath it. Now there is one. Anyone still pricing conversions off comparable-building sales is pricing the wrong asset.

The filings also disclose a second Oklahoma site that had not surfaced before: roughly 16 MW of critical IT load on a 12-year take-or-pay to a publicly traded AI cloud provider, about $391 million over the base term and $819 million if it runs the full 22 years. That works out to roughly $170 a kilowatt-month on average — a premium to the Tulsa building's $161, on a shorter term and a smaller block. Two caveats worth carrying: the escalator on Site II is not disclosed, and the investment-grade backstop on Tulsa has not taken effect. It is conditioned on the project financing closing, and Host disclosed a $27.5 million working capital deficit at July 31 alongside a going-concern note. The lease is real. The credit enhancement is a plan.

Deal specs. Sponsor: Host Digital Inc. (NYSE American: HOST), f/k/a Healthy Choice Wellness · Site: Site I within Tulsa city limits, Centergate Business Park, east Tulsa; Site II "northeast Oklahoma," address and mileage n/d · Footprint: 80+ ksf (Site I); n/d (Site II) · Load: 43 MW critical IT (Site I, ≤537.5 W/sf — ceiling, computed on the disclosed "80,000+" sf); 16 MW (Site II, density n/d) · Lease: Site I 15-yr take-or-pay, 3.0% annual escalator, renewable to 30 yrs, ~$1.25B base term; Site II 12-yr take-or-pay, escalator n/d, ~$391M base term · Tenant credit: unnamed large private cloud (Site I) and unnamed public AI cloud (Site II); IG backstop disclosed but not yet effective · Acquisition: $27.7M building and lot (~$346/sf) plus ~$33.5M for T-20 Mining LLC and its ESA (~$779k per contracted IT MW) · Source: Form 8-K, Ex. 99.2 and 424B5.

NVIDIA's Signature Costs 6.97 Percent, and Now We Have the Receipt

Every landlord who has been handed a non-investment-grade neocloud tenant in the last eighteen months has been told there is a parent backstop and has had no way to price it. Nscale's S-1, filed Sept 18, prices it. NVIDIA guarantees up to $860,340,000 of Nscale's obligations under a net lease on the Ward County, Texas facility. The consideration Nscale gave up: warrants for up to 9,476,700 Series B preferred shares, aggregate value $60 million, exercise price one cent. That is 6.97 percent of the guaranteed principal, or about $300,000 per megawatt on a 200 MW building. There are also contingent default warrants that issue if Nscale defaults on a lease NVIDIA has guaranteed, which is the part to read twice.

Ward County is 200 MW and would not normally appear here. It appears because the guaranty rate is a comp, and because the same filing publishes the portfolio table. Of Nscale's seventeen active and contracted sites, nine are colocation, sized 5, 6, 9, 15, 16, 20, 24, 30 and 40 MW. That is 165 MW across nine leases, an 18.3 MW average. The company raising billions on gigawatt narrative is executing most of its site count in this band.

The structure showed up again three days later without a price. Kodiak Gas Services announced a six-year, 76 MW behind-the-meter supply agreement with an unnamed West Texas operator, roughly 40 reciprocating gas units, deploying in Q4 and scaling into Q1 2027. The credit language in the release is the story: the operator "is contracted with an investment-grade-rated hyperscaler and has a GPU designer as guarantor of the data center lease." Kodiak does not name the guarantor and neither will I. But a chip vendor standing behind a 76 MW colo lease is now a template rather than an anecdote, and Nscale just told you what one of those signatures goes for.

Deal specs. Sponsor: Nscale Ltd (S-1 filed Sept 18); guarantor NVIDIA · Site: Ward County, TX — municipality and mileage n/d in the filing · Footprint: n/d — Nscale discloses no square footage for any site · Load: 200 MW-IT leased (density not computable) · Lease: net lease, term and escalator n/d; NVIDIA guaranty capped at $860,340,000 · Guaranty price: $60M in penny warrants = 6.97% of guaranteed principal, ~$300k/MW · Portfolio comp: nine colo sites totaling 165 MW, 18.3 MW average · Source: SEC S-1. Kodiak: 76 MW, 6-yr behind-the-meter supply, ~40 recip units, IG hyperscaler tenant, GPU-designer lease guarantor unnamed, value n/d · Source: Kodiak IR.

Fifteen Years, Two Five-Year Options, and Not One Megawatt Reconfirmed

Blockfusion's North East Data subsidiary signed a definitive anchor lease with CoreWeave at its Niagara Falls campus on Sept 16, converting a letter of intent from June 30. Fifteen-year initial term, two five-year renewal options, a converted decommissioned power plant inside the city limits, NYISO Zone A hydro, Avison Young on the leasing side, Jones Day and Phillips Lytle on the papers. A clean announcement.

It is what is missing that should interest you. The June LOI carried 85 MW of guaranteed take-or-pay inside an up-to-300 MW envelope and a $2.8 billion fifteen-year revenue estimate. The Sept 16 definitive-lease release restated none of it. The company says terms will appear in an amended Form S-4 — it is merging into Blue Acquisition Corp. When a SPAC-bound landlord goes quiet on capacity at the exact moment the capacity becomes contractual, that is the number to chase, and Blockspace flagged it before anyone else did.

If the June figures survive into the S-4, the implied rent is roughly $183 a kilowatt-month — $2.8B over 85 MW over fifteen years. That would sit above Host's $170 on a longer term with a weaker tenant credit, which is either a hydro premium or a number that is about to change. The expansion tranche, for its part, is conditional on Blockfusion procuring firm power and CoreWeave approving the power infrastructure plan. CoreWeave can withhold. Read the envelope as an option, not a pipeline.

Deal specs. Sponsor: Blockfusion USA via North East Data LLC, merging into Blue Acquisition Corp. (Nasdaq: BACC) · Tenant: CoreWeave, Inc. (Nasdaq: CRWV), public, non-investment-grade · Site: within the City of Niagara Falls limits, Niagara County, NY; converted decommissioned power plant, NYISO Zone A; street address n/d · Footprint: n/d · Load: 85 MW take-or-pay per the June 30 LOI, not reaffirmed at signing; up-to-300 MW campus envelope; density not computable · Lease: 15-yr initial plus two 5-yr options; escalator n/d; separate Expansion Agreement conditioned on firm power and tenant approval · Deal value: ~$2.8B base term / ~$5.4B all options — June LOI estimate only · Source: Blockfusion release.

Soluna Sized the Next Fifty Megawatts to Miss the Queue

Soluna furnished an 8-K on Sept 14 disclosing a load interconnection request for an additional 50 MW at Project Dorothy in Briscoe County, behind the meter at the 150 MW Briscoe Wind Farm it bought in April. Dorothy 1 and 2 are 98 MW energized. The sentence that matters says the new request falls below the large-load threshold and the provider is studying it directly.

That threshold is 75 MW. Below it, you get a direct study. At or above it, you join a queue that held more than 438,000 MW of requests as of mid-year, roughly 90 percent of it data centers. Soluna is the second public company in ten days to disclose in a filing that it sized a project under that line on purpose; AIB used nearly identical language about its own sub-75 MW site the same week. This is no longer a preference. It is a design constraint that shows up in the engineering before it shows up in the pro forma, and it is the single best argument for why the 5-to-75 MW band is where paper is actually getting signed.

Deal specs. Sponsor: Soluna Holdings, Inc. (Nasdaq: SLNH) · Site: Project Dorothy, Briscoe County, TX (Texas Panhandle), behind the meter at the 150 MW Briscoe Wind Farm; miles to nearest city limits n/d · Footprint: n/d · Load: 98 MW energized across Dorothy 1 and 2; +50 MW requested, below the 75 MW large-load threshold, under direct study; density n/d · Lease: n/a — interconnection request, not a lease; no tenant, term or escalator disclosed · Portfolio: 266 MW across Dorothy and Kati; the 100 MW Dorothy campus conditionally classified Base Load · Source: Form 8-K, Ex. 99.1.

One Megawatt Under Hyperscale, and Now It's in Superior Court

Statesboro amended its Unified Development Code on June 2 to permit smaller edge data centers in its office district while prohibiting hyperscale ones. On Aug 18, roughly ten weeks later, the mayor and council voted 3-2 to rezone almost 27 acres at 6539 Burkhalter Road from R-4 high-density residential to O, office and business. The plans 4am Development submitted describe a 99 MW project.

Eleven residents and Coastal Communities United have now petitioned Bulloch County Superior Court to void the rezoning, naming both the city and 4am Development. Their argument is arithmetic: the ordinance bans hyperscale, the project sits one megawatt under the threshold, and a code amendment adopted a month before the application arrived does not look accidental from the cheap seats.

I have not seen a case before that turns on where the numerical boundary of "edge" sits in a municipal code. If a Georgia court puts a defensible line at 100 MW, every ordinance drafted on that template — and they are being drafted everywhere right now — becomes a hard cap rather than an aspiration. Which, for a developer who has spent the last year arguing that 40 MW is a neighbor and 400 MW is a land use, is not the worst outcome available.

Deal specs. Sponsor: 4am Development, LLC · Site: 6539 Burkhalter Road, within Statesboro city limits, Bulloch County, GA; ~26.5 acres · Footprint: n/d · Load: 99 MW per plans submitted by the developer, as characterized in the petition; density not computable · Lease: n/a — land-use entitlement; no tenant, term or value disclosed · Entitlement: R-4 to O; UDC amended June 2, 2026; Planning Commission 5-1 on Aug 4; Mayor and Council 3-2 on Aug 18; petition to void filed in Bulloch County Superior Court · Source: Statesboro Herald.

What to Watch Next Week

Host Digital's Tulsa closing, on or before Sept 26. The 8-K puts the $27.7 million building acquisition on a deadline at the end of this week. If it slips, the 43 MW lease and the investment-grade backstop are both sitting on an option rather than a deed.

Blockfusion's amended Form S-4, no date given. The company has said the anchor lease and Expansion Agreement terms go in the amendment — capacity, take-or-pay quantum, escalator, security. It is the highest-value document in the pipeline and it will either confirm the $183 a kilowatt-month or blow it up.

Loudoun County's pause resolution, no date announced. The board voted 7-1 on Sept 15 to direct staff to draft a twelve-month halt on legislative data center applications. It only directed the drafting. Until the board adopts the resolution itself, nothing is frozen and the Dillon's Rule workaround is untested.

Lawrence, Kansas, next city commission cycle. The planning commission voted 6-1 on Sept 21 to move data centers from by-right to special use permit, a regime that outlives the city's two-year moratorium. The dissent objected that the amendment cannot tell a 20 MW inference site from a hyperscale campus. Watch whether anyone writes a megawatt threshold in before adoption.

Indianapolis MDC, Oct 21. The Metrobloks abatement hearings resume, delayed from Sept 16. First test of whether the 60-percent-over-ten-years real estate and 90-percent-over-fifteen equipment template the commission gave Sabey holds a second time inside a county that has otherwise banned new data centers through 2027.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Barrio Energy Research

Barrio Energy Research

Market Intelligence Analyst | Barrio Energy

The Grid Report is researched and drafted by the Barrio Energy market research desk and edited by Ivan Pinney, Principal. Every figure links to a primary source. Corrections and tips: info@barrioenergy.com.

← Back to The Grid Report

"Very, Very Intrusive": 461 Surveys, 231 Notaries, and a Board That Voted Itself a 30% Raise

Last week I said the Batch Zero scoreboard was self-reported and that ERCOT had published nothing. On September 11, two days before that issue went out, ERCOT filed the aggregate in Project 59142, and the numbers are worth the wait: 362 large loads and 191.8 GW made it into Batch Zero, split between 66.4 GW of base load and 125.4 GW of studied load. 302.2 GW across 373 projects did not. The studied bucket, the one that gets studied rather than served, is almost twice the size of the one that gets served.

Then the state started counting in earnest. ERCOT issued 231 notarized eligibility questionnaires due September 23, sent a community impact survey to 461 data center projects due October 12, and the Governor told the Water Development Board to start referring data centers that skip the water survey to prosecutors. The ERCOT board chose the same week to approve a compensation package for its CEO with a potential 2027 value of $6.47 million and to raise its own pay 30 percent. The CEO package lasted about six hours. The board raise is still on the books. Elsewhere, Oracle bought 1.7 GW of existing West Texas wind on paper for Abilene, and Blue Energy filed the first half of a nuclear construction permit at the Port of Victoria. Five stories, one theme: the era of announcing megawatts is over, and the era of documenting them has arrived.

191.8 GW In, 302.2 GW Out, and 0 of 231 Have Hit Submit

The September 11 filing, signed by Chad Seely, ERCOT's general counsel, is the first category-by-category accounting of the September 3 conditional classifications. Base load, the 66.4 GW that ERCOT intends to plan around, breaks down as follows: 9,085 MW across 50 projects energized before March 25, 2022; 13,176 MW across 54 energized since; 6,604 MW across 17 that were in the May 2026 QSA or IVRT rounds or earlier; 3,360 MW across 10 in the Permian Reliability Plan; 4,173 MW across 13 "committed" loads; a single 1,200 MW PURA 39.169 net-metering load; and the big one, 28,761 MW across 59 "advancing" loads. Advancing is the largest base-load category by a wide margin, and it is the category built entirely on attestations of financial commitment. That is where the December verification report will do its work.

Studied load is 125.4 GW across 158 projects. Of that, 9,478 MW across 11 projects elected the WLPUN path, 8,515 MW across 11 elected to be price-responsive under PCLR, and 107,398 MW across 136 projects asked for firm service and got a study. Nine loads are in conditionally, subject to a future good-cause exception on eligibility. And every number carries the same footnote, which I will reproduce because it is the most honest sentence in the deck: "#s and MWs are subject to change based upon dispute processes and eligibility verification process."

Now the verification tracker, as of 7:00 a.m. on September 11. 231 RFIs issued, 100 percent delivered, 187 of 231 handed off to an external contact at the company, 16 of 231 with any answers saved, and zero submitted. Total answers saved across all 231 questionnaires: 0.9 percent. All 231 are due September 23. Two hundred ninety-two people have portal access, 228 of them on accounts created for this exercise. The RFIs cover 59 advancing loads, 13 committed loads, the one net-metering load, and all 158 studied loads; the templates for the QSA, IVRT and Permian buckets are still marked TBD, and a separate site-verification RFI that "will aid in site inspection" is still pending. December 10 is the filing date for the Batch Zero Eligibility Verification Report and the Community Impact Review Report. December 17 is the open meeting where the Commission gets to act on them. That is the real Batch Zero deadline. Everything between now and then is discovery.

"Very, Very Intrusive": 461 Surveys, About 130 Questions, and a Water Code Offense

The second questionnaire is the one nobody had priced in. The State and Community Impact RFI, issued September 14 under the Governor's August directive, goes to 461 data center projects: 214 medium loads of at least 25 MW and under 75 MW totaling 12,535 MW, and 247 Batch Zero large loads totaling 168,238 MW. Energized data centers are exempt. ERCOT's slide describes "approximately 130 questions that are the same for every recipient"; Houston Public Media, which counted the sub-questions in the released instrument, puts it at more than 250 across nine sections: facility information, reasons for development, financial assistance, power self-sufficiency, water sources and consumption, cooling technologies, community impact, ownership and controlling interests, and a notarized attestation. Responses are due by 5:00 p.m. on October 12. ERCOT "will provide PUCT and Governor a list of non-responding entities," and Seely told commissioners on September 11 that ERCOT will "have essentially a report card where we think that there are deficiencies in responses and be able to make that public as well."

Ed Hirs at the University of Houston gave Houston Public Media the line of the week: "This is going to be considered to be very, very intrusive in a state that usually has a good reputation for free market principles." Maria Faconti of K&L Gates gave the more useful one: "I think there are a lot of people who think that the legislature will make changes, but no one knows really what those changes will be." Asked what happens to companies that do not complete the survey, PUCT spokesman Rich Parsons had previously said in an email that those situations "would be addressed on a case-by-case basis." Case-by-case is a policy. It is just not a published one.

Water got its own enforcement track. On September 14 Governor Abbott directed the Texas Water Development Board to refer past and future failures to file the annual water use survey to county and district attorneys, to notify TCEQ so the non-filer becomes ineligible for permits, amendments or renewals under Chapter 11 of the Water Code, to coordinate with the PUCT and ERCOT on the audit, and to report back by October 14. "Data centers must share the duty to protect Texas water," the Governor said. The Texas Tribune, which pulled the TWDB compliance records, found the industry's track record on the survey: 22 data centers surveyed in 2023 with a 32 percent response rate, 67 in 2024 at 28 percent, and 329 in 2025 at nearly 30 percent. Of 267 facilities new to the survey in 2025, 22.5 percent complied. Failing to file is, per the Tribune's reading of the code, a Class C misdemeanor. It has apparently never been treated as one.

The counter-example arrived the same day, and it was not a coincidence. Cipher Digital, Fluidstack and Anthropic committed $10 million to a new Colorado City Water Infrastructure Foundation to repair the town's well pump station after July storm damage; the mayor told San Angelo LIVE the total rebuild is about $27 million once two grants are counted. Anthropic's Ryan Wilson: "Communities that host AI infrastructure should be better off for it." That is the sentence every one of the 461 survey recipients now has to be able to say with a straight face, in writing, in front of a notary.

"Not the Time to Give the CEO of ERCOT a Multi-Million-Dollar Pay Raise on the Backs of Ratepayers"

Into this atmosphere the ERCOT board walked on Tuesday, September 15, and approved a new employment agreement for CEO Pablo Vegas. The board item lays out a six-year term from January 2027 through December 2032, the final year of the current contract rolled in, so effectively a five-year extension, with 2027 potential earned compensation of $6,470,398: roughly $1.1 million base, a short-term incentive of about the same, a long-term incentive above $2 million, a $587,007 deferred compensation contribution, and a final $1,385,000 make-whole payment from his 2022 hire. The Texas Tribune reported the vote; a PUC spokesperson confirmed commissioners voted the same day to grant the contract, which the board's own resolution made subject to Commission approval. ERCOT later argued the number to print was $4.1 million of maximum 2027 cash pay, which excludes the deferred contribution and counts the long-term award at a $420,000 payment rather than target. Vegas earned $3.6 million in 2024 and is on track for about $4 million this year.

Lieutenant Governor Dan Patrick posted within hours: "During a time of increasing utility costs, this is not the time to give the CEO of ERCOT a multi-million-dollar pay raise on the backs of ratepayers." By the end of the day chairman Bill Flores said the board would not finalize the contract, PUC chairman Thomas Gleeson said the Commission would defer further action, and Vegas told the Tribune it would not be executed and he would remain under his current agreement. No rescission vote was taken. Flores, on the record before the reversal: "This contract extension reflects the value that Pablo has added to this organization over the last four challenging years..." Vegas, after: "Clearly there's an opportunity to clear up what was meant by this contract, and everyone would be well served understanding that better." The board that must accept ERCOT's December verification reports on 191.8 GW of load just discovered it operates with roughly the same political cover as the loads it is verifying.

The item that did not get reversed is the board's own. In the same meeting the directors raised their own compensation 30 percent, from an average of $169,375 to $219,375: a $160,000 base plus a $150,000 retention award vesting at the end of each three-year term, prorated for sitting directors. Flores's own pay goes from $195,000 to $250,000. Effective October 1. Unanimous, Flores abstaining. ERCOT's benchmark for peer nonprofit grid operator directors, from the Meridian study in the board packet, is $150,889. Patrick's Thursday follow-up: "My suggestion to them is to reverse their own increase. If they do not want to serve, I am sure there are plenty of public-service minded Texans who are willing to take their place." For scale, ERCOT cut its administrative fee from $0.63 to $0.61 per MWh at the start of the year on a budget of nearly $486 million, and Texas residential rates have risen about 40 percent since 2020, from 11.50 to 16.11 cents per kWh by ElectricChoice's count. The board raise costs ratepayers almost nothing. It costs the board something else, and they will find out what in the next session.

Oracle Buys 1.7 GW of Existing West Texas Wind for Abilene. New Megawatts: Zero.

Oracle announced on September 15 agreements covering more than 1.7 GW across ten Texas wind projects with Clearway Energy, ENGIE, RWE and Scout Clean Energy, all feeding the ERCOT grid that serves its Abilene campus. Oracle calls them investments in wind energy generation projects; the output, it says, equals the consumption of more than 525,000 U.S. homes and avoids 1.8 million metric tons of CO2 a year against the ERCOT baseline. Mahesh Thiagarajan, executive vice president of Oracle Cloud Infrastructure, framed it as progress toward matching "100 percent of AI data center electricity use with carbon-free electricity by 2035" and as "paying our own way for the energy we use."

The sellers' releases are where the megawatts live. RWE signed a 433 MW virtual power purchase agreement from its existing Panther Creek I, II and III wind farms in Sterling, Howard and Glasscock counties, wind farms that have been running since the late 2000s and were repowered in 2019 and 2021. ENGIE will supply up to 568 MW under what it calls renewable energy supply agreements. Clearway and Scout have not disclosed their share. Only RWE uses the words "virtual PPA," and only RWE says its assets are existing, but a repowered 2009 wind farm is not being built twice. Read the announcement for what it is: a financial hedge and a carbon accounting instrument for a campus that draws firm power from the grid. It adds no capacity to ERCOT, no firming, and no answer to the community impact survey's section on power self-sufficiency. It does put Oracle on the right side of the "paying our own way" argument at exactly the moment the state started asking who is.

Blue Energy Files Half a Construction Permit at the Port of Victoria: Gas in 2030, Reactors in 2032

On September 16 Blue Energy submitted the first part of a construction permit application to the Nuclear Regulatory Commission for its gas-to-nuclear plant at the Port of Victoria, in Victoria County. The design, per the company's August and September releases: approximately 1 GW from two GE Vernova 7HA.02 gas turbines first, then up to 1.5 GW from as many as five GE Vernova Hitachi BWRX-300 small modular reactors, 2.5 GW in total. The turbines are expected online in 2030 and the first reactor in 2032, both subject to a final investment decision in 2027. The filing asks the NRC to allow limited construction activities, including deep foundation and shaft work, so the gas plant can be built while the nuclear review proceeds, and it carries a nearly 300-page environmental report. Part two comes in the second half of 2027 after a year of site-specific data collection.

The money: more than $400 million raised to date, including a July strategic investment from Constellation Technology Ventures, with Societe Generale retained this month to structure project finance. In GE Vernova's own release, GE Vernova Hitachi Nuclear Energy CEO Jason Cooper said the quiet part: "This is what fleet deployment looks like: projects advancing on common technology, licensing work and supply chain capabilities..." The customer, per World Nuclear News, is Crusoe's planned campus nearby, though neither primary release names it. The sequencing is the story. A plant that is 1 GW of gas in 2030 and 2.5 GW of gas plus nuclear in 2032 is a plant that can sign a firm power contract today, which is more than any of Oracle's ten wind farms can say, and it is the first Texas developer to put that specific claim in front of the NRC in a construction permit filing. Watch whether the NRC grants the limited work authorization; that is the mechanism every other gas-first developer in the state is waiting to copy.

What to Watch Next Week

Tuesday, September 22: Regional Planning Group, 9:30 a.m. The RPG meets while 231 questionnaires are still open. Watch for the first transmission project tied explicitly to a base-load large load rather than a studied one.

Wednesday, September 23: the eligibility RFIs come due. Extensions of up to five business days are permissible under Market Notice M-A090926-01, and every company that takes one will be visible. As of September 11, zero of 231 had submitted. Watch for the first public disclosure of a miss, and for the first company with listed equity that says nothing at all.

Thursday, September 24: Batch 1+ and Comprehensive Transmission Planning Workshop #2, 9:30 a.m. The first workshop on August 31 opened the financial security question. This is the meeting where the 302.2 GW that did not make Batch Zero finds out what the next door costs.

Monday, September 28: construction is scheduled to start at Hut 8's Beacon Point. The TDLR filing registered September 9 lists 657,130 square feet, a construction cost of nearly $399 million, and a schedule of September 28, 2026 through November 5, 2027 at 4650 FM 1694 outside Robstown, against two 15-year, 352 MW leases with a combined $19.6 billion base-term value. The Nueces County lease I inferred last week now has a construction schedule on file with the state.

No PUCT open meeting this week. The next are October 1 and October 15. The October 6 SB6 Large Load Curtailment workshop, the October 12 community impact deadline and the October 14 TWDB report to the Governor are the three dates that decide whether the audit has teeth. Jupiter Power, meanwhile, disclosed $1.4 billion of storage financing closed between April and July across 1,500 MW and 3,600 MWh in Texas and Michigan, including Callisto II and Pamela Heights I in Harris County. Batteries do not fill out surveys. That is increasingly the point.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Nobody Disclosed a Square Foot

Four sub-75 MW deals closed or cleared in the past seven days. Between them: 29 acres in Texas, three acres and a building in Arkansas, forty-one acres of a decommissioned Kodak campus in Colorado, and twenty acres under option in western Kentucky. Not one of them disclosed a building square footage. Which means the number this newsletter exists to compute — watts per square foot — is not computable for a single transaction in the transacting middle of this market.

That is not a research failure. That is the finding. The small end of this market has stopped buying buildings and started buying utility paperwork, and the paperwork is what gets priced. AIB Data Centers paid $313,189 per megawatt for two Texas parcels whose entire value is a pair of facilities extension agreements. Z Squared paid for eight interruptible megawatts in south Arkansas with stock it printed, then leased the building back to the seller for a dollar a year. Global AI cleared Weld County on a will-serve letter from a rural co-op. Sphere 3D offered to write an eight-figure check for a substation it will only use three-quarters of. The common thread is that in every one of them, the asset is the interconnection and the building is an afterthought — sometimes literally not mentioned.

$550,000 for an Energized Megawatt, $224,385 for a Dark One

AIB Data Centers (NYSE American: AIB) signed on September 4 and closed on September 11 the cleanest small-site comp of the year, and it is cleanest precisely because the company bought two parcels from two unrelated sellers on the same day at the same campus in two different states of readiness. Property A: 5.00 acres with an existing building shell and a live facilities extension agreement for 15 MW, for $8,250,000 in cash at closing. Property B: 24.385 adjacent acres, acquired through 100% of the membership interests in a Delaware LLC holding the right to fee title, carrying an FEA for 40 MW that has not yet been placed in service, for $8,975,400.

Run the arithmetic the way a buyer would. Property A clears at $550,000 per megawatt. Property B clears at $224,385 per megawatt. Same buyer, same campus, same closing date, and a 2.45x premium for electrons that are actually moving. That spread is the queue, priced in a single transaction, and it is the most useful number to come out of this week. The blended figure across all 29.385 acres and 55 MW is $313,189 per megawatt, or $586,195 per acre.

The structure carries the rest of the lesson. Six million dollars of the Property B consideration does not move until the "Release Date" — defined as the date the utility places the Property B facilities in service — and is secured by an irrevocable standby letter of credit. If the utility has not shown up by December 31, 2028, AIB may substitute a parent guaranty subject to creditworthiness tests. A second letter of credit, this one for $1,754,640, sits with the utility as performance security under the 40 MW FEA — $43,866 per megawatt just to hold the agreement open. The two contracts are expressly linked and had to close concurrently.

Note also where the aggregate stops. Fifty-five megawatts is under the 75 MW line ERCOT uses to classify large loads, which is a convenient place for a campus to land in a year when the large-load regime is the long pole. It does not, however, buy anyone out of the separate community-impact audit, which reaches every non-energized computational load at 25 MW and up. AIB's county, city and utility are all redacted in the filing under the confidential-information carve-out, so the site line below is genuinely blank. In a week defined by missing square footage, a missing address is almost restful.

Deal specs. Sponsor: AIB Data Centers Inc. (NYSE American: AIB) · Site: Texas; county, city and utility redacted in the 8-K — miles to city limits n/d · Land: 29.385 acres (5.00 + 24.385, adjacent) · Footprint: n/d — existing building shell on Property A, square footage not disclosed · Load: 55 MW (15 MW energized + 40 MW contracted); density n/d, no sf denominator; 1.87 MW/acre · Lease: n/a — fee acquisition, no tenant signed · Deal value: $17,225,400 ($313,189/MW blended; $550,000/MW energized vs. $224,385/MW contracted) · Credit support: $6.0M deferred payment LC + $1,754,640 utility LC · Source: Form 8-K.

A Dollar a Year, Paid Entirely in Paper, Closed Inside Two Moratoria

Z Squared (Nasdaq: ZSQR) closed on Paradox Data LLC and its Union County Campus at 713 Industrial Road in El Dorado, Arkansas on September 8 and filed the terms on September 14. No cash changed hands and no debt was incurred. The consideration was 5,000 shares of newly designated Series A convertible preferred with a $5.0 million stated value, convertible at $7.45, with up to $20 million more in the same instrument payable against four milestones — first energization of AI compute, then a binding request for service and an energization event at each of 50, 100 and 150 MW. Roughly eighty percent of the headline $25 million is contingent on a buildout that has not started.

What the buyer actually acquired is 8,000 kVA — about 8.0 MW, interruptible — from Entergy Arkansas, three acres with a building, and a contract on ten adjacent acres. At closing that is $625,000 per energized megawatt. Some secondary coverage put the figure at 80 MW. The filing says 8,000 kVA. A factor of ten is a large thing to lose in transcription, and it is worth checking the exhibit yourself before you underwrite anything off a trade headline.

The leaseback is the part to steal. Under a triple-net lease and relocation agreement dated the same day, the acquired subsidiary is landlord and the seller is tenant, continuing to mine bitcoin in the building at a base rent of $1.00 per year for a term expiring no later than the second anniversary. Rent was never the point; time was. Z Squared is a party solely as to a one-time $500,000 relocation payment on specified triggers, and its aggregate monetary liability under the lease is capped at that figure. Two open items belong in any diligence memo: the Entergy service agreement is still held by the seller and its assignment requires a consent that has not been obtained, and the company's CTO holds an indirect minority interest in the seller, disclosed and cleared by the audit committee as a related-person transaction.

The timing is the tell. Union County is running a data center moratorium through 2027 and the City of El Dorado's own runs to November. Buying an energized, grandfathered site inside a moratorium is not a workaround; it is increasingly the whole strategy.

Deal specs. Sponsor: Z Squared Inc. (Nasdaq: ZSQR), acquiring Paradox Data LLC from Paradox Infrastructure LLC · Site: 713 Industrial Road, El Dorado, Arkansas (Union County) — at/near the city limit, exact setback n/d · Land: ~3 acres with existing building, plus contract on ~10 adjacent acres · Footprint: n/d — building sf not disclosed · Load: 8.0 MW (8,000 kVA), interruptible, Entergy Arkansas; density n/d, no sf denominator · Lease: triple-net leaseback to seller, $1.00/yr base rent, term ≤2 years, no escalator, $500,000 relocation cap; private crypto-pivot tenant credit · Deal value: $5.0M Series A preferred at closing ($625,000/MW), up to $25M with milestones · Source: Form 8-K.

Forty-One Acres of Kodak, and a Will-Serve Letter Good for Three Years

Weld County commissioners voted 5-0 on September 9 to grant Global AI a use-by-special-review permit for a 41-acre data center on the former Carestream Health campus — Eastman Kodak's old Colorado division — at 2000 Howard Smith Avenue West in unincorporated Weld County, adjacent to the Town of Windsor's boundary and roughly sixty miles north of Denver. The daylong hearing drew more than 400 written comments, most of them opposed. It passed anyway, on the reasoning that a data center is a proper reuse of an industrial campus already zoned light-industrial.

The land basis is the cheapest of the week by a wide margin. Global AI bought the full 438 acres for about $15.6 million late last year — $35,616 per acre — from a local developer who had picked up the shuttered Carestream site for $3.5 million nine months earlier. That is roughly a 4.5x markup on dirt in three quarters, with no vertical improvement in between, and it is the clearest illustration going of what entitlement plus proximity to a substation is worth right now.

The power evidence is thinner than the vote suggests. Global AI's proof of service was a will-serve letter from Poudre Valley Rural Electric Association for 35 MW against a 27.5 MW first phase, and opposing counsel put on the record that the letter commits the co-op for only three years and does not describe how the power physically reaches the site. Co-op paper is clearing entitlement. Whether it clears a construction lender is a different question, and one the next six months will answer. Conditions attached: closed-loop cooling, a 65,000-gallon initial fill with roughly 6,500 gallons of annual top-off, noise capped at established ambient, and a decommissioning bond. The company is separately negotiating a pre-annexation agreement with Greeley, which is where the long-term water would come from.

Deal specs. Sponsor: Global AI (New York); site acquired from local developer Martin Lind · Site: 2000 Howard Smith Ave. W, unincorporated Weld County, CO — outside any city limits, adjacent to the Town of Windsor boundary, ~60 mi N of Denver · Land: 41 acres of a 438-acre former Carestream/Kodak campus; 8 existing buildings, adaptive reuse · Footprint: n/d — building sf not disclosed · Load: 27.5 MW Phase 1 against a 35 MW PVREA will-serve letter; density n/d, no sf denominator; 0.67 MW/acre · Lease: n/a — fee-owned, no tenant disclosed · Deal value: $15.6M for 438 acres ($35,616/acre; $567,273/MW on land basis, Phase 1) · Source: CPR News.

DarkHorse Will Build the Utility a 65 MW Substation and Keep Fifty of It

Sphere 3D (Nasdaq: ANY), operating as DarkHorse Technologies, priced a $5.0 million private placement on September 8 and closed it on the 11th: 1,666,661 units at $3.00, each a common share plus a five-year warrant struck at $3.50. The unit price was a 29% premium and the warrant strike a 51% premium to the prior close, with a six-month lock-up — terms that only get written when insiders are buying, and three directors including the chairman and the CEO took about a fifth of the raise. It funded alongside $4.6 million of housecleaning: an Iowa site sold for $1.5 million and roughly 5,500 legacy miners sold for about $3.1 million.

The proceeds back roughly twenty acres under option in Hopkinsville, Kentucky, for a proposed 50 MW facility. The interesting term is not the site, it is the offer attached to it: DarkHorse has proposed to self-fund a 65 MW substation for Hopkinsville Electric System at $8 million to $10 million and release the surplus 15 MW to the utility's other customers. That prices at $123,000 to $154,000 per megawatt of substation built, or $160,000 to $200,000 per megawatt actually retained — which, set against what energized capacity trades for, is cheap goodwill in a country where the binding constraint has become the zoning hearing. The company's own framing is unusually blunt for a deck: right-sized 10 to 50 MW AI factories in the range hyperscale overlooks. Power across its TVA fleet runs about $49 per megawatt-hour. There is still no AI or HPC customer signed at any of its sites, and Hopkinsville's data center zoning ordinance — which we covered when the draft first set its thresholds — has not had its second public hearing yet.

Deal specs. Sponsor: Sphere 3D Corp. (Nasdaq: ANY) d/b/a DarkHorse Technologies, via North Campbell Land Co. · Site: ~20 acres under option in Hopkinsville, KY (Christian County) — parcel undisclosed, separate from the existing Holland Substation operation; miles to city limits n/d · Footprint: n/d · Load: 50 MW proposed, behind a 65 MW substation with 15 MW released to the utility; density n/d, no sf denominator · Lease: n/a — development commitment subject to zoning and TVA/HES approval; no tenant signed · Deal value: $5.0M placement at $3.00/unit; $8–10M substation ($123k–$154k/MW built) · Source: Investor presentation, Form 8-K.

The Only Two Buildings Anyone Measured This Week: 429 and 350 Watts a Foot

Both of these are over the 75 MW line and normally would not run here. They run here for one reason: they are the only projects in the past seven days that disclosed a square footage at all, which makes them the sole source of a power-density comp — the benchmark every deal above will eventually be priced against. That is the exception, and it is worth naming rather than pretending otherwise.

Thor Equities filed a development-of-regional-impact application with Georgia's Department of Community Affairs on September 4 for the Kingston Technology Hub — 350,000 square feet on roughly 560 acres off State Route 293, inside the city limits of Kingston in Bartow County, about sixty miles north of downtown Atlanta. One billion dollars, 150 MW from the Municipal Electric Authority of Georgia, delivery targeted 2030, fifty full-time jobs and 50,000 gallons of water a day. Divide it out and the design density is 428.6 watts per square foot, at $6.67 million per megawatt and $2,857 per square foot of building.

A week earlier Edged topped out OMA01-1 and OMA01-2 in Council Bluffs, Iowa, at College Road and East Kanesville Boulevard, inside the city limits in Pottawattamie County — two buildings of about 285,445 square feet each against a site reportedly totaling 200 MW. That works to 350.3 watts per square foot, identically per building. The parcel had been entitled for a logistics park in 2021 that never got built, which is its own small commentary on land use in 2026. Deal value, lease structure and tenant are all undisclosed.

Four hundred and twenty-nine watts a foot was an aggressive spec two years ago. It is now the number a new-build files on its zoning application, in a county, on the record, five years before delivery.

Deal specs. Sponsor: Thor Equities (Form8tion), via Thor Acquisitions WC LLC · Site: off GA-293, within Kingston city limits, Bartow County, GA — ~60 mi N of downtown Atlanta · Land: ~560 acres · Footprint: 350 ksf · Load: 150 MW from MEAG (428.6 W/sf at full utilization) · Lease: n/d — no tenant disclosed; DRI application filed Sept. 4, delivery targeted 2030 · Deal value: ~$1.0B ($6.67M/MW; $2,857/sf) · Source: DCD.

Deal specs. Sponsor: Edged (Koch Real Estate Investments portfolio company); Turner Construction and Jacobs · Site: College Rd. and E. Kanesville Blvd., within Council Bluffs city limits, Pottawattamie County, IA · Footprint: ~570.9 ksf across two buildings (~285.4 ksf each) · Load: ~200 MW site total (350.3 W/sf, identical per building) · Lease: n/d — tenant and structure undisclosed · Deal value: n/d · Source: DCD.

What to Watch Next Week

Portland votes Wednesday on a 20 MW notification trigger. The council takes up a resolution discouraging non-disclosure agreements with developers and requiring notice whenever a company seeks to build or expand a facility drawing 20 megawatts or more. Portland has seventeen smaller facilities and no hyperscale, which is exactly why the threshold matters — it is set at the floor of the band this newsletter covers, and other cities will copy the number before they copy the reasoning.

Prince William County holds its public hearing September 22. The planning commission has already recommended ending by-right data center development entirely, shrinking the 2016 Data Center Opportunity Zone Overlay District, and imposing a 500-foot buffer from homes and schools with a 120-day grace period. Loudoun's own grandfather-clause amendment comes up October 6. Between them this is the largest single repricing of entitlement value outside Texas.

The ERCOT community-impact audit runs to a December 10 filing. Roughly 157 projects and 8.8 gigawatts sit in the 25-to-75 megawatt band that the audit captures regardless of large-load classification — ownership, controlling interests, public financial assistance, on-site generation, projected and peak load, water consumption and cooling technology, all of it due ahead of a Legislature that convenes in January. Every developer who sized under 75 MW to stay out of the queue regime now owes a filing nobody underwrote.

Vulcan's October note redemption. Vulcan Infrastructure and Power closed a $39.4 million placement on September 10 with Machine Investment Group, Atlas Holdings and Conversant Capital, largely to retire 8.50% senior notes due next month and hold a 34-acre, 40 MW position in Columbus, Mississippi until capacity arrives in Q3 2027. Watch the terms: forced conversion at 215% of VWAP, a make-whole through the second anniversary, and a Black-Scholes cash put on the warrant.

Two moratoria expire in November. El Dorado's city moratorium — the one Z Squared just closed a deal inside of — lapses in November, while Union County's runs to 2027. Charlotte's 150-day pause expires November 5 with staff already recommending an extension. Watch which of these come back narrower rather than longer; the Gallatin, Tennessee council has been explicit that it is trying to write a rule that separates edge facilities from hyperscale, and whoever drafts that language first will get copied nationally.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

ERCOT Sorted the Queue and Published Nothing, So the Market Built Its Own Scoreboard

On September 3 at 3:55 in the afternoon, ERCOT sent Market Notice M-A080326-04 to transmission and distribution service providers, telling them which large loads had been conditionally included in Batch Zero. It did not tell the loads. It did not tell the public. There is no list on ercot.com, no spreadsheet, no press release, no total.

So the market did what markets do when the referee will not post the score. Over the following week, eight publicly traded sponsors announced their own results, one at a time, through press releases and 8-Ks and in one case a tweet. By Thursday a trade publication had assembled those disclosures into the only aggregate scoreboard that exists in Texas. The chart's own footer credits its methodology: "Source: Company press releases, public disclosures | Generated with Chat GPT." Its lead line item is off by 23 megawatts.

The Scoreboard Is Self-Reported, and Nobody Reported a Loss

Start with what is actually documented. IREN said on September 8 that its 2 GW Sweetwater hub was conditionally included as Base Load — Sweetwater 1 at 1,400 MW and Sweetwater 2 at 600 MW. Soluna said ERCOT conditionally classified the full 166 MW Kati campus in Willacy County as Base Load, including the planned Kati 2 expansion. Ionic Digital said TNMP had informed it that ERCOT provisionally classified its remaining 466 MW at Ward County as Base Load, which would take that campus to 700 MW aggregate. Cipher Digital said it had received classifications covering 3.2 GW and declined to say how much of that was base load, how much was studied load, or which sites were involved.

Every one of those is a good result. That is the problem. Eight companies spoke and eight companies cleared. Not one press release this week said a project was excluded, and not one disclosed a dispute filing. ERCOT built a remedy path into the September 3 notice specifically for loads that were submitted as base load and came back reclassified as studied load — Planning Guide Section 9.3.1(2)(a) — which is not the sort of provision a grid operator drafts for a hypothetical. Somebody got moved. Nobody has said so.

The denominator does not arrive until December 10, when ERCOT files its Batch Zero Eligibility Verification Report, followed by a Commission open meeting on December 17. Until then, the sample is every company with listed equity and a favorable outcome. Underwrite accordingly.

"1,402 MW" Is Not 1,402 MW of Batch Zero

Core Scientific filed the cleanest document of the week and it rewards reading past the headline number. The September 10 8-K reports conditional approvals across three Texas sites totaling 1,402 MW. Of that, 371 MW is not in Batch Zero at all: 297 MW at Denton is classified base load under Pathway (a) as longstanding existing load because it energized before March 25, 2022, and another 74 MW was already validated through ERCOT's 2025 Regional Transmission Plan. The filing says both plainly — neither portion is subject to the Batch Zero allocation process.

What is actually in the batch is 1,031 MW: 431 MW at Hunt County as base load under the advancing-large-load pathway, and 600 MW at Pecos split evenly, 300 MW base load and 300 MW studied load. Studied load is not a rejection and it is not an approval. It means the project stays in the allocation queue and may receive less than it asked for, with final results expected in spring 2027. Core Scientific is targeting roughly 1.5 GW gross at Pecos and intends to cover the difference with generation behind the meter.

The 23-megawatt error in the aggregate scoreboard is Denton, listed at 274 MW where the 8-K says 297 MW. It is a small number and it does not change anyone's thesis. It is worth naming anyway, because it is the tell: the only public tally of the largest load-sorting exercise in ERCOT history was assembled from press releases by a trade outlet doing work the grid operator declined to do, and it has already drifted from the filings. That is not a criticism of the outlet. It is a description of the information environment.

Ten Business Days and a Notary

Six days after the classifications went out, ERCOT started taking them back. Market Notice M-A090926-01, issued September 9, began the verification requests for information that trace back to Governor Abbott's August 3 directive. Responses go through RIOO within 10 business days, with an extension of no more than five, and they require notarized attestations from three parties: the load entity, the interconnecting transmission service provider, and the interconnecting distribution service provider.

The penalty language is not hedged. Failure to timely provide a complete response, ERCOT wrote, "will result in the Large Load being excluded from ERCOT's Batch Zero interconnection process." A separate RFI covering state and community impacts is still to come.

Consider what a notarized attestation from three parties actually requires. The developer has to certify facts about a project. The utility has to certify the same facts. Both have to find a notary and a signatory with authority, twice, inside two weeks, in September. ERCOT already has a read on how this market handles technical paperwork: in its August 20 filing to the commissioners, the grid operator reported reviewing 290 dynamic models, of which "approximately 18% were acceptable on first review." The first RFI responses come due around September 23. Watch for the first company to disclose a miss, because on this schedule somebody will.

The Chairman Said "Remand," and Then the Record Went Quiet

Two of the largest pending questions in Texas power were on the Commission's September 11 agenda, and as of this writing neither has produced a signed order.

The first is 765 kV. On September 9, Chairman Thomas Gleeson filed a memorandum in Docket 59475 — the Oncor and LCRA TSC line from Bell County East Switch to Big Hill, the one where the administrative law judges recommended denial. He did not act on the recommendation. He proposed sending it back: "At this time, I believe it is premature to address whether the recommendations in the PFD should be acted on. Instead, for the reasons outlined below, I believe we need to remand this proceeding to SOAH for further processing." His grounds are procedural rather than substantive — the proposal for decision did not address two of the preliminary order issues, including whether the facilities are necessary to meet reliability standards. Oral argument was cancelled the same day. An intervenor filed a response on September 10 captioned as a response to the Chairman's memorandum proposing remand, so the parties understood the posture.

Proposed is not ordered. A chairman's memo is a signal, not a disposition, and remand, abatement, denial and postponement are four different things with four different consequences for a developer's schedule. I have watched this Commission get all four described interchangeably in the same week. As of today the docket shows no order.

The second is Agenda Item 24: Project 58481, the large-load interconnection rulemaking under PURA 37.0561, which came to the meeting as a staff-recommended order adopting new 16 TAC §25.194. The draft puts a price on a place in line — $50,000 per megawatt in financial security before a load is included in an ERCOT study, returned in 20% increments as the project energizes, with 20% forfeited for withdrawing after allocation. The separate interconnection fee that appeared in the March proposal was removed. The last filing in the project is dated September 10. There is no adopted order on file.

So: the rule that prices the queue and the docket that decides whether the Permian gets its first 765 kV line both went to a Friday open meeting, and the public record shows nothing came out. That may resolve on Monday. It may not. Either way, anyone modeling a Texas interconnection this quarter is working from an agenda item rather than a rule.

Three Balance Sheets That Stopped Waiting

While the queue sorted itself, other people bought their way around it.

SoftBank's SB Energy filed an S-1 on September 1 to list on Nasdaq under the symbol SBE, disclosing 8,827 MW-IT of contracted data center capacity. Two Milam County projects — 308 MW-IT and 445 MW-IT, both targeted for 2028, both under construction — name OpenAI as the customer. A Travis County campus at 50 MW-IT is leased triple-net for fifteen years to a SoftBank affiliate. The prospectus also contains the most useful sentence any Texas power buyer will read this month: "No data center capacity is currently in operation." The widely quoted $439 billion backlog is cumulative undiscounted contracted cash across lease lives averaging nearly twenty years, most of it in Ohio, and the filing itself calls it a hypothetical estimate. Treat it as a term-length disclosure, not a revenue figure.

Fluidstack broke ground the same week on roughly 1,100 acres in unincorporated Cameron County near Rio Hondo, a $4 billion first phase with no tax abatements and no county incentives. Head of public affairs Kate Franko: "We pay our own way: our energy, our infrastructure, our water, and full local property taxes, and we build to the Governor's standards from day one." No megawatt figure has been disclosed for the site, which in a week defined by megawatt disclosures is itself the interesting fact.

And Net Power closed on ten Wärtsilä engine-generator sets, about 123 MW, taking phase one of Project Permian to nearly 200 MW. The EPC contract runs to $196,711,035.70, and the same filing states the company has not entered into a power purchase agreement for the facility's output and has not made a final investment decision. Chief executive Daniel Rice: "In eighteen days, we identified this equipment, secured it with appropriate protections, and closed the transaction." Eighteen days to buy 123 MW of engines. Batch Zero results land in April 2027.

What to Watch Next Week

Cipher's site-level split. The company said it would provide details during the week of September 14. Rosenblatt has already guessed at the allocation — Colchis at 1,000 MW, four sites at 500 MW, Stingray expansion at 200 MW — and kept a $30 target against a $16.90 share price. Cipher has confirmed none of it. 3.2 GW with no tier breakdown is the largest undefined number in Texas power right now.

Two orders that should have issued. Watch Project 58481 for the signed §25.194 adoption order, and Dockets 59475 and 59182 for whatever the Commission actually does with the ALJs' denial recommendations. Docket 59336 drew its own joint memorandum from Gleeson and Commissioner Hjaltman on September 10.

The first RFI failure. Notarized attestations from three parties, ten business days, exclusion as the penalty. The earliest responses come due around September 23.

ERCOT's calendar. The board meets September 14 and 15, the first time since classifications went out. The Large Load Working Group meets September 17, which is where the implementation detail gets argued rather than announced. An October 6 workshop takes up the SB 6 large-load curtailment framework.

A number to stop misquoting. ERCOT's all-time peak demand record stands at 91,134 MW, set July 22, 2026, and it is still preliminary pending final settlement. The 91,308 MW figure in circulation is a real-time instantaneous reading. ERCOT's own methodology note is unambiguous: "ERCOT does not count instantaneous loads for demand records."

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

$161 a Kilowatt-Month in Tulsa, 333 Watts a Foot in Dowagiac: The Middle Market Prices Live Power

Nobody in the sub-75 MW market bought dirt this week. They bought meters. A Tulsa business park with 43 MW already landed signed a 15-year take-or-pay worth $1.25 billion. A Michigan bitcoin barn switched off its miners on September 1 so a California neocloud could have its 20 MW. A Nasdaq-listed GPU shop raised $33 million for the specific purpose of renting 6.5 MW inside other people's finished buildings, and its co-CEO said the quiet part in the press release: the scarce input is energized power inside a finished building. Meanwhile in Texas, a liquid-cooled colo filed a $280 million shell outside Austin at $1,453 a foot, and a crypto miner paid half a million dollars an acre for smelter ground because the interconnect was already there.

Five deals, none above 55 MW critical, one land comp above it. The pattern: lease or retrofit an existing box, anchor it with a 10-to-15-year take-or-pay from a neocloud (ideally with an investment-grade backstop), then raise equity or go public against the contracted revenue. The price of that trade is now visible in three different units, and I will give you all of them.

$161 a Kilowatt-Month in an East Tulsa Business Park

Host Digital Infrastructure, mid-merger with Healthy Choice Wellness Corp. (NYSE American: HCWC), announced on August 31 a 15-year take-or-pay lease for 43 MW of critical IT load at 5555 S 129th E Ave in Tulsa's Centergate Business Park. Base-term contracted revenue is roughly $1.25 billion; about $3.2 billion if every renewal option is exercised across a 30-year total term. The tenant is described as one of the world's largest privately held cloud infrastructure companies, and the obligations are backstopped by an unnamed U.S. investment-grade technology company. Delivery is first half of 2027, per the company release.

Do the arithmetic and the lease prices at $83.3 million a year, $1.94 million per MW-year, or about $161 per kW-month, all-in contracted rent with no disclosed separation between real estate and any power pass-through. The structure is turnkey: landlord owns land, building, interconnect, electrical, and cooling; tenant brings the compute. Host Digital's stated thesis is "right-sized" sites of 20 to 100 MW where grid power is available today, which is a polite way of saying it does not want to wait in an interconnection queue with everyone else. The building itself is a conversion, and neither square footage nor the utility substation made it into the release, so the density number stays blank until the merger 8-K drops. The merged company expects to close this month and trade as HOST, which means the lease exhibit, the escalator, and possibly the backstop's identity are a few weeks away.

Deal specs. Sponsor: Host Digital Infrastructure (landlord); unnamed private cloud infrastructure tenant; unnamed U.S. investment-grade tech backstop · Site: within Tulsa city limits, Centergate Business Park, ~10 mi ESE of downtown Tulsa · Footprint: n/d (building conversion) · Load: 43 MW critical IT (density n/d) · Lease: 15-yr take-or-pay, annual escalators (rate n/d), renewal options to 30 yrs, outage abatement, turnkey landlord-owned electrical and cooling · Deal value: ~$1.25B base term (~$29.1M/MW; ~$161/kW-month); ~$3.2B with renewals · Source: GlobeNewswire / HCWC.

333 Watts a Square Foot Where the Miners Used to Hum

Hyperscale Data (NYSE American: GPUS) said on September 2 that every bitcoin miner at its 617,000 sf former manufacturing plant at 415 E Prairie Ronde St in Dowagiac, Michigan, was switched off effective September 1. The reason is the master services agreement its subsidiary Alliance Cloud Services signed in June with an unnamed California neocloud: 20 MW of critical AI load, 10-year initial term plus two 5-year extensions, north of $1.2 billion in revenue over the maximum 20-year term. The customer holds an option on another 32 MW within two years, which would take the contract to 52 MW and past $3 billion. Alliance is retrofitting 60,000 sf of the plant for the customer at an estimated $100 to $120 million, per the company release and DCD's June coverage of the original signing.

This is the cleanest crypto-to-inference conversion comp on the tape because every input is disclosed. Twenty megawatts into 60,000 sf is 333 W/sf in the retrofitted hall, which is real AI density inside a 1972 building. The retrofit runs $5 to $6 million per MW, or $1,667 to $2,000 per square foot of hall, before a single GPU. And the revenue line, $1.2 billion over 20 years on 20 MW, works out to about $3.0 million per MW-year, roughly $250 per kW-month. That is not a rent comp against Tulsa: it is a services MSA that almost certainly bundles power and operations, and the landlord is a microcap crypto pivot with a 340 MW site ambition that includes 40 MW of behind-the-meter gas. But the customer needed the capacity badly enough to tolerate all of that, and Hyperscale Data needed the contract badly enough to turn off the thing that was paying the bills. Both sides of that trade tell you what a live 20 MW in the Midwest is worth right now.

Deal specs. Sponsor: Hyperscale Data / Alliance Cloud Services (owner-operator); unnamed California neocloud (customer) · Site: within Dowagiac city limits, Cass County, MI, ~25 mi NW of South Bend, IN · Footprint: 617 ksf building on 83 acres; 60 ksf retrofitted for this customer · Load: 20 MW critical (~333 W/sf in the retrofitted hall), option to 52 MW · Lease: MSA, 10-yr initial + two 5-yr extensions, escalator n/d, private neocloud customer, crypto-pivot landlord · Deal value: >$1.2B over 20 yrs (~$3.0M/MW-yr); retrofit capex $100–120M (~$5–6M/MW) · Source: PR Newswire / Hyperscale Data.

"The Scarce Input Is Energized Power Inside a Finished Building"

Corvex (Nasdaq: MOVE), the Arlington, Virginia GPU cloud that used to be a health-wearables company called Movano, executed definitive agreements to double its existing Mid-Atlantic colocation deployment and take space in a second existing enterprise-scale data center in the Midwest. Critical IT capacity goes from about 1.5 MW to about 8 MW by year-end 2026, roughly 1,000 GPUs in the Mid-Atlantic and 2,000 in the Midwest, B300 and GB200-class per DCD. Corvex holds a right of first refusal on a further 12.5 MW at the Midwest site, ready for service in Q3 2027, which would take it past 20 MW. The capacity is funded by a roughly $33 million PIPE at $7.75 a share led by Goldman Sachs with Morgan Stanley and Oppenheimer, leaving pro forma cash near $55 million, per the company release.

Corvex would not name either landlord, which is a shame, because this is the tenant's-eye view of the small-block colo market and it rarely gets published. What it did say is the useful part: both sites have live utility power, and the company is pursuing multi-year take-or-pay GPU-as-a-service contracts against the space. Thirty-three million dollars against 6.5 incremental MW is about $5.1 million of equity per MW, or roughly $11,000 per GPU, and that equity is buying servers and fit-out, not real estate. The real estate is the part Corvex explicitly does not want to own. If you run enterprise data centers in Ohio, Indiana, or Illinois with stranded 5 MW blocks, this is what your next tenant looks like: public, thinly capitalized, in a hurry, and willing to sign an ROFR on capacity that does not exist yet.

Deal specs. Sponsor: Corvex, Inc. (tenant); two unnamed enterprise data center landlords · Site: undisclosed Mid-Atlantic and Midwest facilities, both with live utility power · Footprint: n/d · Load: ~8 MW critical by YE2026 (6.5 MW incremental); ROFR on 12.5 MW more (RFS Q3 2027) · Lease: colocation agreements, term and escalator n/d; public microcap neocloud tenant · Deal value: ~$33M PIPE (~$5.1M equity per incremental MW) · Source: PR Newswire / Corvex.

54 MW on a 74 MW Pad in a 2.8%-Vacancy Market

Northampton Capital Partners, the New York middle-market infrastructure shop Geoffrey Strong started in 2023 after co-running infra at Apollo, formed a joint venture with Dallas-based Provident Data Centers to build a turnkey 54 MW critical-capacity data center on a 74 MW site in the North Dallas Corridor, targeting late 2027, per DCD. No address, no tenant, no JV split. Simpson Thacher represented Northampton, Haynes and Boone represented Provident, and Citizens Capital Markets advised Provident, which is a lot of counsel for a deal with this few disclosed numbers. The partners also signed a framework to develop additional "inference-ready" sites nationally.

What makes this worth your time is the market it is landing in. CBRE's H1 2026 numbers put DFW vacancy at 2.8%, with 95% of the 765-plus MW under construction already pre-leased. A 54 MW spec build in that market is not really spec; it is a bet that the pre-leasing rate holds for another 18 months. The 54-of-74 ratio, 73% of site power reaching the critical load, is a reasonable design number and it implies the site power is real rather than aspirational. Provident's design pitch is effectively zero water and quiet operation, which in Collin and Denton counties is now table stakes for a zoning hearing rather than a differentiator. Watch for the address; when it surfaces, the miles-to-substation number will tell you whether "North Dallas Corridor" means Plano or Sherman.

Deal specs. Sponsor: Northampton Capital Partners (capital) + Provident Data Centers (developer); no tenant announced · Site: "North Dallas Corridor," DFW; exact city and distance n/d; Oncor / ERCOT presumed · Footprint: n/d · Load: 54 MW critical on a 74 MW site (density n/d) · Lease: JV (split n/d); turnkey wholesale intent; no lease signed · Deal value: n/d · Source: DCD.

$1,453 a Foot in Hutto, and $500,000 an Acre Down the Road

Colovore, the King Street-owned liquid-cooled colocation operator, registered its Hutto, Texas project with the state on September 2: a one-story, 192,694 sf data center at 2401 Innovation Blvd with an admin area and screened equipment yard, estimated construction value $280 million, start December 1, 2026, completion December 1, 2028, owner of record Colovore Austin 1, LLC, per the TDLR filing and Connect CRE. The Statesman reports 40 MW across roughly five data halls and quotes a $250 million figure; I am using the filing's $280 million. Either way, the project has shrunk from the $500 million, 180,000 sf pitch Colovore made in 2024, and the sf went up while the dollars went down.

The arithmetic is what matters. Forty megawatts into 192,694 sf is about 208 W/sf whole-building, which is modest for a company whose brand is extreme density; the halls themselves will run far hotter than the gross number, and the gross number is what a lender underwrites. At $280 million the shell costs $1,453 per square foot and $7.0 million per MW before the customer's equipment, which is a hard public number on a mid-size liquid-cooled colo in the Austin ring and about half the $/sf of the 2024 version. The site is a 30-acre tract Colovore took control of in July 2025 inside the 118-acre Hutto Crossing park, 2.9 miles from Skybox's 600 MW Hutto PowerCampus and 5.6 miles from Iron Mountain's Hutto build, next door to a parcel Blue Origin is circling for a manufacturing plant.

Which brings me to the one deal above 75 MW in this issue, included because it is the land comp every Central Texas sub-75 MW site will be priced against. Bitdeer (Nasdaq: BTDR) closed on September 1 a fee-simple, all-cash purchase of roughly 200 acres of the former Alcoa smelter ground near its Rockdale facility in Milam County for about $100 million, per the company release. That is $500,000 an acre, about $11.50 per square foot of dirt, for greenfield that happens to sit behind an interconnect carrying 563 MW today and 742 MW planned. Bitdeer's CFO framed it as eliminating lease-renewal risk so the AI/HPC builds can be project-financed. A miner paying half a million an acre for ground it already had under lease is not a real estate decision; it is a financing decision. Colovore's 30 acres in Hutto, 25 miles from Austin instead of 70, now have a comp.

Deal specs. Sponsor: Colovore (King Street Capital Management); landowner Velocis Hutto Innovation JV; no tenant announced · Site: within Hutto city limits, Williamson County, ~25 mi NE of downtown Austin; ~2.9 mi from Skybox Hutto PowerCampus · Footprint: 192.7 ksf single-story on 30 acres · Load: 40 MW (~208 W/sf whole-building), liquid-cooled · Lease: colocation; ground lease vs. fee n/d; no tenant signed · Deal value: $280M construction estimate ($1,453/sf; ~$7.0M/MW) · Source: TDLR TABS2027000200, Austin American-Statesman.

Deal specs (benchmark, >75 MW). Sponsor: Bitdeer Technologies Group · Site: Rockdale, Milam County, TX, ~70 mi NE of Austin, adjacent to the former Alcoa large-load interconnect · Footprint: ~200 acres greenfield (255 acres owned in total) · Load: 563 MW interconnected site-wide, 742 MW planned (density n/a, land only) · Lease: fee-simple cash purchase, no lease · Deal value: ~$100M ($500,000/acre; ~$135K per planned MW) · Source: GlobeNewswire / Bitdeer.

What to Watch Next Week

Host Digital's merger 8-K. HCWC expects to close the Host Digital combination this month and re-list as HOST. The lease exhibit is where the escalator, the abatement mechanics, the square footage, and possibly the backstop's name live. That filing turns a $161/kW-month headline into an actual comp.

Nevada PUCN on Fleet's gas plants, September 8. The commission is due to rule on Fleet Data Centers' two gas plants, more than 360 MW as a two-to-three-year bridge, for its Peru Ridge and South Valley sites at TRIC, 30 miles east of Reno. A yes is the first data-center-specific gas approval in the state and reprices every Nevada site sitting on an interconnect date past 2028, per the Nevada Current.

I Squared's Cogent switch sites, targeted by September 30. The $225 million purchase of ten former Sprint switch sites, 53 MW and 259,000 sf, is slated to close by quarter-end. I covered the pricing and the CEO when it was announced; the closing 8-K is the update, and any change to the $225 million or the site count is news.

Kokomo, Indiana council vote, September 14. Final reading on a data center ordinance with 200-foot setbacks and industrial-only siting. Kokomo is the kind of Midwest secondary market Corvex's landlords operate in; the ordinance either opens or closes the next 10 MW there.

Northampton/Provident's address. The JV was announced without a site. When the address surfaces, the substation distance and the county will say more about the deal than the press release did.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

Around the Queue, Not Through It: $35 Billion in Nueces County, 400 Miles of 765 kV, and a Batch Zero List Three Days Late

At 7:16 p.m. on Monday, August 31, ERCOT issued Market Notice M-A080326-03, informing the market that it "requires additional time to complete its data validation and due diligence processes" and would release the conditional Batch Zero classifications "later this week." August 31 was the deadline. It was also the replacement deadline, granted by the Commission on August 20 after ERCOT missed the original August 7 date. The grid operator has now missed the extension it asked for, on a list that determines which of roughly 300 data centers get to stay in the study that decides whether they get power.

The list did land, on Thursday afternoon, in M-A080326-04. Three days late on a 24-day extension is not a scandal. It is a tell. While ERCOT's front door was closed for data validation, the capital that needs Texas power spent the week going around it: buying land next to substations that already exist, stacking three balance sheets on a bitcoin miner's interconnection agreement, laying gas pipe instead of waiting for a study, and taking a company with zero operating data centers public on the strength of a Milam County lease. The Commission, for its part, approved 400 miles of 765-kV wire and drew an amicus brief from the Attorney General for its trouble. Around the queue, not through it.

"Later This Week": Batch Zero Ships on a Thursday

Thursday's notice tells each transmission and distribution utility which of its large loads are conditionally in Batch Zero — subject to eligibility verification, subject to curing dynamic-model deficiencies, or subject to a good-cause exception the Commission has yet to grant. The utilities have two business days to pass that along to the load. Loads moved from "base" to "studied" can file a Section 9.3.1 dispute, and anyone denied gets 14 business days to resubmit under a different eligibility subparagraph. ERCOT also said it "will not seek a good cause exception for every Large Load that requested it," which is the sentence in the notice worth reading twice.

The classifications start the clock on the disputes, but not on the study. ERCOT's general counsel told commissioners on August 20 that the April 9, 2027 Batch Zero study deadline will be missed and that ERCOT was "still working on what that new timeline might be" — I printed that quote last week and it has not aged. At the August 26 Technical Advisory Committee, ERCOT confirmed that approvals to energize data center and crypto facilities of 75 MW and up are paused until the eligibility verification is complete, with the verification report now planned for December 10. The same TAC meeting took multiple ballots on ERCOT's 2027 Ancillary Services methodology and passed none of them, so the reserve procurement plan for a year in which several gigawatts of new load may or may not show up goes to the Board without a stakeholder endorsement.

The queue those classifications sort is 474 GW, roughly 90 percent of it data centers, per the ERCOT queue figures cited in the Governor's August 3 audit directive. The Batch Zero process was designed to bring order to that number. What it has produced so far is a list, delivered late, of who is allowed to keep waiting.

"Nowhere in the Plain Language of the Statute Are 765KV Lines Mentioned"

Last Friday's open meeting was underway at press time. Here is how it ended: after hours of landowner testimony, the five-member Commission voted unanimously to amend Oncor's certificates for Dinosaur Switch–Longshore Switch (Docket 59315) and Longshore Switch–Drill Hole Switch (Docket 59029) — Import Path 1 of the Permian Basin Reliability Plan, more than 400 miles of the first 765-kV transmission ever approved in Texas, running from Somervell County west to the Permian. Oncor is targeting 2028 for the eastern segment and 2029 for the western one. The AEP Texas and CPS Energy Howard–Solstice line, Docket 59336, was tabled for further deliberation.

The Commission approved the lines the same morning the Attorney General asked it not to. Ken Paxton's amicus brief, filed early Friday in support of American Stewards of Liberty's motion to defer a determination of need, argues that HB 5066 "mandate[s] the Commission to develop a reliability plan to implement, but nowhere in the plain language of the statute are 765KV lines mentioned." That is the state's chief legal officer — and the Republican nominee for U.S. Senate — taking the landowners' side against Oncor, AEP Texas and CPS on a plan the Commission adopted two years ago. ASL says it will seek rehearing and prepare for court. Sen. Kevin Sparks of Midland, whose district gets the power, issued a statement urging the Commission to reserve decisions on the remaining 765-kV dockets until the 90th Legislature convenes in January, and pointed to the SOAH recommendation I covered last week that found Oncor had not proven need on Import Path 2.

The strongest argument for the lines came from the oil patch, not the utility. Diamondback Energy's lobbyist told commissioners the company self-generates about 80 MW and pulls 330 MW from the grid, with a current interconnection wait of more than two years. The strongest argument against them is no longer about landowners; it is about arithmetic. An Evolved Energy Research study published Monday, produced with ClearPath, modeled roughly 5,000 buses and 7,000 lines in ERCOT and found that $10 billion of reconductoring avoids $30 billion of greenfield build in a high-load scenario through 2040 — and that $35 billion of greenfield is still needed on top of it. Two weeks ago I argued that if Texas is going to build wire, it should build 765. The study does not disagree. It says build less of it, later, and restring what you have first. Somebody in Docket 59029 is going to cite it by Thanksgiving.

$35 Billion, 350 Megawatts, Three Balance Sheets, One Interconnection Agreement

The Wall Street Journal reported Monday night that Anthropic signed a roughly $35 billion cloud capacity agreement with Lambda, the Nvidia-backed neocloud, with Nvidia itself holding the lease on the data center. Reuters put the capacity at about 350 MW and the site in Nueces County. There is one 350 MW data hall in Nueces County with a lease that size: Hut 8's Beacon Point campus outside Robstown, where the company disclosed in July a second 15-year, 352 MW lease that took a single unnamed tenant to 704 MW and $19.6 billion of base-term contract value. Hut 8 has not confirmed the tenant, and none of the four companies answered Reuters. Treat the identification as reported, not admitted.

Follow the stack. Hut 8 owns 525 acres and holds a 1,000 MW interconnection agreement with AEP Texas. Nvidia, per the reporting, holds the lease. Lambda installs Nvidia's chips inside Nvidia's lease. Anthropic buys the output. The chipmaker is the landlord's tenant, the tenant's supplier, and the end customer's financier, and the whole structure sits on a bitcoin miner's interconnection agreement for which formal ERCOT energization authorization is still outstanding. Initial energization is scheduled for Q1 2027. See the section above regarding approvals for loads over 75 MW.

This is Anthropic's second reported gigawatt-scale landing on a Texas miner in three weeks. On August 11, Riot announced a 20-year, 191 MW lease at Rockdale with a "leading frontier AI lab" worth about $9.1 billion over the base term; CNBC and Bloomberg named the lab. Miners spent 2024 telling investors they were pivoting to AI. The pivot, it turns out, was mostly a matter of waiting for the customer to arrive with a bigger balance sheet than the miner's.

$500,000 an Acre, Because the Substation Is Already There

On Tuesday, Bitdeer closed on about 200 acres of greenfield in Milam County, near its Rockdale mining site, for roughly $100 million in cash, fee simple. That takes Bitdeer to about 255 acres with 563 MW of interconnected capacity and a plan to reach 742 MW. Riot paid $96 million for its own 200 acres at Rockdale in January, funded by selling about 1,080 bitcoin, and has since put 241 MW of it under contract. Two miners, 400 acres, $196 million, a few miles apart, in a county of 25,000 people. The land is not worth $500,000 an acre. The existing large-load interconnection and the substation next to it are, and Bitdeer's release says as much: the site "positions the Company to pursue additional power allocations over the coming years." KBW kept the stock at Market Perform, noted the price came in under its $131 million estimate, and asked the questions that matter — whether the seller's interconnection and water rights transferred with the dirt, and who exactly owns the aging Rockdale substation.

The third Milam County play went to the SEC. SB Energy, SoftBank's power-and-data-center developer, filed an S-1 dated August 31 to list on Nasdaq and Nasdaq Texas under the ticker SBE, with Nvidia committing $1.5 billion in a concurrent private placement and another $1.5 billion through a prepaid forward. The backlog is $439 billion, $430 billion of it data centers, resting on two Texas campuses — Stargate Milam County for OpenAI, and Cosmos in Austin for SoftBank itself — and one sentence on page one that every underwriter will have to read aloud: "No data center capacity is currently in operation." Trailing twelve-month revenue is about $269 million. The trailing twelve-month net loss is about $3.7 billion, most of it a $2.57 billion warrant fair-value charge in the first half. Press reports put the raise at $5 billion to $7 billion, per Latitude Media. Milam County now hosts three separate gigawatt-class AI power plays — Riot, Bitdeer, SB Energy — on one ERCOT load pocket that is itself waiting on the list ERCOT delivered Thursday.

2.5 GW of Pipe, Zero Named Sites

Cipher Digital's answer to Batch Zero arrived Thursday morning: the company has begun building natural gas lateral pipelines at multiple undisclosed sites capable of fueling up to 2.5 GW of on-site generation, with power targeted before the end of 2027. Cipher will "work with power providers to develop and operate" the plants, and its CEO says the company plans to seek grid connection for the generation capacity as well — bring your own generation now, sell into ERCOT later. The 2.5 GW is what the pipe can carry, not what is built, contracted or leased. Per Blockspace, Cipher is carrying roughly 2 GW gross across McLennan, Mikeska and Colchis awaiting Batch Zero, plus a 900 MW option near San Antonio, none with a firm interconnection date. Two weeks ago its Cotulla project ran into the audit. This week it ordered pipe.

Bring-your-own-generation has its own bottleneck, and it got tighter on August 26 when the White House signed Executive Order 14420, declaring a national emergency over the bulk-power system and restricting equipment from 24 countries at 69 kV and above, with DOE rules due within 120 days. Wood Mackenzie's read, published Wednesday in pv magazine: Chinese manufacturers have supplied more than $22 billion of U.S. bulk-power imports since the start of 2025, the domestic shortage this year runs about 15 percent for power transformers and 8 percent for substations, and the segment that leaned hardest on Chinese units to shave lead times is the 100 MVA-plus class that data centers buy. Every behind-the-meter campus in Texas still needs a step-up transformer. The order did not create the shortage. It just decided who is not allowed to fix it.

What to Watch Next Week

The dispute clock. Utilities have two business days from Thursday's notice to pass classifications to their loads, and base-to-studied reclassifications can be disputed under Section 9.3.1. Expect the first dispute forms, and the first press releases from developers who did not get the classification they wanted, by mid-week.

Project 58481, the large-load interconnection rule. Staff targeted a recommended adoption order for the §25.194 rule — the $50,000-per-MW security, the 80/20 refundability split — this week, with the Commission taking it up at the September 11 open meeting. Howard–Solstice and any ASL rehearing motion on Docket 59029 could land on the same agenda.

ERCOT Board, September 14–15. The 2027 Ancillary Services methodology arrives without a TAC endorsement. Watch whether the Board adopts ERCOT's higher risk-credit parameter for ECRS and Non-Spin anyway.

Large Load Working Group, September 17. The agenda is voltage ride-through solutions currently available — the technical question behind the dynamic-model cure that a slice of Batch Zero is now subject to.

Hut 8 and Lambda. Hut 8 has not named its 704 MW tenant. Lambda is reportedly raising up to $3 billion ahead of an IPO. One of them will say something.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

The 40 MW Gets a Credit Rating

For two years the capital markets treated anything under 100 MW as a rounding error. This week the rounding error got a credit rating. J.P. Morgan and Goldman Sachs closed an investment-grade-rated facility of up to $1.2 billion against a 40 MW colocation retrofit in a North Carolina town of 2,200. I Squared Capital stood up a $1 billion operating platform on 53 MW of ex-Sprint switch rooms spread across nine metros. And a small city in Kentucky drafted an ordinance that makes 75 MW and 50,000 square feet the legal boundary of what it will tolerate. The debt stack, the platform thesis, and the zoning map are all being rewritten around exactly the deal size this audience chases — and this week they were rewritten in Madison, Hopkinsville, and Maysville, not Ashburn.

Five stories this week: Nscale's $3 billion two-site debt close and the $30M-per-MW small-site facility buried inside it, the Saragon platform launch on the Cogent switch-room portfolio, four more EdgeConneX filings outside Austin, a $13.7 billion GPU contract signed in a Georgia town of 2,000, and Kentucky's new math on what counts as hyperscale.

Madison, North Carolina: Population 2,200, 40 Megawatts, $1.2 Billion, Investment Grade

Nscale announced on August 31 that it closed roughly $3 billion in senior secured delayed-draw term loans across two US sites, with J.P. Morgan and Goldman Sachs as joint lead arrangers — and both facilities carry investment-grade ratings with stable outlooks. The larger tranche, up to $1.85 billion, funds the ~275 MW Ward County campus in West Texas — that one clears our 75 MW line only because it travels in a package with the deal that matters here. The deal that matters is the smaller tranche: up to $1.2 billion against a 96-acre colocation retrofit in Madison, North Carolina, about 25 miles northwest of Greensboro, on a former mine and industrial site, specced at up to 40 MW.

Run the division and sit with it: $1.2 billion over 40 MW is $30 million per megawatt of rated, GPU-inclusive debt on a sub-75 MW site. The Ward County tranche pencils at roughly $6.7M per MW — closer to a shell-and-power number — so the Madison figure is mostly silicon, networking, and cooling capex riding on top of the real estate. Two years ago a 40 MW retrofit in Rockingham County would have been a bridge loan and a prayer. Now it is a rated instrument arranged by the two largest names on the street. Context worth holding: Anthropic reportedly signed a $45 billion, 460 MW capacity agreement with Nscale days earlier, which is the kind of offtake that makes lenders comfortable rating a neocloud's paper.

Deal specs. Sponsor: Nscale (borrower via SPVs); J.P. Morgan and Goldman Sachs, joint lead arrangers · Site: Madison, NC, ~25 mi NW of Greensboro, 96 acres at the town's industrial edge; plus Ward County, TX campus in the package · Footprint: n/d · Load: up to 40 MW (Madison); ~275 MW IT (Ward County) · Lease: not a lease — two senior secured delayed-draw term loans, investment-grade rated, stable outlook, funding GPU/network/cooling capex · Tenant credit: neocloud borrower, rated IG at the facility level · Deal value: ~$3.0B total; $1.2B ÷ 40 MW = ~$30M/MW (Madison), ~$6.7M/MW (Ward) · Source: Nscale.

The Switch Rooms Get a Name, a CEO, and a Billion Dollars

An update on the $869-a-foot Sprint switch-room portfolio we covered two weeks ago, because the material terms just changed. I Squared Capital has launched Saragon, a Phoenix-headquartered operating company built on the ten ex-Sprint/Cogent facilities, with up to $1 billion in committed capital and a leadership bench pulled from Seaborn Networks (CEO Steve Orlando) and Cumulus Data/Talen (President Kevin Dalton). The thesis is explicitly AI inference and edge colocation — retail, enterprise, and wholesale — with liquid-cooling support in urban infill buildings that sit largely inside city limits in Chicago, Atlanta, Phoenix, Los Angeles, Kansas City, Baltimore, Houston, Nashville, and Stockton.

The underlying real estate math is unchanged and still the best comp in the segment: $225 million for 259 ksf of colo space carrying roughly 53 MW of installed power — $4.25M per MW, $869 per foot, and about 205 W/sf of installed density across ten buildings averaging 5.3 MW each. That is precisely the inference-edge profile everyone claims to want and almost nobody owns at scale. The caveat carries over from DCD's reporting: engineering reports flag major refurbishment needs and less spare utility power than assumed at some sites. The close is expected by end of Q3 — that is this month.

Deal specs. Sponsor: I Squared Capital (up to $1B committed); Saragon opco; seller Cogent Communications · Site: 10 facilities in 9 metros — Chicago, Atlanta, Phoenix, LA, Kansas City, Baltimore, Houston, Nashville, Stockton — urban infill, mostly within city limits · Footprint: 259 ksf total (~26 ksf avg/site) · Load: ~53 MW installed (~205 W/sf across the portfolio) · Lease: fee-simple owned; platform to sell retail/enterprise/wholesale colo · Tenant credit: PE-backed platform; target tenants AI inference, CDN, enterprise · Deal value: $225M portfolio (~$4.25M/MW, $869/sf) + up to $1B platform commitment; close expected Q3 2026 · Source: DCD.

Four More Filings on FM 535: Another $2.8 Billion, Thirteen Miles From Austin

Four new Texas TABS filings landed for Cedar Creek in unincorporated Bastrop County, roughly 13 miles southeast of Austin's city limits: two 577 ksf single-story buildings at 6543 FM 535 at $700 million each (construction October 2026 to December 2028), and two 730 ksf buildings at 6682 FM 535, also $700 million each (September 2026 to March 2029). The filings aren't officially named, but the naming convention — EDCAUS31/32 and EDCAUS13/14 — and the land records point at EdgeConneX, whose Bastrop position could exceed a dozen buildings on 1,500-plus acres, with at least part of the campus leased to CoreWeave.

This is the build-to-suit cost tape for inner-ring Austin: $1,213 per square foot on the 577 ksf boxes and $959 on the 730s, filed value against shell-plus-fit. For density, the campus comp is AUS01 at 96 MW over 920 ksf — about 104 W/sf, a wholesale number, roughly half Saragon's urban-infill 205. Two campuses, one week, and the spread between them is the whole inference-real-estate market in two data points.

Deal specs. Sponsor: EdgeConneX (developer, per filing convention); CoreWeave (neocloud tenant on part of campus) · Site: Cedar Creek, unincorporated Bastrop County, TX, ~13 mi SE of Austin city limits · Footprint: 2× 577 ksf + 2× 730 ksf = 2,614 ksf filed this week · Load: n/d for new buildings; campus comp AUS01 = 96 MW / 920 ksf (~104 W/sf) · Lease: build-to-suit/wholesale; CoreWeave terms n/d · Tenant credit: neocloud · Deal value: $2.8B filed construction value ($1,213/sf and $959/sf) · Source: DCD.

A Town of 2,000 Signs a $13.7 Billion GPU Contract

Rum Group — the company formerly known as Rumble, post its Northern Data acquisition — disclosed a six-year GPU capacity and services agreement worth up to $13.7 billion with an unnamed "US-based third-party cloud customer" at its under-construction campus in Maysville, Georgia, population roughly 2,000, an hour northeast of Atlanta. The campus runs 120 MW initially, expanding to 180 MW, with an operational target of Q1 2027. This one is over our size line, and it's here for one reason: the contract structure is a benchmark that smaller GPU-colo deals will price off. Payment comes in three tranches, with tranche three contingent on the customer approving the delivery schedule, plus warrants for 50.81 million Class A shares at a penny, vesting with purchase volume. Take-or-pay-adjacent revenue with an equity kicker riding on volume — expect to see this template again at 20 and 40 MW.

The run-rate math is the part to underwrite carefully: $13.7 billion over six years is about $2.28 billion a year, which on 120 to 180 MW works out to somewhere between $12.7M and $19M per MW per year — GPU services pricing, not rent. Against that, Rum Group posted a $79.1 million net loss on $40.4 million of revenue in Q2. The gap between the contract and the operator's current P&L is the credit story, and the tranche structure is how the customer priced it.

Deal specs. Sponsor: Rum Group (operator, via its Quake AI cloud); unnamed US cloud customer writing the check · Site: Maysville, GA, at the town's edge, ~60 mi NE of Atlanta · Footprint: n/d · Load: 120 MW initial, expanding to 180 MW · Lease: 6-yr GPU capacity/services agreement, three tranches (tranche 3 conditional on delivery-schedule approval), warrants for 50.81M shares at $0.01 tied to volume · Tenant credit: n/d (unnamed) · Deal value: up to $13.7B (~$2.28B/yr run-rate) · Source: DCD.

Kentucky Draws the Line at 75 Megawatts — and 1,500 Watts a Foot

In Hopkinsville, Kentucky, about 70 miles northwest of Nashville, North Campbell Land Co. — a Sphere 3D subsidiary since June — wants to convert its 15 MW Bitcoin mine at the Hopkinsville Electric System's Holland Substation into AI/HPC and build a second 50 MW facility elsewhere in the city, on TVA power, with a new substation possibly ready in six to twelve months. A 65 MW crypto-pivot in a secondary metro is a familiar story. What's new is the city's response.

Hopkinsville's draft ordinance would cap "large-scale" data centers at under 75 MW and under 50,000 square feet, with 1,000-foot residential setbacks — and flatly prohibit anything bigger as "hyperscale." Run that ratio: 75 MW over 50 ksf is a regulatory density line at 1,500 W/sf, drawn by a city council rather than a mechanical engineer, and almost certainly by accident. Whatever the intent, the effect is a template: a small city defining exactly how much data center it will absorb, in megawatts and square feet, before the word hyperscale becomes a prohibition. Other councils will copy the numbers without re-deriving them. Watch where 75 and 50,000 show up next.

Deal specs. Sponsor: North Campbell Land Co. (wholly owned by Sphere 3D; ~53 MW operating across IA/KY/TN) · Site: Hopkinsville, KY, within city limits at HES Holland Substation; second site elsewhere in the city, undisclosed · Footprint: ~22 modular units at the existing site; sf n/d · Load: 15 MW conversion + 50 MW new build = 65 MW planned · Lease: owner-operated; curtailable-load arrangement with TVA; no AI/HPC customers announced · Tenant credit: crypto-pivot, public microcap · Deal value: n/d · Source: DCD.

What to Watch Next Week

September 21 — the federal courts go colo shopping. The Administrative Office of the US Courts has an RFI out on sam.gov for two geographically diverse enterprise colocation sites; the incumbent contract (Digital Realty El Segundo, Csquare Ashburn) runs to July 2029, the new term goes to at least 2032, and the office prefers one location near Washington, DC. Responses due September 21.

By September 30 — the Saragon close. The I Squared/Cogent ten-site portfolio is expected to close in Q3, which is now. Also watch Cogent's remaining Sprint sites — multiple parties reportedly in diligence, some for single buildings.

September — shovels at Cedar Creek. The EDCAUS13/14 filings show construction starting this month, EDCAUS31/32 in October. Watch Bastrop County permits for the first MW disclosures on the new buildings.

Date TBD — Hopkinsville's second hearing. Community & Development Services holds a second public hearing on the 75 MW / 50 ksf ordinance before a council vote. The numbers that survive that hearing are the ones other small cities will copy.

Q4 setup — Rum Group tranche three. The Maysville contract's third tranche hinges on customer approval of the delivery schedule; the campus targets Q1 2027 operations. Customer identity may surface in future SEC filings.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"The Only Meaningful Remedy Remaining": Three Judges Recommend Killing the Line, and ERCOT Concedes April Is Gone

Thursday, August 20 was a busy day in Austin. At 1:52 in the afternoon, three administrative law judges filed a Proposal for Decision recommending that the Public Utility Commission deny Oncor and LCRA Transmission Services' applications for two segments of the Permian import path — not on routing, not on cost, on need. Earlier the same day, at the Commission's open meeting, ERCOT collected the good cause exceptions it had asked for on the missed Batch Zero deadline, and then told commissioners the study will not be finished by April 9, 2027, and that it does not yet know what date replaces it.

Texas spent three years arguing about how quickly it could say yes. This week it worked through the various ways it can say wait. The practical effect is that a position in the queue is worth less than it was on August 1 and an energized meter is worth considerably more, and the market has already started quoting the spread.

"Still Working on What That New Timeline Might Be"

The procedural part went as scripted. ERCOT filed on August 10 in Project No. 59142 seeking good cause exceptions to three Planning Guide obligations — the missed August 7 Batch Zero classification deadline and the August 1 and November 1 quarterly stability assessments. On August 20 the Commission granted all three and authorized conditional Batch Zero classifications targeting August 31. I noted two weeks ago that ERCOT had asked and the Commission had not yet granted anything, and that this happens August 20. It happened August 20.

The unscripted part came next. Chad Seely, ERCOT's general counsel and chief compliance officer, told commissioners the Batch Zero study will not be complete by its April 9, 2027 deadline and that ERCOT is, as Community Impact reported it, "still working on what that new timeline might be." Every term sheet, seller note and construction-loan covenant written in Texas this year against a Batch Zero project assumed that date. It is gone, and nothing has replaced it.

What ERCOT did commit to is a calendar for the audit itself. Requests for information go out to provisionally qualified large loads from the end of August into early September, with further rounds in October and November. The Eligibility Verification Report and the Community Impact Review Report get filed December 10, with Commission discussion at the December 17 open meeting. The cohort is roughly 250 to 300 projects at 75 MW or larger, most of them data centers, drawn from a large-load interconnection queue Governor Abbott's August 3 directive put at 474 GW and about 90% data centers. That supersedes the 438,000 MW figure ERCOT published in June and this newsletter has been using since; the queue grew 36 GW in ten weeks while everyone was arguing about whether to study it.

The number that actually moves money is smaller. Seely told the Commission that 17 large loads representing about 6.6 GW of peak demand have cleared every ERCOT gate except one: approval to energize. They are not classified, not verified, not audited. They are simply finished with everything else. Utility Dive has the exchange. BNEF put roughly 49.8 GW of national pipeline at delay risk from the pause. Both numbers are real. Only one of them has a substation attached.

"The Only Meaningful Remedy Remaining"

Administrative law judges Linda Brite, Linda J. Burgess and Dee Marlo Chico spent 100-odd pages on the Bell County East–Big Hill and Big Hill–Sand Lake 765-kV applications and arrived at a recommendation nobody at Oncor wanted to read. Conclusion of Law 14 recommends denial of both projects because the applicants failed to prove need. Conclusion of Law 15 recommends denial of Bell County East–Big Hill on notice grounds as well. This is a Proposal for Decision remanded to the Commission, not a final order — the commissioners can adopt it, modify it, or throw it out. But the need case for the center import path has now failed once, on the record, in writing.

The notice arithmetic is worth reading slowly. Oncor and LCRA TSC sent 2,809 invitations to the June 2025 pre-filing public meetings. Then roughly 400 miles of new route links went into the project. When the applications were filed, notice went to about 4,200 landowners, mailed on or after March 26, 2026 — meaning some 1,400 people first learned they were affected when the paperwork arrived, months after the meetings where community input was supposed to happen. The judges wrote that denial was "the only meaningful remedy remaining." Nine words, page 45.

The need finding is the one that travels. The ALJs credited intervenor testimony cataloguing 37 announced gas generation projects in the Permian, West Texas and the Panhandle-Northwest totaling 39.467 GW as of May 13, 2026, and found the 2022 oil-and-gas electrification forecast underpinning Import Path 2 rested on corporate pledges rather than committed load. This newsletter ran the wires-versus-pipes numbers three weeks ago and concluded the case was closer than the transmission planning process treats it. Three administrative law judges have now written a version of the same thing into a docket.

The Commission moved the next day. On August 21 Chairman Gleeson and Commissioners Jackson and Hjaltman — Rhode and Johnson absent — consolidated the Longshore Switch–Drill Hole Switch and Dinosaur–Longshore dockets under PURA §37.0541, solely on the issue of need. That is Gleeson trying to answer the need question once, cleanly, before the 90th Legislature takes the pen away from him. The same morning, a statement signed by 31 members of the Texas House landed in Docket 59029 asking the Commission to deny all five pending 765-kV certificates. Oncor's counsel told the Commission the governing statute "is not a study bill" and "demands action," as reported by Texas Scorecard — a reading of HB 5066 that both Gleeson and the bill's author have publicly disputed.

Three of those dockets are on today's open meeting agenda, which convened at 9:30 this morning: 59029, 59315, and 59336, the AEP Texas and CPS Howard–Solstice line, which runs into a statutory deadline this weekend. The meeting was underway at press time.

Six August Records, No Conservation Appeal

On August 18, Bloomberg reported that ERCOT expected peak demand to exceed the all-time record of 91,089 MW every day from August 20 through August 24, with the forecaster Atmospheric G2 projecting wind output down as much as 5 GW by that Friday. Five consecutive all-time records, into a wind sag, in August. It was the setup for a bad week.

The record never fell. ERCOT's preliminary numbers show six straight daily August records from August 15 through August 20, topping out at 90,353 MW on Thursday the 20th, and then a new all-time weekend high of 90,411 MW on Sunday the 23rd. The July 22 mark held by 678 MW. There was no conservation appeal, no weather watch, no emergency notice. ERCOT published no news releases at all in August, which for a grid operator is its own kind of statement.

Two caveats on the figures. Every August number carries ERCOT's asterisk and is unofficial until settlement, and the July 22 record is drifting the wrong way for anyone quoting it: settlement data already puts that hour at 91,133.7 MW on an integrated hourly basis. Use 91,089 as preliminary or don't use it. For scale, the pre-2026 official record was 85,508 MW, set August 10, 2023. Texas is carrying about 6.5% more peak than it was three summers ago and doing it with more than 45 GW of solar and a battery fleet heading for 27 GW by year end.

The summer reliability question, the one that has driven a decade of Texas energy politics, quietly got answered in the affirmative this month. The tight window has moved off the August afternoon. What is left is winter, and winter is a different fleet problem with a different answer.

Nine Hours, and No Authority Over Community Impact

The day before all of it, the House Committee on State Affairs, chaired by Ken King of Canadian, sat for nine hours in JHR 140 on data center development and the 765-kV approval process, with two overflow rooms open. ERCOT President and CEO Pablo Vegas said the audit should conclude around December and acknowledged that some Batch Zero projects will drop out rather than sit through it.

The admission that matters came from the regulators themselves: PUCT and ERCOT have no explicit statutory authority over "community impact" and will rely on voluntary attestations from developers. So the most politically potent piece of the Governor's directive is a survey ERCOT cannot compel and cannot verify, covering facilities that in many cases sit below the Batch Zero threshold entirely. That is not a regulatory process. That is an evidence file, and every answer a developer gives this fall is an exhibit next spring.

Two other things got said out loud. Representative Drew Darby of San Angelo, on the 180-day certificate window that has been driving the whole transmission calendar: it "came from" the Permian Basin Reliability Plan, "not y'all deciding that we've got to run lines all the way across the state," and "I think we need to relook at that." And Adrian Rodriguez, president and chief operating officer of AEP Texas, on what delay actually costs: the 765-kV equipment order book is national, PJM and MISO are buying into the same slots, and Texas can lose its place in line. Transformers do not care which state's political process is having a moment.

$25 Million a Megawatt, If the Meter Already Spins

Which brings us to the price. IREN reported FY26 results on August 27: revenue of $707.0 million against $501.0 million a year earlier, with AI Cloud Services at $128.8 million and bitcoin mining at $578.2 million. In the fourth quarter AI Cloud finally passed mining, $70.5 million to $66.7 million. The company also booked a net loss of $702.6 million including $638.8 million of non-cash impairments, holds $5.90 billion of cash plus $1.72 billion restricted against $7.59 billion of debt, and told the call it plans $25 to $30 billion of capital expenditure in FY27.

Buried in that release is the cleanest price signal Texas has produced this year. IREN says recent three-year contracts are generating more than $20 million of revenue per critical IT megawatt, with roughly a two-year payback, and that active discussions are running near $25 million per megawatt on three-to-five-year terms, with customer prepayments covering 45 to 55% of the associated GPU capital. On August 13 Microsoft accepted Horizon 1 at Childress, the first of four 50 MW critical-load phases under a five-year contract worth about $9.7 billion signed last November. Phases two through four are targeted for the fourth quarter.

Set that against the other half of the state. Cipher, CleanSpark and Core Scientific are carrying gigawatts of Texas capacity whose value now depends on an audit that lost its deadline last week, and the sell side has been marking those positions down since the pause. Same state, same commodity, same regulator. The only variable is whether the meter is already spinning.

The constraint in Texas was never electrons. Everyone spent a decade planning for a shortage of generation and got a grid that took six straight August records without raising its voice. The shortage that showed up instead is permission, and permission is now the thing with a price.

What to Watch Next Week

Today's open meeting. Dockets 59029, 59315 and 59336 were all posted for discussion and possible action this morning. The Howard–Solstice application runs into its statutory deadline this weekend, which means the Commission either acts on it or explains why it did not.

ERCOT's Batch Zero RFIs. They go out from the end of this month into early September. The first real read on Vegas's prediction that projects will drop out is how many of the 250 to 300 respond, and how many quietly do not.

Exceptions to the Bell County East–Big Hill PFD. Docket 59475 is not on today's agenda. Oncor and LCRA TSC will file exceptions, staff and intervenors will reply, and the Commission takes it up in September. Watch whether the commissioners engage the need finding or dispose of it on the notice defect, which would be the narrow way out.

Project No. 58484. The transmission cost recovery docket has a December 31 statutory deadline and a March draft that would move ERCOT off four coincident peaks toward more of them, impose minimum demand charges on contracted peak for 10 to 15 years, and — in the companion proceeding — eliminate interconnection cost allowances for large loads. Nobody is protesting it on the Capitol steps. It will move more dollars than the 765-kV fight.

December 10 and December 17. The verification and community impact reports, and the open meeting that takes them up. Between now and then, the only Texas megawatts with a firm price are the ones already energized.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Buy at $4.2M a Megawatt, Build at $5.9M, Rent at $1.5M a Year

Five transactions printed this week, and for once none of them needed a gigawatt to be interesting. A private equity platform bought ten metro boxes at $4.25 million a megawatt. Eleven banks committed $800 million against five suburban halls at $5.93 million a megawatt. A Nasdaq microcap papered a seller note that does not amortize until the utility shows up. And a grocery-store holding company with $900,000 in the bank asked its shareholders to approve a $425 million valuation built on a lease nobody has signed.

Put those side by side and the sub-75 MW market has, briefly, a legible price. Used capacity trades around $4 million a megawatt. New capacity gets built for about $6 million. The one rent figure anyone put on paper this week runs $60 to $76 million a year against 40 to 47 MW — call it $1.5 million per megawatt-year. Every deal below sits under 75 MW at the site level, and no exceptions were needed to fill the issue, which is itself the signal. The money that used to only move in gigawatt blocks is now buying 5 MW switch rooms in Stockton.

$869 a Foot for Sprint's Old Long-Haul Switch Rooms

I Squared Capital launched Saragon on Tuesday, and the disclosure that came with the launch is the most useful comp set printed this month. Ten facilities across nine markets — Chicago, Atlanta, Phoenix, Los Angeles, Kansas City, Baltimore, Houston, Nashville and Stockton — carrying 53 MW of installed capacity across 259,000 square feet. The portfolio came out of Cogent Fiber for $225 million in cash, a sale Cogent closed on June 29; the platform, the management team and the site-level numbers only surfaced with the August 19 launch release.

Do the division and you get $4.25 million per installed megawatt, or $869 a square foot, for an average site of 5.3 MW and 25,900 square feet. These are former Sprint long-haul switching sites, built in the 1980s and 1990s, sold to Cogent for a dollar in 2022. Their virtue was never the slab — it is the fiber that terminates in them and the fact that they are inside the metros rather than ninety minutes outside. At 205 watts per square foot the portfolio is not an AI building. It is an option on becoming one, and I Squared has put up to $1 billion behind converting it, which is roughly $19 million of dry powder per megawatt of seeded base. Steve Orlando, ex-Seaborn Networks, runs it out of Phoenix; Kevin Dalton, previously chief data center officer at Talen's Cumulus, is president.

The interesting part is who did not buy this. A hyperscaler would not take a fragmented ten-site retail colo portfolio at any price. A REIT would choke on the tenancy. It took an infrastructure fund willing to underwrite the retrofit spread between 205 W/sf and whatever liquid cooling can get these rooms to.

Deal specs. Sponsor: Saragon (I Squared Capital) · Seller: Cogent Fiber LLC · Site: 10 facilities, 9 metros — Chicago, Atlanta, Phoenix, Los Angeles, Kansas City, Baltimore, Houston, Nashville, Stockton; all inner-ring metro, individual addresses n/d · Footprint: 259 ksf colocation, ~25.9 ksf average per site · Load: 53 MW installed (~205 W/sf, ~5.3 MW average per site) · Structure: all-cash fee acquisition, closed June 29, platform disclosed August 19; up to $1B committed sponsor capital · Tenant credit: mixed retail, enterprise and wholesale colo tenancy; sponsor institutional · Deal value: $225M — $4.25M/MW, $869/sf · Source: DCD.

Eleven Banks, $800 Million, and Not One Signed Tenant

Flexential closed an $800 million dedicated development facility on August 18, upsized 60 percent from a $500 million target and oversubscribed by an eleven-bank syndicate with TD Securities as administrative agent and RBC and J.P. Morgan alongside as coordinating leads. It funds 135 MW across five sites, none of them larger than 36 MW: 36 MW under construction in Atlanta-Douglasville, 36 MW under construction in Portland-Hillsboro with a second 36 MW planned behind it, 22.5 MW under construction in Denver-Parker, and a 4.5 MW expansion bolted onto the existing Atlanta-Norcross site.

That is $5.93 million per committed megawatt, drawn from planning through delivery, against capacity that is not pre-leased. Banks financing spec construction at 20-to-36 MW scale in Douglasville and Hillsboro is a different risk posture than the one that existed eighteen months ago, and the syndicate list — Goldman, ING, SMBC, Bank of America, KeyBanc as joint leads, Flagstar, Citi and Investec on co-documentation — reads like the lender group for an asset class that has stopped being exotic.

The release does not disclose square footage, which would normally end the density question. It does not, because Douglas County published it. When commissioners approved a $19.3 million business personal property tax rebate for the Parker site on August 11 — 100 percent of the county's share over 35 years, against 16 jobs — the record put the building at 249,000 square feet at 15255 Compark Boulevard. Against 22.5 MW that is 90 watts per square foot. Flexential is financing enterprise colo, not inference halls, and the density says so plainly. Nothing wrong with that; it is simply a different product than the one the headlines are about, financed at the same per-megawatt number.

Deal specs. Sponsor: Flexential (GI Partners, Morgan Stanley Infrastructure Partners) · Site: five sites — Douglasville GA (~20 mi W of Atlanta), Hillsboro OR ×2 (~17 mi W of Portland), 15255 Compark Blvd in Douglas County CO marketed as Denver-Parker (~23 mi SE of downtown Denver), Norcross GA (~20 mi NE of Atlanta) · Footprint: 249 ksf at Parker; other four n/d · Load: 135 MW total — 36 / 36 / 36 / 22.5 / 4.5 MW by site. Parker computes to ~90 W/sf · Structure: $800M dedicated development credit facility, 11-bank syndicate, upsized 60% from $500M; tenor, coupon and advance rate n/d · Tenant credit: n/a — spec construction ahead of leasing · Comp: $5.93M per committed MW · Source: DCD.

A Seller Note That Does Not Amortize Until the Utility Shows Up

Duos Edge AI bought a data center at 8 Corporate Ridge Parkway in Columbus, Georgia, together with about 13.7 acres, for $30 million — $15 million cash and a $15 million two-year seller note — and the note is the part worth copying. It bears interest at 0% per annum, sits behind a first-lien security deed on the property, and is payable, in the filing's own words, "as additional power capacity of up to 15 MW is delivered to the property in 5 MW increments." The mechanics live in the 10-Q filed August 19, not the press release. The purchase closed after quarter end.

Read that again as a buyer standing in an interconnection queue. The seller is holding the power risk, in writing, on a small brick-and-mortar site. If the utility does not deliver the next 15 MW, the note does not come due. Anyone negotiating a sub-20 MW acquisition against a queue that will not commit to a date should have this structure on the desk, because it is the cheapest way anyone has priced that risk this year — zero coupon, and the trigger is energization rather than a calendar.

The building is being equipped to support 2,304 NVIDIA B300 GPUs. Management put the company's build cost at "under $6 million a megawatt" on the August 17 call, which brackets Flexential's committed number from the other side. One caution on the anchor tenancy: the July release characterized the counterparty as an investment-grade hyperscaler, while on the call management named Axe Compute, described as a neocloud AI infrastructure platform. Those are not the same credit, and the filings have not reconciled them. Treat the contracted-revenue figures circulating from the July release as unverified against the filings — the note terms above are what the 10-Q actually says.

Deal specs. Sponsor: Duos Edge AI (Duos Technologies Group, Nasdaq: DUOT) · Site: 8 Corporate Ridge Parkway, Columbus, Georgia, within Columbus/Muscogee County city limits; ~13.7 acres · Footprint: n/d — W/sf not computable · Load: path to 20 MW, via up to 15 MW of additional delivered capacity in 5 MW increments · Purchase: $30M — $15M cash plus a $15M two-year seller note at 0% per annum, secured by a first-lien security deed, payable only as capacity is delivered · Lease: anchor lease terms n/d in the filings; July release figures unreconciled · Tenant credit: unreconciled — "investment-grade hyperscaler" in July, named as neocloud Axe Compute on the August 17 call · Build cost: "under $6M a megawatt," per management · Source: DUOT 10-Q.

A $425 Million Valuation on a Lease Nobody Has Signed

Host Digital Infrastructure is taking a northeast Oklahoma data center public through Healthy Choice Wellness Corp, the NYSE American-listed owner of a Richmond grocery store and a Kansas natural foods chain. Host's unitholders take roughly 96 percent of the pro forma company, and the shareholder vote lands Thursday. The HCWC board put $425 million on Host Digital, derived from a discounted cash flow on the Oklahoma project alone, with no credit for pipeline.

Read the assumptions underneath that DCF, because they are unusually candid. A 15-year initial lease term. Year-one base rent of approximately $60 million to $76 million, based on 40 to 47 MW of critical IT load, increasing 3 percent annually thereafter. Total contract value over the initial term projected at $1.1 billion to $1.4 billion. Divide it out and the rent runs roughly $125 to $135 a kilowatt-month in year one, or about $1.5 million per megawatt-year — the only rent number anyone put on paper in this market this week, and a useful one.

Then read the sentence that follows the assumptions in the DEF 14A: the analysis rests on "the terms discussed between Host Digital and the prospective tenant, as reflected in the drafts of the lease agreement exchanged." Drafts. The lease is not executed, the load is an expression of interest in a range rather than a contracted number, and the tenant is unnamed. No fairness opinion was obtained; the board concluded one was not necessary "given current market conditions and sentiment around artificial intelligence infrastructure and data centers." That is a remarkable thing to write down.

The proxy also does not say where the building is. Northeast Oklahoma is the finest geographic granularity in the document — no county, no city, no parcel. And the shell carries substantial doubt about its ability to continue as a going concern, with $0.9 million of cash and negative $6.6 million of working capital at June 30. The rent math is sound. What sits under it is a draft.

Deal specs. Sponsor: Host Digital Infrastructure LLC, merging into Healthy Choice Wellness Corp (NYSE American: HCWC); Host holders take ~96% · Site: "northeast Oklahoma" — no city, county or parcel disclosed anywhere in the proxy · Footprint: n/d — W/sf not computable · Load: 40–47 MW of critical IT load, per the prospective tenant's indication of interest — not contracted · Lease: unexecuted. Drafts exchanged for a 15-yr initial term, $60–76M year-one base rent, 3% annual escalator; Host targets NNN with credit-enhanced counterparties · Tenant credit: unnamed prospective tenant, characterized as investment-grade in the DCF · Valuation: $425M, DCF on this project alone, no fairness opinion obtained · Rent comp: ~$125–135/kW-month year one; $1.1–1.4B projected over the initial term · Source: SEC DEF 14A.

Keel Handed Back Ten Megawatts to Keep Eighteen

Keel Infrastructure — Bitfarms until the rebrand — committed $128.7 million to Vertiv under a turnkey agreement for 18 MW on six acres in Moses Lake, Washington, and relinquished its option on an adjacent 10 MW to do it. That is $7.15 million per megawatt for equipment and EPC alone, before land and shell, and it is the highest per-megawatt number in this issue by a wide margin — which is what buying a turnkey delivery from a single vendor costs when you want the capacity commissioned rather than scheduled.

The give-back is the story. A developer with an option on 28 MW chose 18, on six acres, inside Moses Lake city limits and about twenty miles east of the Quincy hyperscale cluster. That is three megawatts an acre on Grant County PUD hydro, in a Columbia Basin market where the power is cheap and the queue is the constraint. The old bitcoin building came down — more than a thousand cubic yards of concrete removed — and the permit went in as "Grant Node Data Center." Mining at the site stopped on April 28.

No tenant. Keel is building this on spec while it talks to AI firms and GPU clouds, which puts it in the same posture as Flexential's Hillsboro halls and Saragon's retrofit thesis: capacity first, credit later. Portfolio PUE is guided at 1.15 to 1.35. Building square footage has not been specced, so there is no watts-per-square-foot to compute yet — which, on a six-acre site with 18 MW behind it, is the number to ask for the moment they publish it.

Deal specs. Sponsor: Keel Infrastructure (formerly Bitfarms); Vertiv turnkey EPC, Turner Construction permittee · Site: six acres within Moses Lake city limits, Grant County WA, ~20 mi E of the Quincy hyperscale cluster; permitted as "Grant Node Data Center" · Footprint: n/d — building not yet specced; W/sf not computable · Load: 18 MW, with an adjacent 10 MW option relinquished (~3.0 MW per acre) · Lease: none — owner-developer spec build, commercial talks underway with AI and GPU-cloud operators · Power: Grant County PUD hydro; portfolio PUE guided 1.15–1.35 · Deal value: $128.7M Vertiv commitment — ~$7.15M/MW, equipment and EPC only · Source: Data Center Frontier.

What to Watch Next Week

Healthy Choice Wellness shareholders vote Thursday, August 27. If it passes, a northeast Oklahoma building with an unnamed tenant and an unsigned lease becomes a $425 million public company. Two things to watch in the post-close disclosure: whether the site location gets named, and whether the lease actually executes on the terms the DCF assumed.

Statesboro, Georgia still owes itself a special use permit. The city council rezoned 26.5 acres at 6539 Burkhalter Road on August 18, three to two, with Mayor Jonathan McCollar breaking the tie twice — once to defeat a motion to deny, once to approve. But the June technological facilities ordinance requires a separate SUP back before council before anything gets built. The concept plan is 230,000 square feet across two stories; the developers have applied to Georgia Power for 99 MW, which they describe as the maximum the adjacent transmission will carry. That is 430 watts per square foot on a building with no tenant — more than double Saragon's portfolio and nearly five times Flexential's Parker hall. Spec-zoned AI density, entitled by tiebreaker.

Kearney, Nebraska city council takes up Project Horizon on September 8. The planning commission recommended a conditional use permit unanimously on August 21 for the Starwood Digital Ventures and MARA partnership at Tech oNE Crossing. Phase 1 runs entirely on an existing crypto mine's 100 MW — same interconnect, same feeder, new building — with 368 MW at full buildout. The city manager projects municipal electricity revenue going from about $2 million a year to $11–13 million. Every small-city power director in the country is about to be shown that slide.

Hanover County supervisors have the last word on Iron Horse. The planning commission backed WestDulles Properties five to two on August 20 for 78 acres off Route 54 near Ashland, after the applicant cut buildable area from 39 acres to 28, dropped height from 110 feet to 75, and went closed-loop the night of the hearing. Supervisors denied a prior version in 2024. No load figure is in the record, and a noise study had not been performed at the time of the vote.

Raeden v. City of Gibraltar is the moratorium test case. The developer filed August 17 over Michigan's Downriver city adopting a total data center prohibition on March 9, weeks after Raeden submitted its application to convert the former McLouth Steel plant at 27800 W. Jefferson to 100 MW of inference capacity. The claim is that the Michigan Zoning Enabling Act forbids total exclusion of a lawful use. With moratoria now live in Tulare County, Spokane County, Alamance, Kalamazoo, Yadkin and Nye, a ruling here travels.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"A Slap in the Face to the Legislative Branch": PUCT Votes on 765kV Lines Nobody in Austin Says They Approved

For six months the story in Texas transmission has been ERCOT and the transmission and distribution utilities racing to keep up with an interconnection queue growing faster than anyone can classify it. This week the story flipped. Lawmakers who wrote a narrow regional-reliability bill in 2023 are now telling the Public Utility Commission they never authorized what got built on top of it, a state senator is calling for wholesale denial of pending applications, and a sitting PUCT chairman has admitted, on the record, that the Legislature never took an explicit vote. Meanwhile capital kept moving regardless: an $860 million gas plant changed hands, a gas-plus-nuclear hybrid near Victoria cleared its next gate, and a Bitcoin miner's Texas pivot ran straight into the audit process the governor ordered three weeks ago.

Call it the week Austin stopped watching the grid and started refereeing it.

"A Slap in the Face to the Legislative Branch"

PUCT commissioners were scheduled to vote today, August 21, on two segments of the 765-kV Strategic Transmission Expansion Plan's Permian buildout: Dinosaur–Longshore, filed under Docket 59315 on February 19 with a statutory 180-day deadline that expired August 18, and Longshore Switch–Drill Hole Switch, filed separately under Docket 59029 and abated back in June pending the outcome of the Dinosaur–Longshore case. Together the two segments are one piece of a project Oncor and ERCOT have described as three lines, five segments, and more than 1,200 miles, with lifetime ratepayer costs approaching $100 billion.

Administrative law judges recommended approval on July 24 — but not of Oncor's preferred route. They picked a hybrid alignment, Route 559, instead. Worse for Oncor: the same judges found the company failed to notify roughly 1,650 landowners within 520 feet of route segments that were added or modified after the initial public meetings. Oncor's fix — more than 4,200 written notices sent after the fact — didn't cure the defect, according to the ruling.

That's the backdrop for a legislative revolt that's been building since a 15-hour Senate Business and Commerce Committee hearing on July 29. Lt. Gov. Dan Patrick backed Sen. Charles Schwertner's call for PUCT to deny every pending 765-kV application until landowner concerns are addressed. State Reps. Brad Buckley and Shelby Slawson argue PUCT, ERCOT, and Oncor stretched a narrow 2023 regional-reliability bill, HB 5066, into what amounts to an unauthorized statewide transmission plan. Buckley didn't hedge: "The contention that House Bill 5066 authorized what is being proposed is a slap in the face to the legislative branch and a rogue interpretation by entities that seek profit and guaranteed returns on investment over honest interpretation of state law." PUCT Chairman Thomas Gleeson has more or less conceded the point — telling a Senate committee in July that lawmakers never explicitly voted to approve the buildout, even as the commission keeps processing dockets one by one.

Two days before the vote, the Texas House State Affairs Committee ran its own six-hour-plus hearing on data center costs. The Office of Public Utility Counsel's Benjamin Barkley used the platform to push a cost-allocation fix PUCT is separately already moving toward: shifting large-load billing from the current 4-coincident-peak model to a 12-coincident-peak model, which would stop big loads from dodging transmission costs by curtailing only during the handful of hours ERCOT currently measures. A Hill Country landowner named Beth Kunz put the other side plainly: "I retired to the Hill Country because of the land, because of the natural resources, because of the beauty and the dark skies, and all of that is currently threatened for a project that's just an extension port across the state."

LS Power Pays $860 Million for 606 Megawatts Constellation Had to Sell

LS Power Equity Advisors agreed on August 6 to buy the 606-megawatt Brazos Valley Energy Center, a gas-fired combined-cycle plant outside Houston, from Constellation Energy for roughly $860 million. The sale isn't optional for Constellation — it's the final piece of a divestiture package required to clear its acquisition of Calpine, and it closes the file on that regulatory obligation. LS Power expects the deal to close in the fourth quarter, pushing its national operating fleet to about 14,100 MW.

The math on why dispatchable Texas gas keeps changing hands: dealmakers have gone after ERCOT capacity roughly 58 times this year, more than California and New York combined. Nobody's buying gas plants in Texas because they expect the fuel mix to shift toward gas. They're buying them because gas is the only thing on the grid today that can plausibly be under contract to a data center by 2027.

Blue Energy and GE Vernova Move Their Nuclear-Gas Hybrid to the Next Gate

Blue Energy and GE Vernova Hitachi Nuclear Energy signed an agreement on August 13 to push their planned 2.5-gigawatt hybrid plant near Victoria into engineering, licensing, and safety-analysis work. The design pairs GE Vernova's 7HA.02 gas turbines with GE Hitachi's BWRX-300 small modular reactors, built in two phases: Phase 1, targeted for 2030, puts roughly 1 GW of gas turbine capacity onto a nearby data center; Phase 2, targeted for 2032, adds up to five BWRX-300 units and another 1.5 GW of nuclear capacity on the same site. A final investment decision is targeted for 2027.

It's a hedge, not a bet on either technology. Gas gets the site energized on a timeline a hyperscaler can actually plan around. Nuclear, five years later, gets it off the fuel-cost treadmill entirely — assuming the SMRs ship on schedule, which is its own running story in this newsletter.

Cipher's Cotulla Bet Runs Into the Audit It Was Supposed to Survive

Cipher Digital — renamed from Cipher Mining after a February board vote, formalized publicly on its May earnings call — reported second-quarter results on August 4 that made the rebrand look premature. Revenue came in at $24.8 million, down from $34.8 million in the first quarter; the loss per share was $0.65 against a consensus estimate of $0.23. The stock dropped 15.6% that day.

The timing wasn't a coincidence. Governor Abbott's directive ordering ERCOT to audit large-load interconnections landed August 3 — one day before Cipher's earnings call. Management told analysts the Batch Zero classification answer they'd expected in early August "would not arrive," and that new timing was too hard to predict. ERCOT has since filed three good-cause exception requests with PUCT seeking relief from its own Batch Zero deadlines, and PUCT considered them at its August 20 open meeting. State officials have told PUCT the audit itself will cover 250 to 300 projects representing roughly 200 GW of future demand — more than twice ERCOT's own peak demand record.

Cipher's smaller Reveille site in Cotulla — 70 MW scalable to 200 MW, bought for $2.5 million in 2024, energization targeted for 2027 — is now caught in the same slowdown, and it's running into local friction on top of it. Cotulla's city attorney warned councilors this week that no one in city government has adequate experience negotiating with Cipher, and recommended the city hire outside help before signing anything. That's a small-town preview of exactly what the statewide audit is designed to catch: deals moving faster than the institutions reviewing them.

What to Watch Next Week

The PUCT vote itself. Commissioners hadn't ruled on Dinosaur–Longshore or Longshore–Drill Hole as of this writing. Watch for whether they follow the administrative law judges' Route 559 recommendation or side with Oncor's original alignment — and whether the landowner-notice defect delays a decision on Longshore–Drill Hole specifically.

ERCOT's good-cause exception requests. PUCT's ruling on the Batch Zero deadline relief ERCOT asked for determines how much runway the audit actually gets before large loads start missing contractual milestones.

Cipher's next interconnection update. If Reveille's classification slips into the fourth quarter, that's the clearest signal yet of how much the audit is actually slowing individual projects versus just adding paperwork.

LS Power's regulatory clock on Brazos Valley. A fourth-quarter close assumes no antitrust friction. Watch for the next Hart-Scott-Rodino filing update.

The next STEP Permian segment. Bell County East–Big Hill is still working through the SOAH process behind Dinosaur–Longshore. If today's vote goes badly for Oncor, expect the company to adjust its approach before that one reaches a hearing.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

Wires or Pipes: Moving 7.6 Gigawatts 100 Miles, Two Ways

Here is the question, stripped of everything else. You have a gas field. You have a data center 100 miles away that wants 7.6 gigawatts. You can build a power plant at the gas field and run a transmission line to the data center, or you can build a pipeline to the data center and put the power plant there. Same gas, same load, same 100 miles. Which one do you build?

I have watched this argument happen in conference rooms for ten years and I have never once seen anybody do the arithmetic on a whiteboard. It gets settled by whoever in the room has done more of one than the other. So I did the arithmetic. The answer is not what most grid people assume, it is not what most pipeline people claim either, and the reason it comes out the way it does has almost nothing to do with thermodynamics.

Setting the Two Cases So They Are Actually the Same Case

Most published comparisons of pipes against wires are garbage, and they are garbage for one specific reason: they compare a thermal megawatt-hour against an electrical megawatt-hour and call it a result. The most-cited paper in this space, DeSantis et al. in iScience, concludes that electric transmission costs "about eleven times higher than for natural gas pipelines" per delivered MWh. That number gets quoted constantly. Read the methods and the gas side is normalized on lower heating value, meaning it is being credited for energy that has not been through a turbine yet. It is comparing crude oil to gasoline.

So let us build the two cases properly.

Case A, the wire. A combined cycle plant at the gas field. 100 miles of 765 kV single-circuit line. Data center at the far end. ERCOT specifies its new 765 kV lines at normal and emergency ratings of at least 7,603 MVA, six bundled Tern conductors, so that is the number we size to.

Case B, the pipe. 100 miles of 30-inch pipeline. The same combined cycle plant, sited at the data center instead. Running Panhandle B at 1,440 psig discharge and 1,000 psig suction with compressor stations 75 miles apart, a 30-inch line moves about 0.99 Bcf/d. At 1,030 Btu per cubic foot that is 12,464 MW thermal, and at a modern H-class heat rate of roughly 5,930 Btu/kWh on a higher heating value basis, it supports 7,172 MW electric. Within five percent of the 765 kV circuit. That is the apples-to-apples pair, and I have never seen anybody publish it: one 765 kV circuit equals one 30-inch pipeline.

Notice what just dropped out of the comparison. Both cases build the same power plant. Same turbines, same capex, same heat rate. It sits at a different end of the route, and that is all. Which means the plant cancels, and what we are actually pricing is the transport layer. Good. That is the only honest way to run this.

The Efficiency Argument Is a Trap, and Almost Everyone Falls In

The reflex objection to pipelines is that you lose 43 percent of the energy converting gas to electricity, so of course moving electrons is better. I made a version of that mistake myself last week and had to walk it back.

Here is the thing. That conversion loss happens in both cases. The pipe does not cause it. Burning gas causes it. If you generate at the field and wire it, you still paid the 43 percent, you just paid it 100 miles earlier.

So take one MMBtu at the wellhead and run it both ways.

Down the pipe: lose roughly 0.25 percent to compressor fuel over 100 miles, then convert at 57.5 percent. You deliver 0.574 MWh to the data center meter.

Down the wire: convert at 57.5 percent at the field, then lose about 1 percent on the line, using NREL's ReEDS planning assumption of one percent per 100 miles. You deliver 0.570 MWh.

The pipe wins by 0.76 percent. That is a rounding error, and anybody who tells you pipelines are dramatically more energy efficient is selling something. But it is not a loss, and the gap widens with distance because line losses accumulate faster than compression losses do. The filed tariffs bear this out: NGPL retains 3.13 percent to move gas from the Permian to its market zone, and that is roughly 1,300 miles.

Efficiency is a tie. Cross it off the list. The decision gets made somewhere else.

$846 Million of Wire, or About $500 Million of Steel

ERCOT's board endorsed the 765 kV STEP Eastern Backbone on December 9, 2025: $9.384 billion for 1,108.8 miles of new right of way, four new 765 kV substations, eleven transformers, in service somewhere between 2030 and 2032. That works out to $8.46 million per mile, all-in, stations included. So 100 miles of Case A is $846 million, or $111 per kilowatt of transfer capacity.

The pipe is harder to price honestly, because the number everyone reaches for is wrong for this job. Oil and Gas Journal's survey puts new construction at a record $12.1 million per mile for the twelve months ending June 2025. That is an interstate, FERC-jurisdictional sample of eighteen spreads, and it is roughly double what large-diameter pipe actually costs in Texas. Kinder Morgan's Permian Highway was $2.0 billion for 430 miles of 42-inch, which is $4.65 million per mile. Energy Transfer's Hugh Brinson is $2.7 billion for about 442 miles, or $6.11 million per mile. Scale those to 30-inch on a dollars-per-inch-mile basis and add back a floor for the costs that do not shrink with diameter, and 100 miles of 30-inch lands at roughly $400 to $600 million, or $56 to $84 per kilowatt.

Call it $500 million against $846 million. The pipe is about 40 percent cheaper for the same delivered gigawatts, and the spread is wider than that if the wire needs series compensation or a second circuit for contingency.

Then the Opex Flips, and the Pipe Loses That One

This is the part pipeline advocates skip, so let us not.

Transmission O&M is remarkably cheap. Connecticut's Siting Council pulled five years of FERC Form 1 data and got $14,481 per circuit-mile per year for overhead line. ITC Holdings, the only large pure-play transmission operator in the country, spent $116 million on O&M across roughly 16,000 circuit miles in 2025, which is $7,250 per mile. Call it $1.45 million a year for our 100 miles.

Gas transmission is not cheap. Williams' Transco spent $509 million on O&M across about 9,600 miles in 2025, which is $53,021 per mile per year. Northwest Pipeline runs $24,615. Boardwalk's gas segment runs $20,387. Weight the three and you get roughly $33,000 per mile, or $3.3 million a year for our 100 miles.

So the pipe costs about 2.3 times as much to run. You have rotating equipment. You have compressor stations every 40 to 100 miles with tens of thousands of horsepower in them, and 34 percent of reported gas transmission incidents happen at those stations rather than on the pipe itself. You have inline inspection, cathodic protection, and a seven-year reassessment clock in high consequence areas. A transmission line, once it is up, mostly just sits there and you cut trees under it.

Worth saying plainly, though: on both sides, maintenance is not where the money is. ITC bills load about $111,625 per circuit-mile per year and spends $7,250 of it on O&M. That is six and a half percent. Ninety-plus percent of what you pay for a wire is capital return, depreciation and taxes. Same story on the pipe. Anybody arguing this on maintenance labor is arguing about the tip.

2,424 Acres, or 606

Here is where it stops being close.

AEP's own landowner brochure lists typical right-of-way width at 200 feet for 765 kV and 150 feet for 345 kV. MISO's cost guide assumes 225 and 175. Take AEP's 200 feet. Over 100 miles that is 2,424 acres, encumbered permanently, and encumbered visibly. Nothing tall grows in it. Nothing gets built in it. It is there for sixty years.

Mountain Valley, a 42-inch line moving 2 Bcf/d, uses a 125-foot construction corridor that is reduced to an approximately 50-foot permanent right of way once the line is in the ground. Over 100 miles that is 606 acres, and after restoration you farm it, graze it, and drive over it. You just cannot build a house on it or plant an oak.

Four to one on permanent acreage. Normalize it per gigawatt and the wire encumbers 319 acres per GW per 100 miles against the pipe's 85. And that is before you count what the corridor looks like, which is not an engineering variable but is absolutely a permitting variable. The 765 kV structures are 130 to 190 feet tall. The pipe is invisible.

I want to flag one honest complication, because ERCOT's own filing raises it. The statewide 765 kV plan requires 434 more miles of new right of way than the 345 kV alternative, even though it needs about 1,400 fewer miles of upgrades on lines that already exist. Per gigawatt-mile, higher voltage always uses less land. At the plan level, in Texas, it currently uses more of it, because it is greenfield.

$2.73 Against $1.60, and a 2004 Study That Got There First

Put the capital, the O&M, the losses and the compressor fuel in one place. Twelve percent fixed charge rate on both sides, which covers return, depreciation and taxes. Same load factor on both sides so nobody is cheating.

At a 65 percent load factor, moving energy 100 miles costs $2.73 per MWh by wire and $1.31 to $1.90 per MWh by pipe. Call the pipe $1.60. That is a ratio of about 1.7 to 1. At 90 percent load factor, which is what a data center actually runs at, the wire is $2.07 and the pipe is $0.96 to $1.38, and the ratio widens to 1.8.

Now the part that made me trust the result. In March 2004 the Bonneville Power Administration and the Northwest Gas Association jointly published a study called "Comparing Pipes and Wires". Same experiment, different equipment: 100 miles of 500 kV serving a 1,500 MW plant at the source, against 100 miles of 20-inch pipe fueling that plant at the load. Their answer was $2.97 per MWh for the wire and $1.58 for the pipe at a 65 percent load factor, and their stated conclusion was that "natural gas pipelines average between 50 and 60 percent of the cost of electric power transmission per unit of energy delivered."

Two completely different sets of assets, twenty-two years apart, one built from 2026 ERCOT and Texas intrastate numbers and one from 2004 Pacific Northwest numbers, both landing on the pipe costing roughly 55 to 60 percent of the wire. And BPA is a transmission operator. They published a finding against their own book. In this business that is about as close to a clean result as you are going to get.

Their O&M split matched too, by the way: $519,000 a year for the line against $1,000,000 for the pipe. The gas side has always cost more to run and less to build.

If You Are Going to Build Wire, Build 765

None of the above is an argument against transmission. It is an argument against building the wrong transmission, and Texas is in the middle of deciding exactly that.

The step from 345 kV to 765 kV is not incremental. AEP puts it plainly: "A single 765 kV circuit carries up to six times the power of a 345 kV line" with "half the transmission losses of lower voltage systems." The underlying engineering, quoted in an Oak Ridge report, is that an uncompensated 765 kV line has a surge impedance loading around 2,400 MW against roughly 390 MW for a 345 kV line, and that "about six single-circuit, or three double-circuit, 345 kV lines would be required to achieve the load carrying ability of a single 765 kV line."

The distance number is the one that should stop you. Move 1,500 MW on a 765 kV line and the St. Clair curve says you can carry it reliably up to about 550 miles. Move the same 1,500 MW on a single-circuit 345 kV line and you get about 50 miles. Fifty. That is not a better wire, that is a different category of infrastructure.

ERCOT ran the losses on its own two plans and found the 765 kV build cuts statewide transmission losses by about 5 percent, between 540 and 577 GWh a year, which they describe as roughly a 128 MW thermal unit running at a 50 percent capacity factor. That is a power plant you never have to build, every year, forever, because you picked a higher voltage.

Scale, in units a person can hold. A Texas home uses about 13,150 kWh a year. One 765 kV circuit at a 60 percent load factor moves 40 TWh, which covers 3.0 million Texas homes. One new-build 345 kV circuit at ERCOT's 2,988 MVA spec covers 1.2 million. Houston has roughly 2.6 million households. One 765 kV line is metropolitan Houston in a single 200-foot corridor. To do that with 345 kV you are cutting six corridors at 150 feet each, which is 900 feet of encumbered land instead of 200.

So if you care about acreage, and about not putting steel through six sets of somebody's pasture, the 765 kV line is the environmentalist's answer and the 345 kV line is not. That is an odd sentence to write about the largest transmission structures ever built in Texas. It is still true.

What the Pipe Cannot Carry

Now the case against everything I just said, because it is a real case and it is the one that decides where this actually goes.

You cannot pipe sunlight. This is the whole argument in four words. Roughly 99 percent of net new US generating capacity in 2026 is solar, wind and storage. None of it has a molecule to ship. For any of that generation, the transport question has exactly one answer and it is a wire. The pipeline's cost advantage applies to a shrinking share of the fleet, even as gas keeps supplying about 40 percent of the energy.

A wire runs both directions and takes anything. Build 100 miles of 765 kV and it will carry gas-fired power today, wind at 2 a.m. in six years, and something nobody has invented in thirty. It shares reserves with everything else connected to it. NREL's Seams study put benefit-to-cost ratios as high as 2.9 on large interregional transmission, almost entirely from that sharing. A pipe is point to point and single commodity. It does one job.

The pipe carries stranding risk the wire does not. Interstate pipelines run at roughly 60 to 65 percent load factor and get paid anyway, because straight fixed-variable rate design puts fixed cost in the reservation charge. That transfers throughput risk to the shipper for the term of the contract. It does not eliminate the risk, it converts it into re-contracting risk at expiry. Transco alone carries $21 billion of gross plant against a 15 to 44 year depreciation schedule. If the load electrifies, that has nowhere to go.

And the plant that actually gets built at the load is usually not an H-class combined cycle. Every number in this piece assumes 5,930 Btu/kWh. Reciprocating engines and simple-cycle aeroderivatives, which is what most fast-deployment data center projects are actually installing because you can get them before 2031, run 7,750 to 8,760. At that heat rate the same 30-inch pipe supports 4.9 to 5.5 GW instead of 7.2, and the delivered cost per MWh goes up by a third. Speed-to-power is being bought with efficiency, and the pipe's advantage is partly spent on the way.

What It Means

The decision rule is not "pipes beat wires." It is narrower and more useful than that.

If the energy is gas, ship the molecule. Roughly 40 percent less capital, about 4 times less permanent land, a slight edge on losses, and no interconnection queue. You give back 2.3 times on O&M and you accept single-commodity risk. On a 100-mile haul to a firm 90 percent load, that trade is not close.

If the energy is not gas, there is no decision. Build the wire, and build it at 765 kV, because six times the transfer for one corridor and five percent lower statewide losses is the best trade available in transmission engineering right now.

What is actually happening in Texas is that we are doing the second thing for the first reason. About 38 gigawatts of behind-the-meter gas has been announced in this state while ERCOT plans a $33 billion, 2,468-mile 765 kV network whose certificates are not granted and whose in-service dates start in 2030. Meanwhile the postage-stamp transmission rate went from $30.95 per kW-year in 2013 to $68.55 in 2025, and every dollar of that build lands in it.

Nobody is choosing gas at the load because they ran this model. They are choosing it because the pipe can be in the ground before the wire has a route. The arithmetic just happens to agree with them.

Solid 8 on the nerd scale. I ran it three times.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Cost figures for the 30-inch pipeline case are scaled from named Texas intrastate projects on a dollars-per-inch-mile basis and are the author's estimate, not a quoted price; throughput is calculated from the Panhandle B equation at stated assumptions. Links go to primary sources wherever possible. Form your own view, and check my math.
Marco Elizondo

Marco Elizondo

Technical Analyst | Barrio Energy

Marco Elizondo spent five years at ERCOT in grid operations and transmission planning before joining Barrio Energy. He writes the engineering and unit economics underneath the headlines, and he will always show you the arithmetic.

← Back to Edge Cases

Eighty-Two Dollars a Foot in Oakland, Thirteen Sixty-Seven in Bristow

Six data center buildings changed hands or got entitled in the lower 48 in the last seven days, and every one of them is small — 3 MW to 55 MW, the band this newsletter exists to cover. Put their trade prices on one line and the range is absurd: $82 a square foot in downtown Oakland, $1,367 a square foot in Bristow, Virginia. Sixteen-and-a-half times, same asset class, same week, same country.

The variable isn't geography, and it isn't power. Oakland has 20 MW of entitled capacity in a building a quarter-mile from a BART station. Bristow is a 2001-vintage box on Linton Hall Road running 43.5 watts per square foot, which is a spec nobody would design today. Bristow has a signed ten-year lease with an investment-grade cloud provider. Oakland has fifteen tours and a broker. That is the whole difference, and this week the market put a number on it.

Below: the Digital Core REIT sponsor sale that priced a lease against a vacancy inside a single transaction, Behring's 81 percent markdown in Oakland, two identical $8.1 million net-lease trades two days apart, the densest small design of the week in Virginia Beach, and a neocloud that stopped renting cabinets and bought 49 percent of the landlord's project company instead.

Bristow at $1,367 a Foot, El Segundo at $769, Same Table, Same Day

Digital Core REIT — the SGX-listed vehicle Digital Realty sponsors and manages — agreed on August 12 to sell interests in three North American assets back to its sponsor for roughly $315.9 million gross, recycling the proceeds into Singapore and Osaka. Two of the three legs are in the lower 48, and between them they do something the tape almost never does cleanly: they price a stabilized lease and an empty building on the same day, against the same counterparty, under the same set of assumptions.

Bristow, Virginia — 8217 Linton Hall Road, 207,000 square feet, single-story, built in 2001, 9 MW — went at a 39 percent interest for $110.4 million. Gross that to 100 percent and the whole asset marks around $283 million: roughly $31.4 million per megawatt and about $1,367 per square foot. The building had just been re-let on a ten-year agreement to an unnamed investment-grade global cloud provider commencing December 1, backfilling a Fortune 50 software tenant that had been in place since 2005.

El Segundo — 200 North Nash Street, 113,606 square feet on four acres, built in 1976, a mile south of LAX — went at a 90 percent interest for $78.6 million. Gross that up and you get about $87.3 million, or ~$769 per square foot. That building has no tenant. Cyxtera's lease ran to 2033 until it was terminated early in the bankruptcy and the Brookfield sale.

Twice the price per foot for a building with a quarter the power density and twenty-five extra years on the clock. The lease is the asset. Everything else is a shell with a substation attached. Unitholder approval is still required and the sponsor is on both sides of the table, so read the mark accordingly — but the relative spread is the useful number, not the absolute one.

Deal specs. Sponsor: Digital Core REIT (seller) to Digital Realty (buyer/sponsor) · Site: 8217 Linton Hall Rd, unincorporated Prince William County, VA — ~4–5 mi SW of Manassas city limits · Footprint: 207 ksf single-story, built 2001 · Load: 9 MW (~43.5 W/sf — the floor of the week) · Lease: 10-yr to unnamed investment-grade global cloud provider, commencing Dec 1; escalator n/d · Deal value: $110.4M for 39%, implying ~$283M / ~$31.4M per MW / ~$1,367 per sf · Source: DCD.

Deal specs. Sponsor: Digital Core REIT (seller) to Digital Realty (buyer/sponsor) · Site: 200 N Nash St, within El Segundo city limits, CA — ~1 mi S of LAX · Footprint: 113.6 ksf two-story on 4 acres, built 1976 · Load: n/d · Lease: none — Cyxtera lease to 2033 terminated early in bankruptcy · Deal value: $78.6M for 90%, implying ~$87.3M / ~$769 per sf · Source: DCD.

Behring Paid $82 a Foot for a Building Berkeley Lab Used to Run Supercomputers In

The Oakland Scientific Facility at 415 20th Street housed Lawrence Berkeley National Laboratory's supercomputing operation for years. Hines bought it from the UC Regents in 2019 for $36 million on an office thesis. Behring Companies bought it from Hines in December 2025 for $6.8 million — an 81 percent markdown — and is now repositioning it as an AI inference facility, uprating the building from 4.5 MW to a 20 MW target with more than 20,000 square feet coming back as raised floor. The reposition surfaced publicly on August 11.

At $6.8 million against 83,000 square feet that is $81.93 per square foot, and against the 20 MW target it works out to roughly $340,000 per megawatt of shell-and-entitlement basis. Nothing in this window is remotely close on either measure. It is the cheapest option on inner-ring capacity anyone bought this year.

Two honest caveats. There is no tenant — Behring is speculative, with tours reported from robotics shops, research labs and cloud providers, and it is not decided between single- and multi-tenant. And the density number depends on how you count. Whole-building, 20 MW across 83,000 square feet is 241 W/sf. Quote it against the 20,000 square feet of raised floor and you get 1,000 W/sf, which is technically true and functionally marketing. Use the whole-building figure. It is the one that comps.

Deal specs. Sponsor: Behring Companies (marketed via Stak Space) · Site: 415 20th St, within Oakland city limits, CA — downtown/Uptown, ~0.2 mi from 19th St BART · Footprint: 83 ksf building, >20 ksf converting to raised floor · Load: 4.5 MW today, 20 MW target (~241 W/sf whole-building at target; 54 W/sf today) · Lease: none — speculative reposition, single- vs multi-tenant undecided · Deal value: $6.8M (Dec 2025, from Hines, who paid $36M in 2019) → $81.93/sf, ~$340k per target MW · Source: DCD.

Two Buildings, $8.1 Million Each, Two Days Apart, Same Seller Naming Convention

A Landmark Dividend affiliate bought the building housing Expedient's data center at 4777 Ironwood Drive in Franklin, Wisconsin on August 11 for $8.1 million. Two days earlier it closed on a T-Mobile-leased data center at 7025 AC Skinner Parkway in Jacksonville, Florida. Also $8.1 million.

The coincidence isn't the price. It's the sellers: both single-purpose entities using the identical RDC-[street number] [street name], LLC convention. That is a net-lease digital-infrastructure vehicle being taken out one asset at a time, and Landmark — a DigitalBridge portfolio company with ADIA holding roughly 40 percent — is the buyer on the other end of it. Expect more of these.

What the pair gives the market is two clean small single-tenant comps: $300 per square foot in Franklin against 27,000 square feet leased to a private operator, and $246 per square foot in Jacksonville against 32,945 square feet leased to investment-grade T-Mobile. The lower price per foot on the better credit is not a pricing error; it is 6,000 more square feet of building. Note also that Jacksonville reportedly traded at $10.5 million in 2022, which makes this a ~23 percent markdown in four years — though DCD has an open query on whether the 2022 buyer was StratCap or Gallatin Point. Don't underwrite off that comp until the chain of title resolves.

Deal specs. Sponsor: Landmark Dividend affiliate (DigitalBridge portfolio co.) from RDC-4777 Ironwood Drive, LLC · Site: 4777 Ironwood Dr, within Franklin city limits, WI (Milwaukee County) — ~13 mi SW of downtown Milwaukee, former Harley-Davidson site · Footprint: 27 ksf · Load: 3.0 MW generator capacity (~111 W/sf on generator, not critical IT — treat as a ceiling) · Lease: occupied by Expedient (private); term and escalator n/d · Deal value: $8.1M → $300/sf, $2.7M per generator MW · Source: BizTimes.

Deal specs. Sponsor: Landmark Dividend from Gallatin Point Capital via RDC-7025 AC Skinner Parkway LLC · Site: 7025 AC Skinner Pkwy, within consolidated Jacksonville/Duval city limits, FL — Southpoint/Deerwood, ~9 mi SE of downtown · Footprint: 32.9 ksf · Load: n/d · Lease: occupied by T-Mobile (investment grade); term and escalator n/d · Deal value: $8.1M → $245.9/sf; reportedly $10.5M in 2022, a ~23% four-year markdown · Source: DCD.

Virginia Beach Sold Nine Acres for $1.8 Million the Same Week It Debated a Moratorium

The Virginia Beach Development Authority agreed to sell nine acres in Corporate Landing Business Park to Globalinx for phase three of its subsea-cable-landing-station and carrier-neutral colocation campus. $1.8 million for the dirt, $65 million all-in, 85,000 square feet, 25 MW, roughly 40 permanent jobs. No anchor tenant disclosed and no timeline shared.

The number that matters: 25 MW across 85,000 square feet is 294 watts per square foot, the densest disclosed design in the window by a comfortable margin and nearly seven times the Bristow box. Cable-landing colo used to be a low-density business — you were selling proximity to the fiber, not the rack. It is now being specced like an inference hall. That is the quiet structural story of the week, and it is worth more to a developer than any of the trade prices above.

The city was weighing a one-year data center moratorium in the same stretch it approved the land sale, which is the current condition of the entitlement market almost everywhere — the door is closing and everyone with a shovel is trying to get through it. At $200,000 per acre and $2.6 million per megawatt all-in, Globalinx got through.

Deal specs. Sponsor: Globalinx (buyer) from Virginia Beach Development Authority (seller) · Site: Corporate Landing Business Park, within Virginia Beach city limits, VA — southern VB near Dam Neck, ~12 mi S of the oceanfront resort strip · Footprint: 85 ksf on 9 acres · Load: 25 MW (~294 W/sf — densest disclosed design of the week) · Lease: land sale, not a lease; no anchor tenant disclosed · Deal value: $1.8M land / $65M project → $200k per acre, $2.6M per MW, $765/sf all-in · Source: DCD.

Axe Compute Didn't Rent the Capacity. It Bought Into the Landlord.

On August 17 Duos Technologies executed five-year hosting service orders with neocloud Axe Compute covering roughly 55 MW of AI facility capacity — facility, not critical IT, and the release is explicit about that — worth more than $500 million in aggregate contractual base payments over the initial terms, with electricity billed separately and excluded. It builds on an existing 10 MW deployment at Duos' Columbus, Georgia campus.

The hosting order is ordinary. The attachment is not. Alongside it the two signed non-binding term sheets for Axe to take a 49 percent minority equity position in the project entities, Duos retaining majority. Duos frames it as non-dilutive project financing. Read it the other way and a distributed-inference operator just decided that renting capacity is a worse trade than owning half the SPV that holds it. If that structure travels — tenant as minority JV partner on the asset it occupies — it changes how every mid-size take-or-pay in this market gets underwritten, because your tenant's credit and your equity partner's credit become the same credit.

Four days earlier Duos signed a separate exclusive term sheet with 0Lat LLC for a structured true lease across all fifteen of its edge sites, 225 cabinets, 90-day mutual exclusivity running to roughly November 11. Term, escalator and pricing are all explicitly unset. That process is where a 15-site edge portfolio finally gets a cap rate, and it is the single thing on this desk's calendar most worth watching.

Deal specs. Sponsor: Duos Technologies Group (Nasdaq: DUOT) project entities · Tenant/co-investor: Axe Compute Inc. (Nasdaq: AGPU) — neocloud credit · Site: "multiple U.S. locations," explicitly undisclosed; builds on 10 MW at Duos' Columbus, GA campus; Duos footprint is TX and GA · Footprint: n/d · Load: ~55 MW facility capacity (density n/d — no sf disclosed) · Lease: 5-yr hosting service orders, reserved capacity, renewal and expansion rights, annual escalators confirmed but rate n/d; billing contingent on RFS testing and written acceptance. Separate non-binding term sheets for Axe to take 49% equity in the project SPVs · Deal value: >$500M base payments over initial 5-yr terms, excluding power → >$1.82M per MW-year on facility capacity · Source: GlobeNewswire.

What to Watch Next Week

The Duos–0Lat exclusivity clock. Ninety days from August 13, so roughly November 11. Confirmatory diligence includes site-level verification of Duos' invested capital, which is an unusual thing to write into a term sheet and tells you what the buyer is worried about. Structure, term and pricing all still to be set.

Hillsboro, Oregon, and the value of an application filed on time. STACK and Aligned both filed land-use applications hours before Hillsboro enacted a 120-day moratorium on August 12; STACK's 4 MW revision survives, Aligned's 36 MW PDX-02 does not. Entitlement scarcity in that submarket just became a pricing lever rather than a nuisance.

Pulaski County, Arkansas, August 25. Full Quorum Court vote on classifying large-scale data centers as heavy industrial requiring a conditional use permit, with 500-foot residential setbacks and noise caps. Watch the setback number — it is becoming the standard ask, and it prices acreage.

Palm Beach County, Florida, August 27. Public hearing and first vote on a temporary halt to large applications, following the 5–1 rejection of the $2 billion Project Tango. That denial was without prejudice, which leaves a door open.

Shawnee County, Kansas, noon on August 28. Compass Datacenters' conditional-use-permit resubmission deadline. The July 24 filing was ruled incomplete on August 4, after which commissioners voted 2–1 for a moratorium running through February 17, 2027. Miss the deadline and the moratorium catches the project.

One number to not get fooled by. The Riot–Anthropic contract straight-lines to $198.52 per kW per month. That is numerically identical to the $198.52 per square foot figure in the build-to-suit tape we ran last week. Different units, pure coincidence, and somebody is going to put them in the same spreadsheet.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"Already Fully Approved and Energized" — $9.1 Billion for 191 MW, and 8,766 MW Nobody Counted

Greg Abbott's August 3 letter did not stop a single data center from being built in Texas. What it did was reprice them. It sorted the market into two piles — megawatts that already hold an approved interconnection, and megawatts waiting on a verification and audit that ERCOT now tells the Commission "will take several months" — and then it let everyone work out which pile was worth more.

That took about a week. On Monday, Riot Platforms leased 191 megawatts at Rockdale for $9.1 billion, and the load-bearing phrase in the announcement was five words long. On Wednesday, IREN handed Microsoft a finished 50 MW at Childress. In between, ERCOT asked the Public Utility Commission for more time on three separate deadlines and, in the same filing, disclosed 8,766 megawatts of Texas data center and mining load that was never in Batch Zero to begin with. Nobody was counting it. It is still coming.

"Already Fully Approved and Energized"

Riot's August 10 filing describes a 20-year, 191 MW critical IT build-to-suit at Rockdale, Tier 3, running through June 2048. Total initial contract revenue is approximately $9.1 billion, or $16.1 billion if the tenant exercises both five-year extensions. Ninety-six IT megawatts land in December 2027; the full 191 by June 2028. Morgan Stanley is fronting a $573 million interim facility until an investment-grade credit backstop is finalized.

The tenant is identified in the filing only as "one of the world's leading frontier AI labs." Bloomberg reported it as Anthropic. Riot has not confirmed that, and I am not going to pretend it has.

What Riot did say, in CEO Jason Les's own quote, is the whole thesis of the week: the company's platform stands apart through "multi-gigawatt-scale power capacity that is already fully approved and energized, in-house data center development expertise, and the ability to engineer custom infrastructure." Two of those three are things a competitor can hire. The first one is now, functionally, unobtainable in Texas until the audit clears.

Run the arithmetic yourself, because it is worth seeing: $9.1 billion over 20 years is about $455 million a year, against 191 megawatts of critical IT. That is roughly $2.38 per critical IT watt per year, on a site where the interconnection was already done. Morgan Stanley took its price target to $43 from $36 the same week. It did not need a new thesis to do it — it needed a calendar.

The rest of the quarter was ugly and largely beside the point. Revenue was $174.2 million against $153.0 million a year ago, but Riot booked a net loss of $237.2 million and adjusted EBITDA of negative $69.7 million. Bitcoin mining revenue fell to $113.7 million from $140.9 million. Data center revenue went from nothing to $23.2 million. That is the transition, showing up in the line items exactly as advertised. Also disclosed: a non-binding LOI covering the full ~1 GW Corsicana campus, single tenant, unnamed. And the AMD lease from January now runs to 50 MW when Phase 4 lands in May 2027.

Two days later, IREN delivered Horizon 1 at Childress — 50 MW of critical IT, direct-to-chip liquid cooled, accepted by Microsoft, the first of four such deployments due in 2026 under a five-year, $9.7 billion contract signed last November. Same pattern. Existing Texas campus, existing power, finished product, paid for. The audit does not touch it.

ERCOT Is Aware of 258 Medium-Sized Loads

I wrote two weeks ago that ERCOT had missed its own August 7 classification deadline. Here is what actually happened next, because it is more interesting than the miss.

On August 10, ERCOT filed in PUCT Project No. 59142 requesting good cause exceptions to three Planning Guide obligations at once: the missed August 7 classification, the August 1 quarterly stability assessment, and the November 1 quarterly stability assessment. It received more than 200 dynamic data submissions and could not review them in time. It has temporarily paused Batch Zero, and it will refrain from granting energization approvals to large load data centers and crypto facilities until verification completes. Note the verbs: ERCOT asked. The Commission has not yet granted anything. That happens August 20.

The new number is on page seven. ERCOT is aware of 258 medium-sized loads — peak demand of at least 25 MW but less than 75 MW — seeking interconnection by 2032, representing 13,473 MW. Of those, approximately 157 are data centers or virtual currency mining facilities, representing 8,766 MW. Every one of them sits below the 75 MW Batch Zero threshold. None of them were in Batch Zero. ERCOT surfaced them from an earlier RFI tied to the 2026 Regional Transmission Plan, and it now intends to collect community impact information from all of them.

Which is the tell. The 474 gigawatts Abbott cited in his directive letter, roughly 90 percent of it data centers, was always the visible queue. Underneath it there is a second population sized deliberately to duck the threshold, and the state has just decided to look at that too. Eight-point-eight gigawatts is not a rounding error. It is more than half of what CenterPoint put into Batch Zero.

The collateral damage is stacked up behind it. ERCOT cannot begin the system-wide Batch Zero study in September as planned. It recommends delaying the Long-Term Load Forecast until final classification, which delays the 2026 Triennial Reliability Assessment results expected in November, which could delay the December Capacity, Demand and Reserves report. ERCOT is not asking the Commission to rule on any of that — it raised it "for the Commission's awareness," which is regulator for you should know this is on fire. And it has pointedly not asked to move the April 9, 2027 deadline for study results. The start slips; the finish does not. Somebody eats that compression, and it is not going to be ERCOT.

"If It Can't Get Met, It's Not Coming Online"

Into that, a genuinely useful counter-forecast. Ascend Analytics gave Utility Dive a market report on August 12 putting ERCOT's 2030 peak at about 120 GW. For context, ERCOT said in April that transmission service providers had reported 208 GW of 2030 load based on contracts and officer letters, and ERCOT's own adjusted forecast came in at 138 GW.

Ascend gets to 120 by assuming a 55.4% success rate for proposed loads, and its core finding is that more than 80% of new large loads seeking interconnection will not have matching generation online by 2030. "Even though that appetite is enormous, if it can't get met, it's not coming online," said Brent Nelson, Ascend's senior managing director of market intelligence. His colleague Robert LaFaso, director of market intelligence, put the constraint plainly: "The ability of the grid to add new generation is much, much smaller than the demand of queued large-load facilities."

This is the argument that has been missing from the queue fight. Everyone has been litigating whether the demand is real. Ascend's point is that the demand's reality is not the binding constraint — tier-one gas turbine slots, EPC crews, high-voltage equipment and permitting are. You can cull the queue or not cull the queue and you still cannot buy a turbine.

Vistra CEO Jim Burke, on the August 7 earnings call, would like it culled regardless: "I'd like to see the queues culled, at the end of the day." Vistra posted $1.767 billion of adjusted EBITDA, up about 30% year over year, and trimmed its ERCOT annual load growth outlook to 4%–6% from 5%–6%. Its 2.4 GW Comanche Peak starts delivering 1.2 GW to Amazon in 2027 under a 20-year PPA, which is to say Vistra is calling for a thinner queue from a position inside the part of it that already cleared. Everyone in Texas is now arguing their own book, and at least Burke does it out loud.

One number to keep straight while all this gets argued: ERCOT's all-time peak record stands at 91,089 MW, set July 22, 2026. That is the integrated hourly figure, not an instantaneous one, and it is still unofficial pending final settlement. The record it beat, 85,508 MW, took three years to fall.

"I Think It's a Mistake"

The most notable political event of the week was a Republican president criticizing a Republican governor's grid policy. In a Punchbowl News interview released August 7, Donald Trump said: "I saw Texas the other day sort of is against data centers." Then: "I think it's a mistake. And I'm not taking positions, I just think it's a mistake, because there are other communities that want it." And: "For Texas to say no to data centers is a mistake in the sense that it could be bigger than oil."

Abbott's office did not blink. Spokesperson Andrew Mahaleris cited ERCOT tracking a more than 500% increase in peak demand and closed with "Simply put, Texans must come first." He also produced the number that makes the audit hard to argue with: less than 10% of data centers responded to the state's requests to report their power and water usage. A separate survey tells the same story — the Texas Water Development Board has asked for monthly water data since 2020 from facilities using at least 10 million gallons a year, and fewer than one-fifth of 341 data centers reported in 2025, despite reporting being required by law.

Not one operator sided with Trump. The compliance announcements instead came in a queue of their own: QTS on August 6, Skybox and Digital Realty and MARA on August 7, Meta and OpenAI on August 10, Oracle and EdgeConneX and Stream on August 11, Google and CleanSpark and Core Scientific and Vantage on August 12, Microsoft and Hut 8 and Equinix on August 13, Amazon and Lancium and Cipher Digital today. Compass Datacenters founder and CEO Chris Crosby, who got there first with a Fortune op-ed, wanted exactly one thing from the state: "Just measure every developer by the same yardstick."

CenterPoint took the more interesting angle. On August 11, nine days before the Commission takes up the audit, the utility announced a Customer Savings Initiative projecting more than $5 billion in statewide customer savings over the next decade, driven by up to 14 new gigawatts of ERCOT-eligible base load and studied load. Chairman and CEO Jason Wells called it "a once-in-a-generation opportunity."

Read that as what it is: an affordability argument aimed at the exact political nerve Abbott is pressing. Large loads absorb fixed grid costs that residential customers currently carry. The 14 GW comes from CenterPoint's July 28 quarterly release, where it disclosed submitting over 17 GW into Batch Zero, of which roughly 14 GW is expected eligible — "more than a 65% increase from our current Houston Electric peak system demand of 21 gigawatts." The pitch is that the thing your neighbors are protesting is the thing that lowers your bill. Whether that lands in an election year is a separate question.

One Hundred Watts in Caldwell County

Last item, and the one nobody put in a queue. At 9:19 p.m. Eastern on August 5, in a 35-foot-deep concrete cavity southwest of Lockhart, Oklo's Groves isotope test reactor achieved first criticality — the fifth DOE-authorized advanced reactor to do so this summer, and the first on private land.

Maximum design power is 100 watts. It will never produce an isotope; Oklo's own communications lead confirmed as much. The DOE determination calls it a zero-power critical assembly running five Framatome GAIA low-enriched uranium dioxide assemblies, commercially procured, never to be refueled, on less than an acre inside a 47-acre parcel.

So why does it matter. Because of the clock. Oklo built the facility in 229 days and went from groundbreaking to a self-sustaining chain reaction in under a year, on private Texas dirt, with commercial fuel and no government material. "Reaching criticality in less than a year is an incredible milestone for our team," co-founder and CEO Jacob DeWitte said. In a week where the operative timeline for a Texas megawatt is "several months, and we'll get back to you on the study," somebody just demonstrated that the physics is not what takes ten years. The paperwork is.

What to Watch Next Week

Wednesday, August 19, 8:00 a.m. — Texas House State Affairs, JHR 140. Chairman Ken King has both charges on one agenda: data center development in Texas, explicitly including SB 6 implementation and the Large Load Batch Study Process, and the regulatory and planning processes for the proposed 765 kV transmission lines. One day before the Commission meets. That sequencing is not an accident.

Thursday, August 20, 9:30 a.m. — PUCT open meeting. ERCOT's good cause exception request is Item 22, Project 59142, with the large load interconnection standards rulemaking, Project 58481, sitting at Item 21. ERCOT has said it will detail the audit's scope and timing here. This is the meeting that decides whether the pause has an end date or a shrug.

August 31 — the dynamic-model cure deadline. Entities notified of deficiencies must resolve them by month-end or drop out of Batch Zero. ERCOT has asked the Commission to let anyone notified late cure within 24 days of notification instead. If that relief doesn't come through on the 20th, some queue positions die on a technicality nine days before September.

September — the study that cannot start, and the month that gets tight. ERCOT has said it cannot open the system-wide study in September. Separately, Ascend flags September as an emerging risk window: earlier sunsets cut solar output while evening wind runs below August levels. Watch evening net-load peaks and scarcity pricing.

Riot's Corsicana LOI and the credit backstop. A non-binding LOI on a full ~1 GW campus is not a lease, and a $573 million interim facility from Morgan Stanley is not permanent financing. Both convert or they don't, and the second one tells you what the first is really worth.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Twenty Megawatts: Now a Zoning Trigger, Still a Financing Orphan

Two things happened this week at opposite ends of the market, and neither one was good news if you build in the middle. Tucson set its data center permitting trigger at 20 MW or 25,000 square feet. The Town of Tonawanda, New York, deliberately halved its state's 50 MW moratorium threshold down to 20 MW. Meanwhile Hut 8 priced its second investment-grade project bond 20 basis points inside its first, at Baa2, in the same quarter. Construction risk got cheaper for gigawatt sponsors and more expensive for everyone else, in the same seven days.

The squeeze is now explicit. A 20 MW inference deployment in Tucson gets reviewed through the same zoning district as a power plant. That same 20 MW deployment cannot reach the project-bond market, which this week cleared exactly two deals, both north of 300 MW. What's left in the middle is improvisation — and the clearest example of it came from a company that borrowed $30 million against bitcoin collateral at 4.9% to fund a 20 MW retrofit, then hired a bank to sell the whole thing.

The Tripwire Fell to 20 Megawatts, in Two States, Two Days Apart

Tucson's mayor and council adopted the ordinance 6-1 on August 5. The definition of a "large-scale data center" is anything above 25,000 square feet or 20 MW — the disjunctive is the whole story. A 25 ksf, 15 MW pod trips the size test even if it never trips the power test. Anything that trips either one gets routed into a PAD or PCD rezoning, with mailed notice to every neighbor within a half mile, neighborhood associations within two miles, a neighborhood meeting, a Zoning Examiner hearing, and then council. Add a half-mile separation from residences, schools, washes and open space, a 50-foot height cap, 40-foot buffers, an all-frequency independent noise study, and a prohibition on potable water for cooling. Council also directed staff to explore legal pathways to an outright ban.

Two days earlier, the Town of Tonawanda passed Local Law 2-2026 unanimously — a one-year moratorium pegged to 20 MW of peak demand, against New York State's executive-order threshold of 50 MW. Supervisor John J. Flynn, on the record: "there is no back door." The single application caught by it is the Riverview Innovation & Technology Campus on River Road, the former Tonawanda Coke site — a 300 MW project, which is the point. The ordinance was written to stop a 300 MW brownfield conversion and it catches every 20 MW colo build behind it. The developer's response was that this is "an evolving issue, which we will continue to review with legal counsel," which is what you say when you have not decided whether to sue.

The counter-example is in Nebraska. Lincoln County's nine-page draft ordinance, up for a planning commission hearing this week, is the first code I have seen this year that explicitly distinguishes smaller ancillary and edge data centers from hyperscale facilities of 50 MW or more, and sets a 10-acre minimum site size. One jurisdiction out of three wrote the carve-out. That ratio is the risk you are underwriting.

Deal specs. Sponsor: Riverview Innovation & Technology Campus (former Tonawanda Coke site) · Site: River Road, Town of Tonawanda, Erie County, NY — within town limits, immediately N of the Buffalo city line · Footprint: ~500 ksf reported, not confirmed · Load: 300 MW (~600 W/sf if the reported footprint holds — the highest density spec in this issue) · Lease: n/d — no tenant disclosed; application frozen by Local Law 2-2026, one-year moratorium at a 20 MW trigger · Source: BTPM.

Hyperscale Data Hires a Bank: 20 Megawatts, One Neocloud, and a For-Sale Sign

Edge Cases covered the Michigan Center pivot earlier this year, when Hyperscale Data was still describing it as 20 MW with an option to 52. On August 11 the board announced a strategic review of the entire Michigan campus — sale, lease, joint venture, strategic investment, or spin — and retained an investment bank it declined to name. That is the update: the asset is now for sale, and it is the only genuinely in-band asset in the country with a sale process running this week.

The numbers are worth the arithmetic. Twenty megawatts of contracted critical compute inside a 60,000-square-foot retrofit pencils to 333 W/sf. The master services agreement runs ten years with two five-year extensions and is worth more than $1.2 billion at max term — which is $250 per kilowatt-month. Do not put that next to Riot's number and call it a premium. Riot's is a build-to-suit lease; this is a gross services rate with power and opex baked in. The spread is the opex load, not the pricing. The number that actually matters here is the retrofit capex: $100–120 million for 20 MW, or $5.0–6.0M per MW, against TeraWulf's published greenfield guidance of $8–10M per critical IT MW. A 40% basis advantage is the entire argument for the conversion trade at small scale, and this is the first clean print of it.

The financing is the tell. On August 3 the company established a bitcoin-collateralized borrowing program through Morpho and drew roughly $30 million at 4.9% to fund the Michigan build. Against construction debt at SOFR plus 250 to 400, that is cheap money — and it is also an admission that conventional construction debt does not reach a 20 MW asset with an unrated private tenant on competitive terms. The counterparty is an unnamed California neocloud. That is the weak link, and it is presumably why the bank got hired.

Deal specs. Sponsor: Hyperscale Data, Inc. (NYSE American: GPUS), via Alliance Cloud Services LLC · Site: Michigan Center, Jackson County, MI — ~5 mi E of Jackson city limits · Footprint: 60 ksf retrofit (existing mining shell, ~28 MW of bitcoin load being reallocated) · Load: 20 MW contracted, option to 52 MW (333 W/sf at 20 MW) · Lease: 10-yr master services agreement + two 5-yr extensions; gross services structure, escalator n/d; unrated private California neocloud tenant · Deal value: >$1.2B at max term (~$250/kW/month gross); retrofit capex $100–120M (~$5.0–6.0M/MW) · Source: SEC 8-K.

$154.67 to $198.52: The Build-to-Suit Tape, and the One Number Everyone Will Misread

Three large leases printed in this window, all of them well over 75 MW. They earn their place here for one reason: they are the comps every sub-75 MW deal is about to get measured against, fairly or not.

Riot Platforms set the ceiling. A 20-year build-to-suit at Rockdale, Milam County, Texas — 191 MW of critical IT for $9.1 billion through June 2048, with two five-year extensions that take it to $16.1 billion. That is $198.52 per kilowatt-month on the base term. Riot also disclosed cumulative NOI of $7.3–8.2 billion, which is an 80–90% margin on contracted revenue, and $1.91–2.15 million of NOI per MW per year. Riot did not name the tenant; Bloomberg and DCD report it is Anthropic. Delivery is phased — first 96 IT MW in December 2027, the balance by June 2028 — and Riot is carrying a $573 million interim facility from Morgan Stanley while it finalizes an investment-grade credit backstop.

Hut 8 set the floor at $154.67 per kilowatt-month on a 352 MW Beacon Point lease worth roughly $9.8 billion. The more useful disclosure was on the debt side: $3.25 billion of senior secured notes for River Bend, which Hut 8 calls the first investment-grade construction financing for a single-sponsor data center project, followed by $4.25 billion for Beacon Point Phase 1 at Baa2, priced 20 basis points inside the first deal. Both fully amortizing, both non-recourse to the parent. Construction risk repricing that fast, inside one quarter, is the signal — it eventually drags mezzanine and private-credit quotes down for everyone, but it reaches gigawatt sponsors first and the middle of the market last.

Then there is Fermi, which is the number that will get copy-pasted wrong. The TensorWave lease at Project Matador reads as 222 MW for $6.5 billion over 15 years, or $162.66 per kilowatt-month. Except the 222 MW is total facility power, not critical IT; the 15-year clock does not start until the final delivery phase commences; and the lease is expressly conditioned on receipt of project guaranties and financing that have not closed. Three haircuts on one headline. If critical IT runs 70–75% of facility power — a rule of thumb, not a Fermi disclosure — the implied critical-IT rate is closer to $217–232. Label it an estimate or leave it out.

Deal specs. Sponsor: Riot Platforms, Inc. (NASDAQ: RIOT), landlord · Site: Rockdale campus, Milam County, TX — ~60 mi NE of Austin · Footprint: n/d · Load: 191 MW critical IT, Tier 3 build-to-suit (density n/d — no square footage disclosed) · Lease: 20-yr initial through June 2048 + two 5-yr extensions; escalator n/d; tenant unnamed by Riot, reported as Anthropic; IG credit backstop being finalized · Deal value: $9.1B base / $16.1B with extensions (~$198.52/kW/month; $47.6M/MW over term) · Source: Riot Q2 2026 release.

One Megawatt in Pittsford, New York, for About $1.1 Million

The only closed asset trade in the band this week was very small, and that is exactly why it is useful. Carrier Connect Data Solutions closed on Rochester Colo on August 4 — a 36,000-square-foot building at 1100 Pittsford Victor Road, eight miles southeast of downtown Rochester, with 7,000 square feet of live white space carrying 1 MW and room to take it to 15 ksf and 4 MW.

Consideration was 800,000 common shares plus $250,000 cash, with the shares escrowed and released in four equal tranches at six, twelve, eighteen and twenty-four months. Against the $1.12 option strike the company set the same day, that implies roughly $1.15 million all-in, or about $1.1 million per live megawatt — call it $287,000 per MW against the 4 MW ceiling. Density on the white space is 143 W/sf; on the gross building it is 28. Neither number is impressive, which is the point: this is a Tier II/III carrier-neutral box with an existing customer base, not an AI deployment, and it traded at a price that reflects that. If you are pricing a sub-5 MW colo asset in a secondary metro, this is your 2026 comp, and it may be your only one. The buyer has declared a US roll-up strategy, so there should be more.

Deal specs. Sponsor: Carrier Connect Data Solutions Inc. (TSX.V: CCDS), via PureColo Inc.; seller Rochester Colo, LLC · Site: 1100 Pittsford Victor Rd, Pittsford, Monroe County, NY — within Pittsford, ~8 mi SE of downtown Rochester · Footprint: 36 ksf building; 7 ksf live white space, expandable to 15 ksf · Load: 1 MW live, 4 MW potential (143 W/sf on live white space; 28 W/sf gross; 267 W/sf at full buildout) · Lease: asset purchase, not a lease — APA dated June 8, closed Aug 4, 2026; arm's length; operating asset with existing customer base · Deal value: 800,000 shares + $250,000 cash, shares escrowed in four tranches over 24 months (~$1.15M implied, ~$1.1M per live MW) · Source: DCD.

Two Planning Votes on August 4, Two Councils on August 18, and a New Price of Admission

Both of these campuses are over 75 MW. They are here because between them they reset what a developer is expected to hand a municipality — and that expectation now applies to the 20 MW applicant standing behind them in line.

PowerHouse Data Centers, a division of American Real Estate Partners, cleared Westlake, Texas planning and zoning on August 4 for a four-building, 1.2 million-square-foot campus at 300 MW on 88 acres at US 377 and Westport Parkway. The site plan is unremarkable at 250 W/sf. The entitlement is not. PowerHouse paid Oncor to build a 350 MW switchyard at no cost to residents, sized 50 MW above its own need, with the surplus 50 MW carved out for the Town of Westlake and the town pump station running off it. Call it a power dowry. It came bundled with 8-foot sound walls along the entire southern boundary, a 220-foot landscape buffer, three-inch-caliper evergreen screening, and 506 feet from the building to the nearest residential property line in Keller. There is no tenant disclosed and no construction permitted until a development agreement passes council on August 18.

On the same day, 900 miles east, Statesboro's planning commission voted 5-1 to recommend rezoning 26.94 acres at 6539 Burkhalter Road for a two-story, 230 ksf box asking Georgia Power for up to 99 MW. That is 430 W/sf — the highest computable density in this issue, and a spec that tells you this is purpose-built AI, not enterprise colo, squeezed onto roughly a tenth of the acreage a 99 MW campus normally consumes. The applicant is eating closed-loop cooling, mandatory city water and sewer, a 50 dB property-line noise cap, a decommissioning plan, and a separate special use permit after the rezoning. Bulloch County, meanwhile, has a moratorium running to December 31 and is drafting an outright ban — city and county moving in opposite directions on the same tax base.

Deal specs. Sponsor: PowerHouse Data Centers / American Real Estate Partners; titled owner Circle T Owner LP · Site: 13580 Denton Hwy at US 377 & Westport Pkwy, Westlake, Tarrant/Denton counties, TX — within Westlake town limits, abutting Keller; ~2.3 mi from Meta's Alliance campus · Footprint: 1,200 ksf across four 300 ksf buildings on 87.96 acres · Load: 300 MW (250 W/sf) · Lease: n/d — no tenant disclosed; first building by-right, successive buildings require SUP; development agreement pending Aug 18 · Interconnect: 350 MW Oncor switchyard funded by sponsor, 50 MW surplus carved out to the town · Source: DCD.

Deal specs. Sponsor: 4AM Development LLC (Bobby Bagwell, Charles C. Way); agent Thomas & Hutton · Site: 6539 Burkhalter Rd, Statesboro, Bulloch County, GA — within Statesboro city limits, ~50 mi NW of Savannah · Footprint: 230 ksf across two stories on 26.94 acres, plus a 32 ksf substation · Load: up to 99 MW requested from Georgia Power (430 W/sf — request is not an approval) · Lease: n/d — no tenant disclosed; unrated private developer; rezoning R-4 to O recommended 5-1 Aug 4, council Aug 18, separate SUP still required · Source: Statesboro Herald.

What to Watch Next Week

Two councils, August 18. Westlake votes on the PowerHouse development agreement — watch whether the 50 MW town carve-out survives into the executed document, because that is the clause every subsequent applicant will be handed as a template. Statesboro votes on the Burkhalter Road rezoning at 5:30 p.m., and a yes still leaves a special use permit to win.

Soluna's first-ever earnings call, Thursday August 13. The live item is Project Kati 2 in Willacy County, Texas — an LOI with a single prospective tenant is signed and the company says it is finalizing design, commercial terms and the lease. A first-lease print from a small sponsor would be a far more relevant comp than anything Riot or Hut 8 disclosed this quarter.

WhiteFiber, Wednesday August 12, and Fermi, Thursday. WhiteFiber is guiding to 76 MW gross by year-end, which puts the whole company inside this newsletter's band; watch for lease signings and any $/kW disclosure. Fermi should face pressure to disclose the critical IT figure behind the 222 MW facility-power number, and the status of the guaranties the TensorWave lease is conditioned on.

Riot's takeout of the $573 million Morgan Stanley bridge. Whatever spread the permanent investment-grade financing prints at, measured against Hut 8's Baa2 benchmark, is next quarter's most important number for anyone financing a contracted build-to-suit at any size.

Recall petitions in Augusta Township, Michigan. Voters overturned a unanimously approved 522-acre Thor Equities rezoning by referendum on August 4, 2,314 to 269 — 89.5% against. Petitions are now under signature review against all seven trustees for a possible November ballot. Price the post-approval reversal window into anything you underwrite in a referendum-eligible jurisdiction.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"ERCOT Will Not Notify": 205 Gigawatts Miss Their Own Deadline

Today was supposed to be the day roughly 205 gigawatts of proposed Texas load found out whether it counted. Under the Batch Zero interconnection study process, ERCOT was to notify every transmission and distribution service provider, by August 7, how each large load in its territory had been classified — base load, studied load, or nothing at all. That notice is the gate. Everything downstream of it, from transmission planning to financing, keys off which bucket a project lands in.

Nothing arrived. On August 3, hours after Governor Abbott sent his directive to the Public Utility Commission, ERCOT issued a market notice saying so in advance, in the flattest language available to a grid operator. The deadline did not slip. It was withdrawn, four days early, and the entity that set it is now going to the Commission on August 20 to ask for permission to have missed it.

"ERCOT Will Not Notify"

The operative sentence in Market Notice M-A080326-01 is worth reading as written: "Based on the directive in the Governor's letter, ERCOT will not notify each Interconnecting Distribution Service Provider and Transmission Service Provider of how any Large Load is classified in the Batch Zero Interconnection Study by August 7, 2026." ERCOT says it will file for a good cause exception to the Batch Zero timelines in Planning Guide Sections 5 and 9, in advance of the PUCT's August 20 open meeting.

The stated reason is compliance, not capacity. Abbott's August 3 letter ties the pause to a survey: "The failure of some data centers to comply with the PUC's survey measuring water and power usage under the General Appropriations Act makes this necessary." A questionnaire is now the binding constraint on 205 GW of interconnection study work.

Scale matters here. Pablo Vegas told the Senate Business and Commerce Committee on July 29 that ERCOT's large-load queue stands at roughly 474 GW, of which 420.8 GW — 90.2 percent — is data centers. Of that, about 205 GW cleared the bar for Batch Zero: commitment criteria met by July 10, or site control plus financial security plus a notarized attestation by July 24. Those developers did the paperwork. The paperwork is now in a drawer.

One correction from last week, while we are on the subject of numbers that get reported before they are final. I printed 91,308 MW as ERCOT's July 22 peak. That was the preliminary real-time figure. ERCOT's all-time records table uses integrated hourly load and lists 91,089 MW. Still a record, still the number the 474 GW queue should be measured against — that queue is 5.2 times the largest hour Texas has ever produced.

$1.76 Billion per Gigawatt per Month, on Hold

BloombergNEF published the first serious attempt to price the pause on August 5, and the numbers are larger than the Texas framing suggests. BNEF puts 49.8 GW of data center capacity at risk of delay — roughly 20 percent of the entire 253 GW US pipeline. This is no longer a state story. One governor's letter put a fifth of American data center development into a holding pattern.

The revenue math is where it gets uncomfortable. BNEF, working from Silicon Data's GPU rental benchmarks, values AI compute at about $1.76 billion per gigawatt per month. CBRE's figure for traditional colocation shell in Dallas is up to $175 million per gigawatt per month. That is a ten-to-one spread, and it explains every strange thing in this market: why a miner will torch its balance sheet to convert, why hyperscalers sign fifteen-year parent-guaranteed leases, why nobody walks away from a Texas interconnect. Cumulative revenue foregone by the first quarter of 2027 runs just over $8 billion at a 60 percent AI compute mix, and around $15 billion if the mix goes to 100 percent.

BNEF also said out loud what everyone in Austin has been saying quietly: Abbott faces reelection in November, and the pause takes a contentious issue off the table until after the voters weigh in. Meanwhile QTS, the Blackstone-owned operator, spent August 6 applauding the audit. Co-CEOs Tag Greason and David Robey called Texas "a global leader in technology and innovation" now "leading the national path forward." Incumbents with energized load rarely object to a freeze on everyone behind them.

Cipher Digital, formerly Cipher Mining, offered the week's cleanest illustration of the timing problem. On August 4 it announced an option on Apollo — roughly 288 acres and up to 900 MW within 25 miles of San Antonio — and disclosed it had already submitted the site as studied load in Batch Zero. That is to say: filed into the process one day after the process stopped.

Oncor Already Counted Its Batch Zero. It Comes to 44 Gigawatts.

Two days before the deadline ERCOT did not meet, the utilities told investors exactly what they think they are holding. Oncor, reporting alongside Sempra on August 6, expects roughly 44 GW of large-load requests in its territory to qualify as base or studied load — about 27 GW as base load and 17 GW as studied. Set against Oncor's current system peak of 31 GW, that is more than 140 percent growth. Eight of the 44 GW is already-interconnected load ramping toward authorized capacity, so the net-new figure is smaller, but not by much.

CenterPoint got there first. On its July 28 call it said it had submitted more than 17 GW and expected 14 GW to be eligible — roughly 10 GW base, 4 GW studied — backed by about $900 million in customer cash commitments and deposits. Against a Houston-area peak of 21 GW, that is a 65 percent increase.

Combined, two utilities are underwriting 58 GW of new demand against 52 GW of existing peak. Oncor expects to build most of the ERCOT-endorsed transmission requiring $7 billion-plus of incremental investment, in service between 2026 and 2034. Sempra's five-year capital plan runs to about $65 billion, roughly 95 percent of it into Texas and California utilities. The capital is committed. The classification letters are not. Note which one moved first — utilities do not raise capital plans on load they expect to be disqualified, which tells you what they think August 20 produces.

The Other Texas Pause Runs at 765 Kilovolts

While the queue froze, the wires that would serve it took fire from a different direction. The Strategic Transmission Expansion Plan for the Permian Basin — three import paths, five segments, more than 1,200 miles of 765-kV line, roughly $33 billion of initial capex and reportedly approaching $100 billion over its life — is now the most politically exposed infrastructure project in the state.

On July 31, Lieutenant Governor Dan Patrick and Senator Charles Schwertner called on the PUCT to deny every pending application until the Legislature reforms the approval process. More than forty lawmakers had already asked for a pause until 2027. At a marathon July 29 hearing, Chairman Thomas Gleeson conceded the Commission had pursued the 765-kV plan without an explicit legislative vote authorizing it.

Be precise about what has and has not happened, because the coverage has been sloppy. The Commission has not paused the project. In June it abated its decision on one of the five segments pending an administrative law judge ruling on a related segment, and the ALJs issued that proposal for decision on July 24. Since then the PUCT has done the opposite of pausing: it has calendared four segments for August 28, September 25 and October 2, with landowners to be heard in oral argument. The House Committee on State Affairs holds an interim hearing on the lines August 19 — one day before the PUCT meeting where ERCOT explains the Batch Zero miss. Someone scheduled that well.

The through-line is uncomfortable for anyone financing Texas load growth. The state is simultaneously slowing the process that decides which data centers connect and slowing the process that decides whether the wires get built to serve them. Those were meant to be the two halves of the same answer.

$1,419 a Kilowatt for Steel That Already Exists

Private capital, predictably, did not wait for any of this. LS Power agreed on August 6 to buy the 606-MW Brazos Valley Energy Center in Fort Bend County from Constellation for $860 million, closing expected in the fourth quarter subject to DOJ Antitrust Division approval. That works out to about $1,419 per kilowatt for a 2003-vintage combined-cycle plant with two GE 7FA turbines — a number that would have looked absurd three years ago and now reads as a discount to anything you could permit and build.

It is also the last asset Constellation was required to divest under the commitments it made to get Calpine done, alongside the roughly 4,353 MW PJM portfolio LS Power agreed to take in March. Post-close, LS Power runs about 14.1 GW nationally. Paul Segal's framing was the entire investment thesis in one sentence: "Acquiring and optimizing proven assets is one of the fastest and most cost-effective ways to meet that need." Fastest is doing the work in that sentence. An operating interconnect in ERCOT is now a scarce good, and the pause just made it scarcer.

Vistra's second quarter, reported this morning, shows what owning the existing fleet is worth in a market like this. Texas segment adjusted EBITDA came in at $311 million against $142 million a year ago — up 119 percent. Ongoing operations adjusted EBITDA of $1,767 million was more than 30 percent higher year over year, the fleet ran above 97 percent commercial availability through extreme heat in Texas and PJM, and Vistra picked up FERC approval on Cogentrix. It also disclosed an initial commitment of up to $1.0 billion to Helix Digital Infrastructure, the KKR-and-Nvidia-backed vehicle where Vistra is the preferred power partner.

Read those two items together. LS Power is paying $1,419 a kilowatt for existing gas, and Vistra doubled Texas earnings on a fleet it already owned. Neither of those trades requires a classification letter from ERCOT. The pause did not stop capital from entering Texas power. It redirected it toward megawatts that are already connected — which is to say, it converted grid access from an asset into a moat, and handed the moat to the incumbents.

What to Watch Next Week

August 19 — House State Affairs interim hearing. The 765-kV lines go before the committee one day before the PUCT open meeting. Watch whether members use it to pressure commissioners ahead of the August 28 segment vote.

August 20 — PUCT open meeting. The single most consequential date on the Texas calendar. ERCOT files its good cause exception on the Batch Zero timelines. Either the Commission sets a new classification date or 205 GW sits in limbo without one. There is no third outcome that anyone can finance.

August 28 — first 765-kV segment on the agenda. Landowner oral arguments, with September 25 and October 2 to follow. A denial on the first segment would reprice the entire Permian plan.

September — PUCT adoption of 16 TAC 25.194. The SB 6 large-load interconnection standard is expected to land next month, with a statutory deadline of December 31. Watch whether the audit's disclosure categories get folded into the final rule, which would make the pause permanent by other means.

Fourth quarter — DOJ on Brazos Valley. Approval discharges Constellation's last Calpine divestiture obligation and confirms roughly $1,400 per kilowatt as the clearing price for connected ERCOT gas.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"Must Be Denied": Abbott Freezes the 474-GW Queue — and NRG Signs $3.2 Billion Anyway

On Monday, Governor Abbott sent a letter to the PUCT and ERCOT directing them to pause data center interconnections until every project in the queue survives a "comprehensive verification and audit" of its power needs, water usage, and tax incentives. By Tuesday, ERCOT had shelved the Batch Zero classification notices that were due tomorrow. And roughly 24 hours after the state froze 474 GW of interconnection requests, NRG announced it had agreed terms with a hyperscaler on the largest contracted gas newbuild of this cycle — $3.2 billion, 1.2 gigawatts, 15 years.

That is the week in one sentence: the state hit the brakes, and capital kept its foot on the gas. The projects that cleared before the freeze — existing interconnects, dedicated generation, signed contracts — just got more valuable. Everyone else got a compliance questionnaire and an indefinite timeline.

"Any Data Center Project That Fails to Comply... Must Be Denied"

The ERCOT interconnection queue currently holds about 474 GW of large-load requests, roughly 90 percent of them data centers — more than five times the all-time peak demand record. Abbott's August 3 letter orders an audit of every one of them: how much power each project actually needs, whether it is building its own generation or leaning on the grid, whether it is bringing its own water or drinking the local supply, and whether it is "paying its own way" or running on state and local tax abatements. The closing line does not leave much to interpretation: "Any data center project that fails to comply with the verification and audit process to protect the reliability and resilience of the Texas electric grid must be denied."

The immediate casualty is Batch Zero. I covered the window closing three weeks ago, and the $50-million-per-gigawatt deposits that came due July 10. The classification notices those deposits bought were scheduled for August 7 — tomorrow. They are not coming. ERCOT issued a market notice delaying the study and will ask the Commission for a good-cause exemption to the timeline at its August 20 open meeting. The August 31 deficiency-cure deadline is presumably fiction now too, though nobody has said so out loud.

The price tag on the pause depends on whose model you believe. BloombergNEF estimates the audit could delay 49.8 GW of load — about 20 percent of the entire US data center pipeline — at a cost to projects of up to $15 billion. Troutman Pepper Locke called it a "delay of indeterminate duration" and told clients to start checking counterparty termination rights. Even the Data Center Coalition, whose members are the ones being audited, mostly asked that the process move fast enough to "distinguish between speculative projects and serious, committed investors." Translation: the industry knows most of the 474 GW is vapor, and the developers with real projects would like the state to hurry up and say which is which.

Texas is the second state to blink in a month — New York halted new data center approvals in July for up to a year. The difference is that New York was never the growth market. Texas is where the queue lives.

NRG Sells 1.2 GW to a Hyperscaler It Won't Name — and the Timing Says Everything

On its Tuesday earnings call, NRG announced it has "aligned on principal commercial terms" with an unnamed investment-grade "leading global cloud and AI hyperscaler" for a new 1.2-GW combined-cycle gas plant in Texas. The shape of the deal: $3.2 billion of capex, a 15-year contract with a parent guarantee, capacity payments covering 95 percent of projected free cash flow, more than $500 million in expected annual adjusted EBITDA, a late-2029 commercial date, and an option to double the whole thing to 2.4 GW. NRG added $721 million to its 2026 capital plan to get moving.

Asked whether Abbott's pause affects the project, NRG's Robert Gaudette declined to say. He may not need to. A dedicated plant with a contracted offtaker and 95 percent of its cash flow guaranteed by an investment-grade parent is precisely the structure the audit is designed to favor — self-supplied power, no speculative grid dependence, a counterparty who is visibly paying its own way. The queue is now political; bilateral steel is not. Announcing the biggest contracted gas newbuild of the cycle one day into a statewide interconnection freeze is either remarkable luck or a very pointed demonstration of which side of the line the money wants to be on.

Cipher's 5.3 GW, and the Earnings Call Riot Didn't Hold

Miner earnings week told the same story from the other direction. Cipher's second-quarter update was, on the surface, ugly — a $267.5 million GAAP net loss on roughly $25 million of mining revenue, and the stock gave up about 10 percent on the print. Underneath, the HPC conversion is accelerating: Black Pearl capacity in West Texas delivered two months early, an $810 million project financing closed for Stingray, and Barber Lake Phase 1 — about 168 critical IT megawatts in Colorado City — on track for rent to start in October with the tenant already in partial occupancy. The portfolio now stands at 5.3 GW across 11 sites, and management guided contracted capacity to roughly $793 million of average annualized NOI, ramping from $97 million next year toward $894 million by 2035.

Note what a miner-turned-developer actually owns in this market: energized interconnects that predate the freeze. Cipher's sites are not in the audit line. Neither is anyone else's already-connected load. The pause converts existing grid access from an asset into a moat.

Riot, meanwhile, abruptly rescheduled its Tuesday earnings call with no new date. Companies do not postpone earnings calls during deal season for scheduling reasons. With AMD already at 50 MW in Corsicana and a $400 million building permit on file for Project Ditto, the silence is doing a lot of talking. Something is being papered.

Two Records in 48 Hours, and a Forecast That Doubles the Grid

The demand math behind all of this keeps getting steeper. ERCOT broke its all-time peak twice in one July week — 87,403 MW on July 21, then 91,308 MW on July 22, retiring the August 2023 record that had stood for three years. Five days later, ERCOT told a Texas Senate panel that statewide peak demand could reach about 175,000 MW by 2032 — nearly double the record set the week before, driven overwhelmingly by large loads.

That 175 GW figure is the sober one. The preliminary forecast ERCOT filed in the spring showed demand more than quadrupling by 2032 before the grid operator distanced itself from its own number — I covered that episode when it happened. The Senate presentation on July 29 is the analytical predicate for the Abbott letter on August 3: if you believe demand doubles in six years and you believe most of the queue is speculative, an audit is what you do. The uncomfortable part is that both beliefs are probably correct, and the audit still freezes the real projects alongside the phantom ones while it sorts them.

What to Watch Next Week

The August 20 PUCT open meeting. ERCOT will ask for a good-cause exemption to the Batch Zero timeline. Watch whether the Commission sets a new classification date or leaves it open-ended — that word choice is worth billions in carrying cost.

Riot's rescheduled call. A postponement with no new date, during deal season, with AMD already on site in Corsicana. When the call happens, the interesting number will not be the mining revenue.

NRG's counterparty. "Principal commercial terms" is not a definitive agreement. Watch for the hyperscaler's name, the definitive docs, and whether the 2.4-GW doubling option gets exercised early.

Audit mechanics. Nobody has published the actual verification process yet — who runs it, what the disclosure forms look like, how long a compliant project waits. The first project to clear the audit sets the template.

August heat. The 91,308 MW record was set in July. August is usually worse, and the pause is now politically coupled to grid performance. A tight afternoon with conservation appeals would hand ammunition to both sides of the argument.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Demand First, Dirt Second: A 40 MW Pre-Lease, $50M/GW Deposit Math, and the ABS Window Reopens

The week's tape reads like the market decided dirt is the easy part. The deals that actually closed between July 28 and August 4 were contracts and credit structures — a 40 MW campus 100% pre-leased before it's fully built, a 1.125 MW Dallas colo hall signed only after the offtake was locked, a $95 million fund invented in weeks to front ERCOT's interconnection deposits, and a $1.18 billion securitization that got upsized 30% because investors who'd never bought data center paper wanted in. Meanwhile the entitlement door kept narrowing: Loudoun County — the densest data center market on earth — rejected 3.25 million square feet and asked its lawyers whether it can stop taking applications altogether.

If you're chasing 10–60 MW deployments, that's both doors moving at once. The capital markets door is swinging open, but only for projects with contracted demand attached. The zoning door is closing on everything else. Demand first, dirt second.

A Dogecoin-Treasury Cleaning Company Just Pre-Leased 40 MW to Cerebras

CleanCore Solutions is an Omaha cleaning-products company that spent the spring holding a Dogecoin treasury and pivoted to AI infrastructure in June. On July 29 it announced a 10-year colocation services agreement with wafer-scale chipmaker Cerebras covering 40 MW of critical IT load at a Minnesota campus — 100% of the site, pre-leased, at roughly $800 million initial contract value, with two 10-year renewal options that could push the total past $3 billion. Fifteen MW of IT load is live today on about 20 MW of energized utility power; the rest, and first revenue, lands Q1 2027.

The structure is the interesting part. The campus sits in a new JV — Monarch SPV HoldCo LLC, CleanCore at 79% with up to $500 million of committed capital, a partner contributing the project assets and development services. Laugh at the sponsor's résumé if you want, but run the math: ~$2 million per IT-MW per year on a 10-year single-tenant term, fully pre-leased before buildout. That is the cleanest mid-size comp printed this week, and it came from a company that sold floor cleaner eighteen months ago. Classic.

Deal specs. Sponsor: CleanCore Solutions via Monarch SPV HoldCo LLC (79/21 JV); tenant Cerebras Systems · Site: Minnesota; city n/d · Footprint: n/d · Load: 40 MW critical IT (55 MW utility at full buildout; 15 MW live today) · Density: n/d — no sf disclosed · Lease: 10-yr colocation services agreement, 100% pre-leased single tenant, two 10-yr renewal options, escalator n/d; tenant newly public, not investment-grade · Deal value: ~$800M initial term, >$3B with renewals · Source: DCD.

1.125 MW in Dallas, and the Offtake Came First

The smallest deal of the week is the purest expression of the same logic. Kidz AI — the former edtech company Classover, pivoted to neocloud in May — signed an MoU announced August 3 to lease 1.125 MW at Limestone Networks' DFW3 facility in Dallas for an Nvidia B300 cluster, starting at 0.5–0.6 MW in a dedicated hall and ramping as servers arrive. The colo capacity exists solely to serve an already-signed 60-month, $44.6 million GPU services agreement with inference platform Canopy Wave. CEO Stephanie Luo said it plainly: demand first, capacity second.

Two things worth filing. First, the underwriting template — contracted downstream revenue before the lease is inked — now runs from 1 MW to 40 MW without modification. Second, the real estate: legacy downtown colo and carrier hotels are absorbing the single-digit-MW inference clusters the big builders won't touch. That's inventory most brokers wrote off years ago.

Deal specs. Sponsor: Kidz AI (via Catalyst Compute); landlord Limestone Networks; offtake Canopy Wave · Site: Limestone DFW3, within Dallas city limits; address n/d · Footprint: n/d — one dedicated hall · Load: 1.125 MW at full ramp (0.5–0.6 MW initial) · Density: n/d · Lease: colocation MoU (not yet definitive), term n/d, underpinned by 60-mo $44.6M GPU services agreement; Nasdaq micro-cap tenant, speculative credit with contracted revenue · Source: DCD.

$50 Million per Gigawatt, Due July 10: Who Fronted Batch Zero's Deposits

Last issue I told you ERCOT's Batch Zero window had closed and the studying had started. Here's who wrote the checks. Houston's Dynamix Capital Partners, with Staubach Capital and Soda Springs, closed the ~$95 million SSSC Batch Zero Fund on July 30 — a first-of-its-kind vehicle that financed the security deposits Texas landowners had to post by July 10 to qualify for ERCOT's large-load interconnection process, priced at $50 million per gigawatt. The fund backed roughly 1.7 GW of requested capacity, including a 1.2 GW site adjacent to Austin and a 480 MW site adjacent to the DFW metroplex. Allocations are expected April 2027; refundability hangs on a PUCT rule (16 TAC §25.194) anticipated for adoption in September.

The sites are mega — that's the exception, and the reason it's here is the product, not the parcels. Traditional lenders wouldn't underwrite bespoke, refundability-uncertain collateral on a three-week fuse, so someone built a fund that would. Every landowner and mid-size developer heading into future ERCOT batches now has a benchmark for what deposit financing costs and who supplies it. Expect imitators before the April allocations print.

Deal specs. Sponsor: Dynamix Capital Partners + Staubach Capital + Soda Springs (SSSC Batch Zero Fund LP), anchored by an unnamed institutional credit partner · Site: 1.2 GW site adjacent to Austin; 480 MW site adjacent to DFW; exact locations n/d · Footprint: n/a — powered-land deposit financing · Load: ~1.7 GW of requested interconnection capacity backed · Structure: fund finances landowner security deposits at $50M/GW under ERCOT Batch Zero; refundability pending 16 TAC §25.194 (Sept 2026); allocations April 2027 · Deal value: ~$95M deployed · Source: GlobeNewswire.

Aligned Reopens the ABS Window: $1.18B, Upsized 30%, 90% Investment-Grade Rent

Aligned Data Centers closed a $1.183 billion asset-backed securitization on July 28 — its first since 2023 — upsized roughly 30% from a $905 million target on institutional demand, including investors new to the asset class. Collateral: four stabilized campuses across three markets, 14 enterprise customers, more than 90% of annualized adjusted base rent from investment-grade counterparties. Multi-tranche, five-year anticipated repayment dates, proceeds to the development pipeline and refinancing.

This one's here as the week's cost-of-capital benchmark — the portfolio is big, but the signal prices every stabilized 10–60 MW colo asset in the country. A reopened, oversubscribed data center ABS market means the exit and the refi both got cheaper for anyone holding leased, investment-grade rent rolls. If your asset can't clear that 90% IG bar, you now know exactly what the market is paying up for.

Deal specs. Sponsor: Aligned Data Centers (private; recently acquired by a BlackRock GIP-led consortium) · Site: 4 stabilized campuses across 3 markets; markets n/d · Footprint: n/d — portfolio level · Load: n/d · Structure: multi-tranche ABS (Class A-2-I + Class B), 5-yr anticipated repayment, 14 enterprise customers, >90% of AABR investment-grade · Deal value: $1.183B (vs. $905M target) · Source: GlobeNewswire.

Loudoun Blinks: 3.25 Million Square Feet Rejected, a Moratorium on the Table

Loudoun County's Planning Commission voted unanimously to recommend denial of Spring Valley Technology Park — 12 buildings, 3.25 million sf, three substations and utility-scale storage on roughly 325 acres near Beaverdam Reservoir — after more than 500 residents showed up in opposition. The Board of Supervisors separately voted 6-1 to have staff study whether a temporary moratorium on new data center applications is even legal, with staff reporting back September 15. This is Data Center Alley, the densest concentration of data centers on the planet, contemplating a full stop on intake.

The campus is mega; the consequence isn't. It landed the same week Hillsboro, Oregon passed a four-month pause, DeSoto County, Florida a one-year, La Conner, Washington six months, Paulding County, Georgia its own, and Akron moved to require a council vote plus disclosed power, water, and noise specs per project. If NoVA pauses intake, every already-entitled, already-powered sub-75 MW site in Loudoun and its spillover metros — Richmond, Culpeper, Frederick — just picked up a scarcity premium without lifting a finger. Entitlement is becoming the asset.

Deal specs. Sponsor: Spring Valley Technology Park developer · Site: ~325 acres near Beaverdam Reservoir, unincorporated Loudoun County, VA, adjacent Banshee Reeks Nature Preserve · Footprint: 3,250 ksf across 12 buildings + 3 substations + storage · Load: n/d — 780 MW reported but unverified in primary documents · Density: n/d · Structure: legislative rezoning — Planning Commission recommended denial; Board action pending; countywide moratorium study due Sept 15 · Source: DCD.

What to Watch Next Week

Vineland, NJ — Wednesday, August 5. The Planning Board decides whether DataOne's partially constructed data center can proceed. A live test of mid-Atlantic entitlement risk on a build that's already out of the ground.

Moratorium calendar. Marshalltown, Iowa holds a public hearing on a four-month pause August 10; Harrison County, Kentucky's fiscal court votes on its own August 11. The county-by-county map keeps redrawing itself weekly.

Bisnow DICE South, Dallas–Fort Worth — August 12–13. Expect term-sheet chatter on DFW mid-size colo and powered land. Denver follows August 20.

Box Elder County, UT — August 18. The MIDA board takes up the contested Stratos project; a water permit filing is promised by end of August.

Piedmont, OK — before August 24. Cloverleaf Infrastructure owes the council a peer-reviewed water and wastewater study ahead of a re-vote. And circle September 15 for Loudoun's moratorium study returning to the Board.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

The Comp Is $1.76M per MW-Year. The Constraint Is Permission.

The week priced both ends of this market at once. At the top, AMD put chipmaker credit behind 529 MW of 15-year leases on converted mining campuses — call it $1.76M per MW-year, and every mid-size take-or-pay in a secondary metro will now get marked against that paper. At the bottom, the 8–75 MW edge deal is getting harder to close, and not for lack of power. Forney, Texas is drafting a citywide ban. Tulare, California tabled a fairgrounds ground lease after hours of public comment. Crusoe's county-park site in Virginia surfaced via FOIA request instead of a press release. The constraint in this market has stopped being megawatts. It's permission.

Five stories this week: the AMD–Core Scientific lease package that resets the comp, Crusoe's quiet 150 acres in Franklin County, Virginia, a dead semiconductor fab in Eugene going for roughly $17 a foot, Global Stack's fairgrounds strategy hitting its first real market test, and one Texas county drawing two opposite zoning maps fifteen miles apart.

15 Years, 529 MW, $14 Billion: AMD Puts Chipmaker Credit Behind the Miner Conversion Trade

One deal this week clears our usual 75 MW ceiling, and it's in the issue for two reasons: it's a multi-site package whose smaller slugs are exactly the size this audience transacts, and it sets the lease-term benchmark everything below it will price off. On July 27, Core Scientific signed 15-year leases covering 529 MW of critical IT load across five sites — Pecos and Hunt County in Texas, Muskogee in Oklahoma, Auburn in Alabama, and Dalton in Georgia — with AMD taking 377 MW directly and an unnamed AMD-backed neocloud taking the remaining 152 MW. Base contracted revenue exceeds $14 billion, with options extending to 30 years and rights for AMD to reserve up to 1,925 MW more through late 2028.

Run the arithmetic: $14B across 529 MW over 15 years is roughly $26.5M per MW of total base, or about $1.76M per MW-year. That's the number to write down. This is the first time a chipmaker — not a hyperscaler — has anchored long-dated leases on converted mining campuses, and the Auburn and Dalton slugs at a combined 152 MW show AMD is willing to backstop neocloud credit at the mid-size sites where most of you operate. AMD also took a warrant for up to 30 million CORZ shares, part vested immediately and the rest vesting as megawatts energize — the equity kicker riding on delivery, not the signature. Core Scientific's Q2 disclosure confirms the mining wind-down that makes the whole conversion trade legible: the bitcoin fleet is now the land bank.

Deal specs. Sponsor: Core Scientific (landlord, crypto-pivot); AMD (tenant, 377 MW) + unnamed AMD-backed neocloud (152 MW) · Site: five campuses — Pecos, TX (Reeves County); Hunt County, TX (~45 mi NE of Dallas city limits); Muskogee, OK (within city limits); Auburn, AL (within city limits); Dalton, GA (within city limits, ~30 mi S of Chattanooga) · Footprint: n/d · Load: 529 MW critical IT, expansion rights to 2.5 GW total through late 2028 · Density: n/d · Lease: 15-yr initial, options to 30 yrs, escalator n/d, investment-grade anchor (AMD) plus warrant for up to 30M CORZ shares · Deal value: >$14B base contracted revenue (~$1.76M per MW-year, computed) · Source: CoinDesk.

Project Flash: Crusoe's 150 County-Owned Acres in Virginia, Surfaced by FOIA Instead of a Press Release

Franklin County, Virginia has been negotiating with Crusoe since November over roughly 150 acres of the county-owned Summit View Business Park on US 220 outside Rocky Mount — a 50–100 MW project on land that already has grid and natural gas infrastructure in the ground, per documents obtained by FOIA and reported by DCD. Neither Crusoe nor the county has confirmed the deal publicly. What did surface publicly, on July 27, was a misconduct complaint against county leadership alleging improper conduct in how the negotiations were handled.

The playbook itself is the one this audience runs: county-owned business park, entitlements and utilities pre-positioned, a landlord that wants the deal more than you do. Cheap entry. The Franklin County lesson is that it is no longer quiet entry — eight months of NDA-phase negotiation on public land ended with a document dump and a complaint, not a groundbreaking. Flag this one as developing; there is no executed land deal to spec yet.

Deal specs. Sponsor: Crusoe (developer, crypto-pivot — divested mining March 2025); Franklin County, VA (landowner); no compute tenant named · Site: Summit View Business Park, Rocky Mount, VA — ~20 mi S of Roanoke city limits · Footprint: n/d (~150 acres of a 540-acre park) · Load: 50–100 MW planned · Density: n/d · Lease: n/d — land deal not yet executed; talks since Nov 2025, unconfirmed by either party · Tenant credit: private (venture/infra-backed) · Source: DCD.

The Cheapest 1.2 Million Square Feet in the Northwest

The former Hynix semiconductor plant in west Eugene, Oregon — 1.2M sq ft on a 200-acre campus, idle since 2008, fab-grade electrical service and industrial water still attached — reportedly went at auction for about $20M. That's roughly $17 a square foot for a building whose replacement power infrastructure alone would run multiples of the price. On July 14 the buyer's land-use attorney filed a zone-verification request asking Eugene to confirm data center as a permitted use under the site's E-1 Campus Employment zoning — which tells you the intended use even though escrow hasn't closed and the buyer, reportedly True Data Center, remains unconfirmed until it does.

Fab conversions are the purest expression of the 2026 trade: buy the interconnect, not the dirt. No MW figure has been disclosed, so we won't invent a density — but a building engineered for semiconductor manufacturing does not need to apologize for its electrical room. Inside city limits, existing industrial zoning, utilities in place. The entitlement risk that killed two other stories in this issue is largely pre-solved here, which is the entire thesis.

Deal specs. Sponsor: unidentified buyer under contract (reportedly True Data Center); zone request filed by attorney Bill Kloos · Site: former Hynix plant, west Eugene, OR — within Eugene city limits · Footprint: 1,200 ksf on 200 acres, idle since 2008 · Load: n/d (fab-grade service in place) · Density: n/d · Lease: fee acquisition, ~$20M reported auction price (~$17/sf); E-1 zone verification pending · Tenant credit: private / unknown · Source: Lookout Eugene-Springfield.

Cotton Candy and Colocation: Global Stack's 8–10 MW Fairgrounds Pods Stall in Tulare

Global Stack's land strategy is the most aggressive inner-ring edge play in the country: 2–5 acre ground leases at California state fairgrounds, terms proposed up to 100 years, revenue share to the fair boards, 8–10 MW per site, roughly $20M per site, up to 70 sites by 2030. If fully built, that's 560–700 MW aggregate assembled entirely from public land nobody else was bidding on. On July 21 the strategy hit its first real market test, and the Tulare County fair board tabled the lease vote after hours of public comment; residents rallied against the proposal two days later. Calistoga talks are already dead. The Kings County fair board in Hanford is still evaluating.

The specs are thin because the deal is thin — no anchor tenant disclosed, no water from the city per the fair's own CEO, construction split across three affiliated LLCs. But the strategic question is real: whoever solves the community-consent problem at 10 MW owns California edge. Global Stack hasn't yet.

Deal specs. Sponsor: Global Stack LLC (with MeshClusters LLC, DAA Parking LLC, PanGalactica LLC); counterparties are state fair boards · Site: Tulare County Fairgrounds, within Tulare city limits (Visalia metro); Kings Fairgrounds, Hanford, CA pending · Footprint: 2–5 acre pads per site · Load: 8–10 MW per site; up to 70 sites by 2030 (~560–700 MW aggregate if built) · Density: n/d · Lease: ground lease on public land, proposed terms up to 100 yrs, revenue share, ~$20M per site; Tulare vote tabled July 21 · Tenant credit: private / speculative, no anchor tenant · Source: The Business Journal.

Kaufman County Splits the Map: Forney Bans, Terrell Zones

Same county, fifteen miles apart, opposite answers. In Forney — twenty miles east of Dallas city limits — a reported 20 MW project sitting roughly 1,000 feet from a subdivision deadlocked the planning commission 3–3 in June, and when the appeal reached council on July 21, the council went further than denial: it directed staff to draft an ordinance prohibiting data centers in all zoning districts. That's an escalation from April's rules, which had already imposed a 5,000-foot residential setback and a conditional-use permit. Forney went from "far from houses" to "not here" in ninety days.

Terrell, meanwhile, read the same demand wave and drafted a purpose-built "Technology Infrastructure Campus" zoning district, with a public hearing held July 23 and council consideration set for August 18. For anyone chasing DFW-east exurb sites, the entitlement map redrew itself in one week — and the redraw, not any single deal, is the story. Sites don't die in this market because the substation said no. They die because the council did.

Deal specs. Sponsor: n/d (Forney project developer unnamed in coverage) · Site: Forney, TX (within city limits, ~20 mi E of Dallas city limits); Terrell, TX (~32 mi E of Dallas) · Footprint: n/d · Load: 20 MW (reported, the denied Forney project) · Density: n/d · Lease: n/a — zoning actions; Forney drafting all-district ban, Terrell's new district to council Aug 18 · Tenant credit: n/d · Source: inForney.

What to Watch Next Week

Aug 3 — Menomonie, WI. City council reviews the draft I-4 zoning ordinance for the 320-acre data center site. No vote scheduled; the standards cover noise, water, setbacks, and reclamation.

Aug 3 — Lakeland, FL. Second and final reading on the one-year data center moratorium.

Aug 5 — Vineland, NJ. The planning board decides whether the partially built DataOne facility — building Nebius's US behind-the-meter site — proceeds. Organized opposition expected, under oath.

Aug 5 — Kansas City, MO. Planning commission takes up the 20-story downtown conversion of the Western Newspaper Union building — a rare vertical urban-core test.

Aug 18 — Terrell, TX. Council votes on the Technology Infrastructure Campus district, the pro-development half of the Kaufman County split. Also watch Core Scientific's 10-Q for site-level MW allocations behind the AMD leases, and Loudoun County's September 15 moratorium vote.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"Last Night It Was Nearly 12,000" — The Record Week, and 438 GW at the Door

The all-time ERCOT demand record stood for nearly three years. This week it lasted about 24 hours. On Tuesday, July 21, the grid hit 87,403 MW, finally breaking the 85,508 MW mark set in August 2023. On Wednesday, load blew straight past 91 gigawatts to 91,308 MW. Triple-digit heat from Dallas to Houston, humidity riding in off Tropical Storm Bertha, heat indices touching 112°F — and not one conservation appeal, not one emergency notice, not one incident.

That is the week in one sentence: the biggest load ERCOT has ever served, absorbed with a shrug. Meanwhile, the paperwork window closed on the 438 GW of future load waiting to get in, and a former Bitcoin miner on the Gulf Coast fully leased out a 1 GW AI campus for $19.6 billion. Demand present, demand future, and the machine that decides who gets to plug in — all in seven days.

"Last Night It Was Nearly 12,000"

The demand record was actually the least interesting record of the week. Wednesday also set new all-time marks for maximum net load (75,733 MW), maximum solar output (34,665 MW), and — the one that matters most — maximum battery storage discharge at 11,980 MW. Grid analyst Doug Lewin put the trajectory plainly: "Two years ago when the grid reached a new 5-minute peak demand record, we had nearly 4,000 megawatts of batteries deployed. Last night it was nearly 12,000, a 3x increase in 2 years". Batteries topped 10 GW of discharge five separate times in July.

Readers with long memories will recall this newsletter flagging the previous storage discharge record of 11,674 MW. That number is now a footnote. So is the old demand record, and possibly the new one — ERCOT's own outlook has summer peak potentially topping 92 GW, and its odds of a grid emergency jump from 0.21% in July to 5.96% in August.

The structural story is that Texas built roughly 53.6 GW of solar and around 29 GWh of storage, and the two now function as a single machine: solar carries the afternoon, batteries carry the evening ramp, and the heat wave that was supposed to challenge the grid instead produced the quietest record-breaking week in ERCOT history. Two summers ago, 91 GW was a number you modeled in an emergency scenario. This week it was a Wednesday.

Worth sitting with what didn't happen, too. No scarcity pricing event worth the name. No EEA levels. No press conference. The August 2023 record came with conservation appeals and a grid operator visibly sweating; this one came with a market notice and a records table. Every legislative session since Uri has been fought over the premise that the ERCOT fleet can't be trusted in extreme heat. The fleet just served six gigawatts more than it ever has, on the hottest week of the year, without anyone outside the industry noticing. That premise is due for an update.

Hut 8 Fills Beacon Point: 1 GW, $19.6 Billion, One Tenant Unnamed

On Monday, Hut 8 — a company that mined Bitcoin for a living not long ago — announced a second 15-year lease at its Beacon Point campus in Nueces County: 352 MW of IT capacity worth $9.8 billion in base rent, signed with the same unnamed investment-grade hyperscaler that took Phase 1 in May. That tenant now holds 704 MW at the campus, the full 1 GW is commercialized, and the campus-level contract value stands at $19.6 billion — or up to $50.2 billion if all three five-year renewal options get exercised.

Run the arithmetic on the base term and it comes out to roughly $1.3 billion a year across the campus, or something like $1.9 million per megawatt of IT capacity per year, contracted for fifteen years to a counterparty with an investment-grade rating. That is not a hosting deal. That is a utility's revenue profile wearing a data center's badge, and it explains why a company that was mining Bitcoin eighteen months ago now trades like an infrastructure REIT. The market has stopped asking whether miners can convert; it has started pricing which ones did it first.

The press release says "fully commercializes." The subtext says the miner-to-AI pivot is no longer a pivot; it's the business. And it's clustering: two weeks ago MARA agreed to buy a 1,200-acre, up-to-2-GW site from HIF USA one county up the coast in Matagorda, for up to $600 million. Nueces, then Matagorda. A Gulf Coast corridor of former miners selling power-dense real estate to hyperscalers is taking shape, and the common ingredient is not the buildings — it's the interconnection agreements signed back when these were crypto plays and nobody else wanted the power.

Batch Zero Closes Its Window. Now the Studying Starts.

Today, July 24, is the deadline for transmission and distribution utilities to submit their finalized Batch Zero eligibility packages to ERCOT. Load-side submissions closed July 10; deficiency cures run through August 31. After that, the first-ever batch study of the large-load queue — 438,000+ MW, roughly 89% of it data centers — begins in earnest. For scale: the queue is about 4.8 times the all-time peak the grid just served on Wednesday.

What comes out of the study matters more than what went in. Batch Zero sorts every applicant into load classes — the megawatts ERCOT will actually plan for versus the ones that exist mostly as optionality on a developer's term sheet. Everyone in the market privately expects the 438 to shrink dramatically once real deposits and real study costs attach to real projects; the open question is whether it lands near the ~100 GW that planners have been penciling in, or somewhere that forces a rewrite of every transmission plan in the state. The answer starts arriving after August 31.

Two related threads from the regulatory beat. First, the PUCT held a workshop Monday on implementing SB6's mandatory curtailment provisions for large non-critical loads — the fine print that determines whether a 500 MW campus is a grid asset or a grid liability at 5 p.m. in August. Second, the joint PUC/ERCOT ratepayer-protection memo that Governor Abbott ordered by July 17 — the one I noted last issue had not arrived on deadline — still has not surfaced publicly. The next tripwire in the directive is July 31, when the Commission is supposed to initiate action to cut residential transmission costs. One deadline missed, one week to the next.

Meta Buys the Evening Sun, Two Years Forward

Small story, telling shape: on Wednesday GameChange Energy announced it will supply trackers for Sabanci Renewables' Pepper and Lucky 7 solar projects in Texas — roughly 286 MWdc combined, with output contracted long-term to Meta to support its Texas data center load. Commercial operation is slated for the second half of 2027.

Look at what Meta is actually buying: the same resource class that just posted a 34.7 GW output record and carried the grid through its biggest week ever. Hyperscalers watched Wednesday happen too. The difference is they're contracting for it two years forward, project by project, before the batch study tells everyone else what their interconnection is worth.

What to Watch Next Week

July 31. The PUC's deadline under Abbott's directive to initiate action on residential transmission costs — and whether the overdue joint memo ever appears.

Batch Zero cure window. Deficiency fixes run through August 31; watch for any ERCOT signal on how many megawatts actually made it into the study.

TANEO's $350 million. Texas's advanced nuclear fund was slated to pick award recipients in July. Nothing public yet, and July is running out of days.

August heat. ERCOT's own emergency odds go from 0.21% to 5.96% next month. The record set Wednesday may not survive it.

Hut 8's tenant. Q2 earnings season may finally put a name on 704 MW of Beacon Point — and tell us whether the deal-a-week pace of miner-AI conversions holds.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

The Edge Premium Prints at 20%: A 10 MW Deal in Columbus Just Priced the Curve

The most useful number this week is one of the smallest. Duos Edge AI signed an investment-grade hyperscaler to a five-year, 10 MW colocation agreement in Columbus, Georgia worth $111 million — about $2.22 million per MW-year. Set that against the wholesale floor Hut 8 established in May at Beacon Point ($9.8 billion for 352 MW over 15 years, or roughly $1.86 million per MW-year) and you finally have two points on the curve the mid-market has been asking for. The edge premium is real, it is about 20 percent, and it comes with a third of the term commitment.

The rest of the week is the supply chain that feeds that curve: a 400 ksf warehouse conversion in Edgerton, Kansas revived by a city council override; a closed acquisition of a 50-acre, gas-fed site in Hood County, Texas with 17 MW already energized; and a 100-acre joint development agreement at a coal-country business park in eastern Kentucky, assembled around power feasibility before any tenant exists. Under 75 MW, the asset that transacts is not a render. It is power-ready dirt and existing shells.

10 MW, $111M, Five Years: An Investment-Grade Hyperscaler Just Paid Edge Prices in Columbus, Georgia

Duos Edge AI, the edge-colocation subsidiary of Nasdaq-listed Duos Technologies (DUOT), announced a five-year customer agreement for 10 MW of critical IT load at its Columbus, Georgia campus, valued in excess of $111 million and expected to be available in the fourth quarter of 2026. The deal takes contracted capacity at the campus to 20 MW by year-end; the first 10 MW block starts generating revenue in August. Duos recently completed a $55 million raise to acquire the facility outright — it owns the real estate under the contract, which is the whole model.

Do the arithmetic and the story writes itself. $111 million over 10 MW over five years is ~$2.22 million per MW-year. Hut 8's Beacon Point lease — 15-year, triple-net, take-or-pay, high-investment-grade tenant, 3 percent annual escalator — clears at ~$1.86 million per MW-year. Same class of tenant credit, one-thirty-fifth the block size, one-third the paper, and a roughly 20 percent per-megawatt premium for being small, fast, and close to users. Duos specs its modular edge data centers at 100 kW-plus per cabinet and aims to sit within 12 miles of end users; it opened another edge facility in Abilene, Texas on July 14. For anyone underwriting a 10–20 MW build in a tertiary metro, this is the comp you quote.

Deal specs. Sponsor: Duos Edge AI (Nasdaq: DUOT), landlord-operator; tenant an unnamed investment-grade hyperscaler · Site: Columbus, GA, ~100 mi SW of Atlanta; exact parcel n/d · Footprint: n/d (modular edge data-center pods, 100 kW+ per cabinet) · Load: 10 MW critical IT this agreement; 20 MW campus contracted by Q4 2026 · Density: n/d (sf not disclosed); contract comp ~$2.22M per MW-yr · Lease: 5-yr colocation services agreement, escalator n/d, investment-grade tenant · Deal value: >$111M contracted revenue · Source: GlobeNewswire.

Edgerton Overrules Its Own Planning Commission, and a 400 Ksf Conversion Is Back On

On July 16, the city council of Edgerton, Kansas held a special meeting and overrode its own planning commission, which had denied DAMAC Digital Solutions the final site plan for a roughly 400,000 sf warehouse conversion at Logistics Park Kansas City — a project local reporting pegs at $860 million. The commission had approved the initial plans, then balked at the final version after DAMAC failed to answer questions about noise and future expansion; residents raised water and land concerns. Public comment was not permitted at the override meeting. Classic.

The dealmaking lesson sits in the sequence. Conversions of existing shells are the fastest route to capacity in this market, and they live or die on mechanical details — generators, fuel storage, noise attenuation — not the zoning envelope. DAMAC Digital, formerly Edgenex, is the data-center arm of the Dubai property group that pledged $20 billion for US data centers in 2025; it has not disclosed the load for Edgerton. For scale only: at the 120 W/sf mid-market density floor we flagged in a prior issue, 400 ksf would pencil to roughly 48 MW — our arithmetic, not a DAMAC disclosure. A possible city-wide data-center moratorium and zoning rewrite are still on Edgerton's table, which is worth watching more than this one building.

Deal specs. Sponsor: DAMAC Digital Solutions (DAMAC); tenant n/d · Site: Logistics Park Kansas City, within Edgerton, KS city limits, ~30 mi SW of Kansas City · Footprint: ~400 ksf existing warehouse (conversion) · Load: n/d · Density: n/d · Lease: n/d — owner-developer conversion; developer-funded dedicated power per the city FAQ · Deal value: ~$860M project cost per local reporting · Source: DCD.

17 MW Live, 300 MW of Headroom: Big Digital Closes on 50 Acres in Hood County

Big Digital Energy completed the acquisition — through its joint venture with energy-infrastructure firm 10NetZero — of an approximately 50-acre, power-ready industrial site in Hood County, Texas, less than 40 miles from the Dallas–Fort Worth metroplex. The site carries 17 MW of operational power today, and existing on-site natural gas infrastructure supports behind-the-meter expansion the company says could reach 300 MW. Northland Capital Markets has been retained to run financing and customer processes. Hood County has appeared in this newsletter before on the generation side; this is the deal layer catching up — flag it as an update.

Seventeen energized megawatts is not a large number until you compare it with the entitled-but-unpowered pipeline it competes against. In the sub-75 MW band, a controlled site with live power and a gas lateral is worth more than a hundred renderings, and buyers are behaving accordingly: close first, sign tenants second. Purchase price was not disclosed, and no customer is named — which is the point. The asset being traded is optionality with a meter on it.

Deal specs. Sponsor: Big Digital Energy + 10NetZero (JV; split n/d); no tenant yet · Site: Hood County, TX (Granbury area), <40 mi SW of the DFW metroplex; exact parcel n/d · Footprint: n/d (~50-acre industrial site with existing improvements) · Load: 17 MW operational; up to 300 MW potential via behind-the-meter gas · Density: n/d · Lease: n/a — fee acquisition via JV; terms n/d · Deal value: n/d · Source: Big Energy News.

100 Acres, a 69 kV Line, and No Tenant: Coal Country Files Its Off-Grid Paperwork

The Appalachian Industrial Development Authority signed a joint development agreement with Diversified Gas and Oil Corporation and real estate developer Maverick Holdings covering the potential purchase of about 100 acres at the Gateway Business Park near Jenkins, Kentucky, in Letcher County on the Virginia line. The long-term concept, per DCD and local reporting, is a self-sufficient, off-grid power supply feeding an AI data center — with the form of on-site generation still undetermined and engineering feasibility work ongoing. No company has been targeted for the site because it has not yet been deemed viable, though One East Kentucky's chief says the development body has been "inundated" with companies looking for space.

This is the bottom rung of the sub-75 MW ladder, and it is worth watching precisely because it is so early: land control and power feasibility first, buildings later, tenant last. The 260-acre park is served by a 69 kV AEP Kentucky transmission line and Kentucky Frontier Gas, which is more infrastructure than most greenfield AI sites start with. And Kentucky is no longer a hypothetical market — TeraWulf's 401 MW Hawesville campus carries a 20-year, $19 billion Anthropic lease. The option value on 100 entitled acres with gas and wires in that state is not zero.

Deal specs. Sponsor: Diversified Gas and Oil Corp + Maverick Holdings, via joint development agreement with the Appalachian Industrial Development Authority; no tenant · Site: Gateway Business Park, near Jenkins, KY (Letcher County), eastern Kentucky at the Virginia line · Footprint: n/d (pre-development; ~100 acres of a 260-acre park) · Load: n/d — off-grid generation under feasibility study; park served by a 69 kV AEP line and gas service · Density: n/d · Lease: land purchase under joint development agreement; terms n/d · Deal value: n/d · Source: DCD.

What to Watch Next Week

Duos Columbus turns on the meter. The initial 10 MW deployment begins generating revenue in August; DUOT's Q2 print should carry facility acquisition cost detail — the other half of the $2.22M per MW-year math.

Realty Income's Northern Virginia JV. The first of three planned Data Center Alley acquisitions in the Cloud Capital joint venture — a fully leased hyperscale asset in a package reported north of $6 billion — is expected to close in Q3.

The 400 MW Abilene JV paper trail. PowerPlay AI announced a behind-the-meter development in greater Abilene with an unnamed Nasdaq-listed neocloud partner, targeting an initial 400 MW in 2028. Watch for definitive JV documents, site disclosure, and who the partner actually is.

Nebraska's incentive reversal. Governor Pillen is expected to sign an executive order suspending data-center tax incentives — an immediate change to Plains-state site-selection math for any deal that penciled on the credit.

Edgerton's rulebook. The council override settles one building, not the policy. A six-month data-center moratorium and a zoning-code rewrite (fuel storage, noise) remain live possibilities; the next council agendas will say whether Kansas conversions just got harder to underwrite.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

727 to 1: Abbott's Deadline Arrives and Nobody Has Decided Who Pays

Shave one megawatt off your demand at the system peak and Texas will save you money on transmission. How much money depends entirely on what kind of customer you are. For a commercial or industrial customer, the answer is about $68,550 a year. For a residential customer, the same megawatt of avoided peak is worth about $94.

That is a ratio of roughly 727 to 1 for delivering the identical benefit to the grid. The figure comes out of the record in PUCT Docket 58484, and as far as I can tell nobody has put it in front of a trade audience yet. It is the cleanest single expression of the thing Texas spent this week failing to resolve.

Abbott's Deadline Arrived. The Memo Did Not.

Governor Abbott's June 10 directive gave the PUCT and ERCOT until July 17 to deliver a joint memorandum to his office: what they can do under existing authority, where the statute stops them, and what legislation they want. I flagged that clock when it started. It ran out yesterday.

As of this writing I can find no public confirmation that the memorandum was filed or released. That is not necessarily a failure — a memo to the Governor's office is not required to be a public filing, and it may surface next week. But it means the single most consequential document in Texas energy policy right now is one that nobody outside two agencies has read.

What we do know is what Abbott asked for, and it is not subtle. He wants the legislature to codify data-center cost responsibility, to require that large loads "add to capacity, not just demand", to mandate closed-loop cooling, to require annual electricity and water reporting, and — the one that will draw blood — to repeal the data center sales tax exemptions. Texas spent a decade recruiting this industry with tax policy. The Governor is now asking the legislature to take the recruitment tools back.

Separately, the PUCT has until July 31 to initiate action on reducing residential transmission costs. That is nine business days after a deadline it may or may not have met.

Five Dockets, and the One Number That Explains Them

The who-pays question is not being decided in one place. It is spread across five open proceedings, and they interlock in ways that are easy to miss if you only follow one.

58481 is large load interconnection standards — the proposed 16 TAC §25.194, published March 12, carrying the $50,000 per MW security requirement for loads at or above 75 MW. Still proposed. Not adopted. It has been sitting for four months. 58482 is the Large Load Demand Management Service. 58484 is transmission cost recovery, where the 727-to-1 figure lives. 58480 is load forecasting. 58000 is the long-term transmission cost allocation work under SB 6.

The connective tissue is worth noticing: the PUCT has decided to improve its large-load forecasting by incorporating actual baseline usage from Batch Zero projects. Which means the interconnection process I wrote about last week is not just a queue filter — it is about to become the state's primary instrument for finding out what these facilities actually draw, as opposed to what their letters of agreement claim they will draw. Those two numbers have never been the same.

On the size of what is being forecast, the sources disagree and I am not going to pretend otherwise. EDF's July 14 analysis counts roughly 335 data centers operating in Texas with at least 247 in development, and projects state demand rising nearly 60 percent in under four years. Floodlight's reporting a week earlier put it closer to 300 operating and 200-plus in development. Both are defensible depending on where you draw the line on what counts as a data center and what counts as "in development." Neither is small.

The Record That Didn't Happen

Everyone spent the spring being told July would break the ERCOT peak demand record. July is now more than half over and it has not.

ERCOT's summer forecast put the 2026 peak at 92,211 MW, in a range topping out near 98,000. The all-time record remains the 85,508 MW set on August 10, 2023. Last summer's peak was 83,679 MW. ERCOT put the odds of a grid emergency in July at 0.21 percent, and so far the grid has spent the month validating that number rather than the headlines.

The week ending July 10 ran near-record on a weekly average basis at 69.71 GW, against the 69.91 GW record from August 2024, and this week the expectation drops to 63.64 GW as rain moves in. Wind fell back to 12.85 GW for the week after the extraordinary 22.00 GW record two weeks ago, with this week expected near 10.87. Coal is running historically low at around 8.5 GW.

The useful read on load growth is still the temperature-adjusted one: 6.0 percent year over year, with the eight-week average at 4.9. The raw print of 14.3 percent is mostly heat, and anyone quoting it at you without the adjustment is either selling something or has not looked.

None of which means the summer is over. August is when ERCOT records actually get set — the standing peak, the standing weekly average, both are August marks. But it is worth saying clearly, because the incentive in this industry runs entirely the other way: the grid has handled a 60 percent demand-growth narrative, a 438 GW queue and a record-hot stretch without an emergency alert. The crisis everyone is planning around is real in 2029. It was not real this week.

What to Watch Next Week

July 24 is the utility-side Batch Zero deadline. DSPs and TSPs must forward eligibility packages to ERCOT. First real look at how much of the 438 GW queue submitted anything at all.

July 31 is the PUCT's residential transmission deadline. Watch 58484 and 58000 for the opening move — and watch whether the 727-to-1 disparity gets addressed directly or quietly parked.

The Abbott memorandum, whenever it surfaces. It contains the legislative ask for 2027, which means it contains the answer to whether the sales tax exemption survives.

August 7 classification notices, August 31 deficiency cure. The sorting of 438 GW toward roughly 100 happens on that calendar.

Adoption of 16 TAC §25.194 in Docket 58481. Four months proposed and counting. Until it is adopted, the $50,000 per MW number that everyone is planning around is not actually a rule.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

41 Gigawatts in Letters of Agreement: Washington Wires $3.26 Billion Into Texas

The Department of Energy closed a loan of up to $3.26 billion to AEP Texas on July 8. Buried in the announcement is a number that deserves more attention than the loan itself: AEP Texas says it has signed letters of agreement supporting up to 41 GW of potential new load additions through 2030.

That is one utility, in south and west Texas, with signed paper. Set it against the statewide interconnection queue — currently reported at 438 GW — and you have the beginning of an honest credibility filter. The queue is what everyone asked for. The letters of agreement are what somebody actually put a signature on. The ratio between those two numbers is the most useful thing anyone has published this year.

"Texas Is Poised for Incredible Growth Over the Next Five Years"

The financing comes through DOE's Office of Energy Dominance Financing and funds roughly 100 transmission projects across about 2,800 miles of rebuild, reconductor and new line. DOE's claim is that the upgraded infrastructure will carry double the power it does today, and that customers will see about $685 million in savings over 30 years across more than a million AEP Texas ratepayers.

Take the savings figure with the usual caution applied to any 30-year number in a press release. The 2,800 miles is the part that matters. Reconductoring existing corridors is the only way to add meaningful transfer capability in Texas on a timeline shorter than a decade, because it mostly avoids new right-of-way and the condemnation fights that come with it. This is the unglamorous version of grid expansion and it is the only version that arrives before 2030.

This is the third utility financing completed under the program, and AEP's parent took a separate $1.6 billion deal last year. Energy Secretary Chris Wright framed it around AI, advanced manufacturing and the Permian. Note what that list has in common: none of it is residential, and all of it is load that shows up in large blocks with its own lawyers.

"One More Than They Can Effectively Regulate"

Floodlight and the Texas Tribune published the best-reported piece of the month on July 9, and it explains the mechanism underneath every "we're building our own power" announcement of the past year.

Since 2024, at least 38 Texas data centers have obtained minor permits — permits by rule and standard permits — for on-site generation, quietly authorizing more than 2,100 backup diesel generators statewide with no public notice and no environmental review. Those generators are collectively permitted for nearly 2,500 tons of nitrogen oxides a year, which is more than triple what the state's newest coal plant emits.

The threshold-gaming is the part that should end the debate about whether this is accidental. A Cyrus One site in Whitney is permitted at 249.1 tons per year of NOx against a review trigger of 250. A Vantage site outside San Antonio comes in at 99.8 tons against a 100-ton threshold. Vantage started with minor permits for 22 diesel generators and is now seeking more than 80. These are not coincidences; they are engineering to a number.

The OpenAI and Crusoe "Stargate" campus in Abilene is the clearest case. Eleven hundred acres, a 360 MW on-site gas plant, ten turbines and 62 diesel generators already in place, with applications pending for 41 more turbines and 18 more generators. Its current minor permits already allow 1.6 million tons of greenhouse gas annually. Bruce Buckheit, who ran air enforcement at EPA, put it about as dryly as it can be put: "When you get to 62, you start thinking, well, wait a minute, maybe the scale is wrong here."

TCEQ is not positioned to catch up. The agency is carrying more than 1,400 open enforcement cases and resolved 39 last year. Kathryn Guerra, formerly of TCEQ and now at Public Citizen, did the division: "At that rate, it's going to take them 35 years." James Doty, who spent three decades at the agency, offered the sharper structural point — by the time a data center is applying for its operating permit, the siting decision is already made and unwindable.

The line in the headline is Doty's colleague's, and it is the thesis: every permit the agency issues is one more than it can effectively regulate. Texas did not decide to let data centers build their own power plants outside public review. It decided, years ago, on a permitting threshold, and the industry found it.

Disclosure worth carrying: Floodlight notes that Meta and Public Citizen have both been financial supporters of the Texas Tribune.

438 Gigawatts In. About 100 Expected Out.

July 10 was the first hard deadline in the Batch Zero process the PUCT approved in June. Customers had to get their completed election forms to their interconnecting utility by end of day. The utility-side package goes to ERCOT by July 24, deficiencies must be cured by August 31, and ERCOT notifies applicants of classification in August.

The queue figure now in circulation is 438 GW, up from the 410 GW I cited a month ago, with something close to 90 percent of it data center load. That is more than five times the all-time ERCOT peak. ERCOT's own expectation is that roughly 100 GW will meet the Batch Zero criteria — about 23 percent of what is nominally in line.

A caution on that 438: it traces to mid-June and was not refreshed this week, and the queue number has been defined differently at different points this year — 233 GW in December, 238.6 GW in March, 410 GW in June. Some of that growth is real and some of it is definitional. The trajectory is the signal; any single print is not.

The financial security default is $50,000 per MW where specific upgrade costs cannot be determined, applied to loads at or above 75 MW. That is the number that will do the actual filtering, and it is still a proposed rule under Project 58481, not an adopted one.

Context worth holding onto: FERC issued Section 206 show cause orders to all six of its jurisdictional RTOs on June 18, directing them to justify or reform their large-load interconnection rules. ERCOT is exempt, being outside FERC jurisdiction. So the one grid operator that moved first on this problem is the one Washington cannot order to move at all, and its rules are now the benchmark the other six will be measured against. Texas is the control group.

11,674 MW

Batteries set a new hourly dispatch record on July 8 at 11,674 MW, beating the 10,372 MW mark from March 13. Solar set a new weekly average record at 13.84 GW. Coal ran at 9.01 GW and gas at 28.94 GW.

Load ran 14.3 percent above the same week last year, which sounds alarming until you adjust for temperature, at which point it is 6.0 percent, with the eight-week adjusted average at 4.9. Weekly average load came in at 69.71 GW against the 69.91 GW record from August 2024 — near-record for the second consecutive week without touching it.

Two records in one week, both on the supply side, both absorbed without a conservation appeal. The story of the summer so far is not that the grid is straining. It is that storage and solar are quietly doing the work people spent a decade insisting they could not do, while the argument in Austin is about who pays for the wires.

What to Watch Next Week

July 24 is the utility-side Batch Zero deadline. DSPs and TSPs forward eligibility packages to ERCOT. This is the first point at which a real submitted-megawatt total becomes knowable, and the first honest read on how much of the 438 GW was ever more than a spreadsheet entry.

July 31 is the PUCT's deadline to initiate action on reducing residential transmission costs, under Abbott's June directive. Watch dockets 58484 and 58000.

The joint PUCT and ERCOT memorandum to the Governor is due July 17. It is supposed to identify statutory limits and recommend legislation, which makes it the opening bid for the 2027 session.

August 7 brings Batch Zero classification notices — base load, studied load, or excluded. That is when 438 GW starts getting sorted toward 100.

August 17 is when the six FERC-jurisdictional RTOs must respond to the show cause orders. Every response will be read against what Texas already did.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

32 Plants, 287 Million Tons: Somebody Finally Added Up the Texas Gas Buildout

The Environmental Integrity Project published a report on July 1 that did something nobody in Texas had bothered to do: it counted the gas plants. Not the ones utilities are building for the grid — the ones being built to sit behind a data center fence and never touch a wire ERCOT controls. The national number is 74 plants of 100 MW or larger. Thirty-two of them are in Texas, which is nearly half, and more than any other state has.

Those 32 plants, running at maximum permitted capacity, would emit more than 287 million tons of greenhouse gases a year. The report's own comparison is 61 million cars. Mine is simpler: the entire national fleet of 74 plants comes to roughly 662 million tons, which is about what Australia emits annually. Texas is carrying 43 percent of that on its own.

"It Makes No Sense for a Technology of the Future to Be Powered by the Dirty Fossil Fuels of the Past"

That line is from Jen Duggan, EIP's executive director, and it is the kind of quote that gets a report covered. The more useful number is buried further in: alongside the carbon, the 32 Texas plants are permitted for more than 20,000 tons of nitrogen oxides and 14,000 tons of fine particulate matter annually. NOx is the one that matters locally, and West Texas — where a large share of this is going — has thin air monitoring coverage to begin with.

The counties named are Comal, Anderson, Bexar, Pecos and Caldwell. The projects named are the ones you would expect if you have been reading this newsletter: Fermi America's Project Matador near Amarillo, Pacifico's GW Ranch Energy Center in Pecos County, Comstock Resources' Texas Power Generation Hub, the FO Permian Partners complex. Pecos County keeps showing up. It showed up when Microsoft went shopping there in June, and it is showing up here as the site of one of the largest air permits in the country.

Griffin Bird, the report's lead author, made the argument that the industry has the least good answer for: "There is no limit on how much solar can scale up. And it can scale a lot quicker than a lot of the gas-fired power plants that are being proposed." He is right on the interconnection math and wrong on the thing the buyers actually care about, which is firmness at 3 a.m. That tension is the whole Texas power market in one sentence, and neither side is arguing in bad faith.

San Marcos Zones Data Centers Out of Existence

On June 16, the San Marcos City Council voted 4 to 3 to define "data center" in its zoning code and then make it an ineligible use in every single zoning district in the city. Not a moratorium. Not a setback rule. A definitional ban.

This is more dangerous to developers than the county moratoria that have been collapsing under legal pressure all year, and the reason is jurisdictional. Moratoria are temporary by construction and vulnerable under 2025's HB 2559. Zoning is a home-rule municipal power, and 352 Texas cities have home-rule authority. If the San Marcos ordinance survives, it is a template that can be copied by ordinance in an afternoon.

State Senator Paul Bettencourt has said he intends to challenge it, arguing it functions as an indefinite moratorium and therefore violates HB 2559. That is a real argument, and it will get tested. In the meantime, San Marcos told the Tribune that other cities have already called to ask how it was drafted. Nobody wants to be first. Everybody wants to be second.

Six Turbines, No Tenants

Fermi America had a June 30 that is worth watching in slow motion, because the largest single line item in the EIP report spent it fighting itself.

At 8:30 that morning, Fermi announced it had selected Primoris Energy Services for balance-of-plant engineering and construction on the first six Siemens SGT-800 turbines at Project Matador. Read the release carefully and it is a selection, not a signed EPC — the parties will "continue to advance scope, schedule and execution plan toward a final EPC agreement." Primoris has finished the excavation for all six power islands, so there is real dirt moving. There is not yet a contract.

At 4:00 that afternoon, co-founder Toby Neugebauer — who beneficially owns 146.5 million shares and is running a consent solicitation against the board — held a town hall and said, on the record in an SEC filing, that Fermi had internally planned June 30 as "the day that we would announce 2 tenants." No tenants were announced. Of the Primoris release, he said he "almost felt baited."

Treat that framing as what it is: a dissident shareholder's characterization, filed in a proxy fight, not a company statement. But two things are independently verifiable and less arguable. Glass Lewis and Egan-Jones both backed Neugebauer's card on June 29. And on June 30, Fermi filed a notice of non-suit dismissing its own declaratory-judgment action in Texas Business Court, days after the court granted Neugebauer expedited discovery into the board's 70 percent supermajority bylaw. Companies that expect discovery to go well do not usually dismiss the case that produces it.

Matador is an 11 GW behind-the-meter promise. EIP scores it at more than 40 million tons of greenhouse gas per year at full permitted operation, against New York City's roughly 48 million tons across power, transport and waste combined. That is one campus in the Panhandle approaching one of the largest cities on earth. Whether it gets built now depends less on turbines than on whether anyone signs a lease.

KKR Pays $4.2 Billion. A Scurry County Battery Gets a Waiver.

Two filings, two days apart, pointing in opposite directions.

On June 30, KKR agreed to acquire EDF power solutions' North American operations for roughly $4.2 billion in equity value, plus up to $390 million in earnouts. It is the largest single renewable-sector investment KKR has ever made, for a platform that has developed 26 GW in North America. KKR's Cecilio Velasco tied the thesis directly to data center expansion and reshoring. The release does not itemize Texas megawatts, so I am not going to invent a number, but you do not buy a top-ten US renewables platform in 2026 without buying ERCOT exposure.

Also on June 30, Vistra filed an amendment upsizing its revolving credit facility to $5.50 billion from $3.44 billion, releasing all guarantors and removing collateral reinstatement requirements. The largest generator in ERCOT just gave itself two billion dollars of additional unsecured flexibility. Nobody does that to sit still.

And on July 1, Energy Vault disclosed that its Cross Trails project — 57 MW and 114 MWh in Scurry County, inside ERCOT — had entered a consent and waiver with its lenders, who waived default for failing to meet debt service coverage requirements for the quarters ending March 31 and June 30. Two consecutive quarters. The lenders also modified the DSCR methodology through the end of 2027 and lowered the minimum ratios, which is the polite version of moving the goalposts.

So: global capital paid a record price for a renewables platform on a data-center thesis in the same week a merchant ERCOT battery needed a covenant waiver to keep going. Both are true. The spread between them is where the next two years of this market actually lives.

Wind Set a Record. Solar Set a Record. Nobody Noticed.

The week ending July 3 was the grid's quietest strong performance of the year. Wind averaged 22.00 GW over the full week, an all-time weekly record, and way above the five-year range. Solar averaged 12.39 GW, also a record, by nine hundredths of a gigawatt. Coal came in at 7.90 GW, which is historically low, and gas at 22.98 GW.

Weekly average load hit 69.71 GW against a standing record of 69.91 GW from August 2024. It missed by 0.2 GW. Daily peaks reached 82,122 MW on June 30 and 81,759 MW on June 28, the latter running 1.6 percent under forecast.

There were no conservation appeals, no grid watches, no emergency alerts and no scarcity pricing. Prices ran lower on average, and the West and Panhandle zones showed daytime price flatlines from surplus renewables. Raw year-over-year load growth was 11.0 percent; temperature-adjusted it was 5.4 percent, with the eight-week adjusted average at 5.0. That adjusted figure is the honest one. The rest is weather.

Worth stating plainly because the aggregators keep getting it wrong: batteries did not set a record this week. The hourly storage mark is still 10,372 MW from March 13. It came close on Saturday and did not get there.

What to Watch Next Week

July 10 is the Batch Zero customer deadline. ERCOT's legacy large load study process expires at end of day, and Batch Zero takes over on July 11. Projects that want in need their technical studies and documentation to their DSP or TSP by then, with utilities forwarding to ERCOT by July 24. This is the first hard filter on a queue that is nominally north of 400 GW. Watch how much of it actually files.

July 4 is the OBBBA construction cliff for wind and solar. Projects that have not begun construction by Saturday lose the 45Y and 48E runway and face a hard end-2027 placed-in-service date. SEIA counts 200-plus GW of solar safe-harbored through 2030 against only about 23 GW of wind. ERCOT's queue skews solar and storage, so the post-holiday filings will show who made it under the wire.

July 9 is the next PUCT open meeting, the first since June 25. Project 58481 and its proposed $50,000 per MW security requirement for loads at or above 75 MW are still proposed, not adopted. That rule has been sitting since March.

Does anyone sue San Marcos. Bettencourt has promised a challenge. The other 351 home-rule cities are waiting to see whether the ordinance holds before copying it.

Does Fermi land a tenant. June 30 came and went. An 11 GW campus with no anchor lease is a very expensive hole in the Panhandle.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

Build Your Own Grid: Microsoft and Chevron Skip the Wires

Texas spent this week doing two things that look contradictory and aren't. On June 18, the Public Utility Commission approved ERCOT's "Batch Zero" process — the first real rulebook in the country for connecting the wall of data center load now stacked against the grid. Four days later, Microsoft and Chevron announced they would skip that rulebook entirely, building a 2.67-gigawatt gas plant in West Texas that never touches ERCOT at all.

That is the whole story of the AI power era in one week. The state is writing the rules for who gets to plug in, and the largest buyers have already decided not to wait in the line the rules govern. The grid is not the bottleneck, because for the biggest players the grid is no longer the power source.

"Built to Run Independently of the Texas Grid"

Chevron's subsidiary Energy Forge One, alongside Engine No. 1, will build a co-located natural gas plant in West Texas to feed a Microsoft AI campus directly, under a 20-year power purchase agreement announced June 22. The project, internally called Kilby, runs to roughly 2.67 GW of phased capacity and about $7 billion, with first power targeted for 2028 and a final investment decision expected by the end of this year. The turbines come from GE Vernova, with additional capacity from Caterpillar's Solar Turbines, all of it fed by Permian Basin gas sitting more or less underneath the site.

The same day, Microsoft confirmed the load this plant exists to serve: a 2 GW data center campus near Pecos, which it called one of the largest single capacity additions in the company's history. Microsoft is funding the energy infrastructure itself. So this is not two announcements — it is one deal with the wiring shown. Kilby is the power; Pecos is the load; ERCOT is not in the diagram.

For three years the standard move was to argue your way to the front of the interconnection queue. Microsoft and Chevron made the same structural bet everyone else is now making, only bigger and with a balance sheet most developers can't match: build your own generation next to your own demand, and let the grid be a backup you may never call. When a major drills its own gas plant to run a data center, "energy company" and "cloud company" stop being separate businesses.

"An Energy Transformation Unlike Anything We Have Seen Before"

That was ERCOT CEO Pablo Vegas on the day the PUCT approved Batch Zero, making ERCOT the first grid operator in the nation to study large loads in batches instead of one at a time. The process groups every project 75 MW and larger into a single study so ERCOT can size the transmission build against the whole picture at once. The picture is large: the queue now holds more than 438,000 MW of large-load requests, roughly 89 percent of it data centers. Applicants get their classification in August, with the final transmission plan due in fall 2027.

Read the fine print and Batch Zero quietly blesses the Kilby model. The framework carves out a path for customers who want to build their own onsite generation and self-supply, and another for loads willing to be curtailed when the local grid is tight. Texas isn't fighting the build-your-own-grid trend. It is writing it into the rules.

It got to, because nobody could stop it. The same June 18, FERC issued show-cause orders to six RTOs — CAISO, ISO-NE, MISO, NYISO, PJM, and SPP — finding their large-load rules inadequate and giving them 60 days to fix cost allocation and co-location. Notably absent from that list: ERCOT, which sits outside FERC jurisdiction. So while the rest of the country got a federal ultimatum to go design something, Texas had already voted its own version into effect. I flagged the federal cost-allocation fight a few weeks back as the thing Washington couldn't keep ignoring. The shoe dropped — everywhere except the one grid that answers to no one in Washington.

Washington Bets $17.5 Billion on Reactors That Don't Exist Yet

On June 23 the Department of Energy conditioned up to $17.5 billion in loans to accelerate ten large reactors — five loans, each funding a site with two 1.1-GW Westinghouse AP1000s. The money targets the long-lead parts, the reactor vessels and steam generators that take years to forge, with the stated goal of shaving up to three years off deployment. Westinghouse and its partners have to put up $1 billion in equity per project first, which is the part that separates the press release from the groundbreaking.

DOE didn't name the sites, but Westinghouse says it has signed letters of intent with seven potential partners, and the math of AI demand keeps pointing at Texas. The state has its own $350 million nuclear development fund, two operating plants with owners who have openly studied expansion, and the load growth to justify it. None of these reactors will produce an electron before the early 2030s. The deals announced this week — Kilby, the gas plants, the batteries — are what carries the load until then. Nuclear is the bet on the decade after the one we're living in.

The Bill for Going Off-Grid: Ask xAI

One cautionary note for everyone now racing to pour their own gas turbines. On June 15 the Department of Justice moved to dismiss the NAACP's suit against xAI over 27 allegedly unpermitted gas turbines at its Colossus 2 site outside Memphis, arguing in court that shutting them down "threatens American national, economic, and energy security." The plaintiffs want the turbines idled until permits and pollution controls are in place, plus penalties of up to $124,000 per day per violation.

The site is in Tennessee and Mississippi, not Texas, so it doesn't move the ERCOT map directly. But the principle travels. Every behind-the-meter gas deal — Kilby very much included — inherits the same air-permitting exposure the moment it fires a turbine. Chevron and Microsoft have the lawyers and the lead time to permit Kilby properly. The cautionary tale is for the dozens of smaller off-grid projects that will try to copy the model without the same patience, and discover that "skip ERCOT" does not mean "skip the regulators."

What to Watch Next Week

August Batch Zero notifications. ERCOT tells the first cohort of 75-MW-plus projects whether they made the initial study. This is the first official read on which of the 438 GW is real and which is a placeholder.

The 60-day FERC clock. Responses from the six RTOs are due in mid-August. Watch whether PJM and MISO ask for extensions, and read the cost-allocation language closely — that is where the fight over who pays for data center transmission actually gets decided.

Chevron's final investment decision on Kilby. FID is expected by year-end and is not yet locked. If the conditions slip, the flagship behind-the-meter deal wobbles, and a lot of copycat term sheets wobble with it.

The five nuclear sites. DOE still has to pick which of Westinghouse's seven LOIs convert. A Texas site in the final five would put real reactors behind the load-growth story.

The heat. ERCOT is forecasting a summer peak above 92 GW against an all-time record of 85.5. If late-June heat sets a new record, the forecast stops being a forecast.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Credit Is the New Gatekeeper: A 50 MW Reuse in Colorado Springs, and Three Ways to Pay for the Box

The most instructive deal in the inference market this quarter never closed. A well-funded neocloud came to the table with a 15-year term, six months of rent prepaid, millions committed to liquid cooling, and pricing at $155–160 per kW. The colocation providers passed. Not on price — on the tenant. As one broker put it, investment-grade credit is no longer a negotiating point, it is the price of admission.

That is the backdrop for everything that transacted this past week. At the other pole sits Hut 8, which closed $4.25 billion of Baa2-rated senior secured notes for its Beacon Point campus in Texas — its second investment-grade construction bond, bringing project-level IG capital to $7.5 billion. Between the neocloud that got turned away and the miner that raised investment-grade paper before commercial operations, the question for every deal this week was the same: who can actually fund the box. Four sponsors answered it four different ways — by reusing a building, by pivoting a miner, by buying the GPUs outright, and by raising the equity. Geography ran from Colorado Springs to Michigan Center to a European GPU estate now flying a US flag.

Raeden Skips the Queue: 50 MW Into a Building That Already Exists

The cheapest megawatt in 2026 is the one you do not have to wait three years to energize. Developer Raeden understood that when it filed for Project Taurus, a 50 MW data center in Colorado Springs that the city's planning department approved on June 11. There is no greenfield slab here, no eighteen-month shell build. Raeden is taking an existing 451,217-square-foot building on roughly 22 acres at 1565 High Tech Way and converting it, demolishing the smaller outbuildings and the old central utility plant while keeping the box that already has steel, roof, and a foundation.

The density tells the story. Fifty megawatts across 451,217 square feet works out to roughly 111 watts per square foot — a fraction of the 1-plus kW/sf you see on purpose-built liquid-cooled greenfields. That is the trade Raeden made: lower density, but a structure it can power and occupy on a timeline a new build cannot touch. The move also reads as a bet on geography. Denver passed a one-year data center moratorium inside its city limits this May, and the development pressure is sliding south to Colorado Springs, where Raeden — a developer with projects in Phoenix, Indianapolis, Detroit, Greensboro, and Miami — now has an approved 22-acre foothold. A local opposition group had until 5pm on June 22 to appeal.

Deal specs. Sponsor: Raeden · Site: Colorado Springs, CO — 1565 High Tech Way, within city limits, ~5 mi NW of downtown · Footprint: 451 ksf existing building on ~22 acres (adaptive reuse) · Load: 50 MW (~111 W/sf, ~0.11 kW/sf at full utilization) · Lease: n/d — developer entitlement, no announced anchor tenant or term · Tenant credit: n/d · Source: DCD.

A Bitcoin Miner in Michigan Center Tries the Pivot Again — 20 MW, Maybe 52

Hyperscale Data (NYSE American: GPUS) told the market on June 15 that its subsidiary Alliance Cloud Services is in advanced negotiations on a master services agreement for 20 MW of critical AI compute at its Michigan Campus, with the structure to expand to 52 MW in 2028. The economics it floated are aggressive: a 20-year term, including renewals, generating north of $1 billion at 20 MW and roughly $2.5 billion at 52 MW. The first 10 MW would come online within 90 days of signing, the next 10 MW ninety days after that.

This is the miner-to-GPU pivot again — the same trade the market saw in Dowagiac earlier this quarter, now in Michigan Center, about six miles east of Jackson. Hyperscale says it will wind down Bitcoin mining at the campus over several months to free the power for the higher-margin colocation services. Two cautions for anyone underwriting off this. First, it is not signed — management expects execution "in the coming weeks," which is not the same as a lease. Second, the customer is unnamed, and the footprint is undisclosed, so the density that actually matters here is unknowable until the agreement prints. What is disclosed is the runway: the campus could eventually support more than 300 MW, meaning even the 52 MW case uses under a fifth of it.

Deal specs. Sponsor: Alliance Cloud Services (Hyperscale Data, NYSE American: GPUS) · Site: Michigan Center, ~6 mi E of Jackson, MI · Footprint: n/d · Load: 20 MW initial, scaling to 52 MW by 2028 (campus potential 300+ MW); density n/d pending footprint · Lease: master services agreement under negotiation, up to 20-yr incl. renewals; ~$1B (20 MW) to ~$2.5B (52 MW) base-term revenue · Tenant credit: n/d — unnamed customer · Source: SEC 8-K.

Rumble Bought the GPUs Instead of Waiting for Them

The exception to the small-site rule this week is a cross-border M&A close, and it earns its place because it is a multi-site package, not a single mega-campus. On June 17, Rumble (NASDAQ: RUM) closed its acquisition of roughly 85.2% of Germany's Northern Data AG, picking up about 22,000 NVIDIA H100 and H200 GPUs running at roughly 85% utilization, across ten data centers — four of them owned — carrying about 250 MW of current and planned power. For a US platform that has been talking about AI compute for two years, buying an operating GPU estate is a faster path than queueing for allocation behind the hyperscalers.

The angle for a US reader: this is American capital reaching across the Atlantic for inference-ready capacity it cannot stand up fast enough at home, then pointing it back at US demand. Rumble has a multi-year, $270 million dedicated-capacity agreement with Together AI for NVIDIA Blackwell B300 systems, and reorganized into RUM Group on close. Northern Data lifted its full-year revenue guide to €170–190 million from €130–150 million on the strength of the utilization. The individual sites sit well under the 75 MW line; it is the aggregate that crosses it.

Deal specs. Sponsor: Rumble / RUM Group (NASDAQ: RUM) · Site: 10-site portfolio (4 owned), primarily Europe; backstops US compute demand · Footprint: n/d · Load: ~250 MW current + planned across ten sites; ~22,000 H100/H200 GPUs at ~85% utilization · Lease: M&A close — ~85.2% equity stake; $270M Together AI dedicated-capacity agreement attached · Tenant credit: n/d (Northern Data FY26 revenue guide €170–190M) · Source: GlobeNewswire.

$350 Million Is the New Letter of Reference

If investment-grade credit is the price of admission, the neocloud workaround is to raise enough equity that the balance sheet does the talking. TensorWave, the all-AMD cloud, raised $350 million in a Series B on June 10 at a $1.55 billion valuation — more than four times its Series A mark from a year earlier — co-led by Magnetar and AMD Ventures. Having your chip supplier's venture arm co-lead your round is its own kind of credit enhancement, and it is the reason a deal like this clears when the $160/kW neocloud lease did not.

The capital is pointed straight at real estate. TensorWave says it has already secured more than 2 GW of long-term data center capacity, operates an 8,192-GPU MI325X cluster it calls the largest AMD training cluster in North America, and is preparing larger MI355X deployments across several new US data center regions. For colocation operators, the read-through is the point: the neoclouds that get to sign leases in 2026 are the ones who can show up with a fresh nine-figure round and a strategic investor on the cap table, not just a high rent number.

Deal specs. Sponsor: TensorWave (co-led by Magnetar, AMD Ventures) · Site: n/d — MI355X deployments across "several new US data center regions" · Footprint: n/d · Load: 2+ GW long-term capacity secured (portfolio); 8,192-GPU MI325X cluster live · Lease: Series B equity raise — $350M at $1.55B valuation; ~$493M total funding to date · Tenant credit: private / venture-backed neocloud · Source: BusinessWire.

What to Watch Next Week

Project Taurus appeal window. The Colorado Springs opposition group's deadline to appeal the June 11 approval was June 22. Watch whether an appeal was filed and whether it stalls Raeden's reuse timeline — and whether more developers chase Denver's overflow into the Springs.

Hyperscale Data's signature. Management said the 20 MW Michigan master services agreement would execute "in the coming weeks." A signed definitive agreement — with a named or rated customer — would convert an advanced-negotiations press release into an actual lease comp. Until then, treat the $1B figure as a marketing number.

The IG construction-bond template. Hut 8's $7.5 billion of investment-grade, construction-stage notes across River Bend and Beacon Point is becoming a playbook. Watch which other miners-turned-operators try to price IG paper before commercial operations — and at what spread over the 6.129% Beacon Point coupon.

TensorWave's landing zones. With 2 GW secured and MI355X clusters to place, watch which US metros TensorWave actually leases into. AMD-first deployments in secondary markets would be a useful counter-comp to the NVIDIA-dominated absorption numbers.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

The Sorting Begins: Texas Builds the Machinery to Tell Real Data Centers From Paper Ones

For two years the story in Texas has been the size of the number. The interconnection queue crossed 400 GW. The 2032 peak forecast hit 367,790 MW, more than four times the all-time record. Every week brought another gigawatt of data center demand that may or may not exist. The number got so large it stopped meaning anything, which is the problem when roughly 70 percent of the large-load requests are data centers and nobody can tell you which ones are real.

This week Texas started building the machinery to find out. The Public Utility Commission approved a new rulebook for sorting mature projects from paper ones. Congress introduced a bill to settle who pays for the grid those projects need. A developer ordered two gigawatts of gas to skip the queue entirely. And the EIA quietly noted that while everyone argues about future demand, solar is about to outrun coal on the actual grid. The gold rush is over. The sorting has begun.

"The Old, One-at-a-Time Process Wasn't Built for Hundreds of Gigawatts"

On Thursday the PUCT approved ERCOT's "Batch Zero" process, the first batch-study approach to large-load interconnection adopted by any grid operator in the country. Instead of evaluating each large load one at a time, the way the queue has always worked, ERCOT will now study them in grouped batches. Batch Zero applies to loads of 75 MW and greater, and the entry ticket is what matters: a project has to show it already has financing and site control to get in. Paper projects need not apply.

The math behind the reform is the justification for it. ERCOT fielded 225 new large-load requests in 2025 alone, against a legacy system designed for a queue of 40 or 50. Studying them sequentially was never going to clear. The framework also builds in two pressure valves the grid badly needs: a pathway for customers to self-supply with onsite generation, and a pathway for loads that agree to be curtailed when local transmission gets tight. Both reduce the amount of new wire ERCOT has to build for demand that might evaporate.

The timeline is the part to circle. ERCOT says it will notify applicants of their project classification by August 2026, with a final transmission plan to follow in fall 2027. August is the first time anyone outside the data rooms gets a real number for how much of that 400-plus GW is actually financed and sited. Mark it.

Circe Orders 2 GW of Gas and Skips the Line

If Batch Zero is the front door, Circe Energy spent the week walking around the building. On June 16 the developer ordered roughly 2 GW of natural gas generation from Cummins to power a behind-the-meter AI campus in the Permian Basin, a 1,950-acre site built for gigawatt-scale compute. The gensets, a mix of Cummins HSK78 and QSK60 high-horsepower units, ship in phases from later this year through 2030, with the campus energizing in 2027.

This is exactly the behavior Batch Zero's self-supply pathway anticipates, and exactly why that pathway exists. A developer sitting on cheap Permian gas and 1,950 acres does not need to wait for ERCOT to study a transmission upgrade. It can bring its own power, energize on its own schedule, and treat the grid as optional. The Cummins order is the second multi-gigawatt behind-the-meter gas deal in West Texas this quarter. It will not be the last. When the queue takes years and the gas is under your feet, the rational move is to not join the queue.

Washington Decides It Cares Who Pays

The same day the PUCT voted, the cost-allocation fight went federal. Representatives Gabe Evans and Kathy Castor, the ranking member of the House Energy Subcommittee, introduced the bipartisan Ratepayer Protection Act, which would require new loads of 100 MW or greater to pay for the transmission upgrades they trigger rather than spreading the cost across existing customers. It is the federal echo of the argument Texas has been having all year about whether a household's bill should rise to wire up a hyperscaler.

It did not arrive alone. The same week, FERC issued show-cause orders to the ISOs and RTOs, ERCOT included, directing them to address large-load interconnection and cost allocation. With more than 300 data-center-related bills introduced across the country in the first six weeks of the year, the politics have caught up to the megawatts. The open question for Texas is whether a federal 100 MW threshold lands above or below where the state ends up drawing its own line. Two regulators, same fight, and the bill for the buildout is the prize.

While Everyone Argues, Solar Passes Coal

Here is the number that actually moved the grid this month, as opposed to the ones moving through committee. The EIA now projects that ERCOT solar will out-generate coal for the first time ever in 2026, at roughly 78 billion kWh of solar against 60 billion kWh of coal. Through June, wind and solar together supplied 40.2 percent of ERCOT generation, with solar alone covering 27.7 percent of the June peak.

This is the unglamorous counterweight to the demand panic. While 400 GW of theoretical load works its way through a brand-new sorting process, the thing keeping the lights on during a record-demand summer is the cheapest, fastest capacity Texas can build, and it is being built faster here than anywhere else. Roughly 40 percent of all U.S. solar additions this year are landing in Texas. The state that argues loudest about whether the grid can keep up is quietly winning the race to add the supply.

What to Watch Next Week

The August Batch Zero classifications. This is the one. ERCOT's first cut of which projects are mature will be the closest thing we get to a real number for financed, sited data center load in Texas. Watch the total MW that survives, and which named campuses make the list.

FERC compliance. After the June 18 show-cause orders, watch whether ERCOT files a response and whether cost-allocation reform gathers any momentum before summer recess.

The summer peak. Extreme heat in late June or July could break the 85,508 MW record. ERCOT has pegged the odds of a July emergency at 0.21 percent, which is the kind of number that looks small until the afternoon it isn't.

More behind-the-meter gas. Circe and Cummins won't be the last. Watch for additional Permian and West Texas bring-your-own-generation announcements from developers pre-empting the Batch Zero timeline.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Power First, Tenant Later

Three deals defined this week, and they rhyme in a way that should make anyone underwriting mid-market inference pay attention: the power got secured before the tenant did. A Bitcoin miner in southwest Michigan is negotiating to turn its ASICs off and 20 MW of AI colocation on. A regional edge operator in South Dallas drew another $650 million of construction debt to pour a fourth building before it has named who fills it. And a developer signed a 15-year take-or-pay on 210 MW in a southern state it still won't disclose. The scarce asset in 2026 is not the customer. It is committed megawatts and the capital to build them.

That is the through-line for this issue: power-first, tenant-second. The crypto refugees and the secondary-metro colos are absorbing the inference demand the hyperscalers are too big to chase, and they are doing it by locking grid headroom and financing first, then dialing for tenants. Below, the Michigan pivot that priced the week, the Red Oak financing comp, the Applied Digital lease that resets the take-or-pay template, and a Sacramento groundbreaking worth holding for its density floor.

Miners Off, GPUs On: A 20 MW Pivot in Dowagiac Prices the Mid-Market

Hyperscale Data put the marquee small deal on the board June 15, disclosing it is in advanced negotiations through its Alliance Cloud Services subsidiary for a master services agreement to deliver 20 MW of AI colocation at its campus in Dowagiac, Michigan — a Cass County town of about 5,500 roughly 30 miles north of South Bend. The structure is a 20-year colocation services agreement the company values north of $1.0 billion, with the first 10 MW live within 90 days of signing and the second 10 MW ninety days after that.

The tell is what funds it. To free the power, Hyperscale says it will wind down Bitcoin mining at the site over several months — the cleanest expression yet of the miner-to-inference pivot, a company literally switching off the hash to switch on the racks. A flagged 32 MW expansion in 2028 would push the same campus past 52 MW and the contract value toward $2.5 billion. White-space square footage for the 20 MW tranche was not disclosed, so the density everyone wants is, for now, unknowable — but a 20-year colo MSA at roughly $50 million a year per ten megawatts is itself the comp. The customer is unnamed; the megawatts are not.

Deal specs. Sponsor: Hyperscale Data / Alliance Cloud Services · Tenant: undisclosed AI deployer · Site: Dowagiac, MI — within city limits, ~30 mi N of South Bend, IN · Footprint: n/d · Load: 20 MW critical IT (path to 52 MW by 2028; density n/d — white-space sf not disclosed) · Lease: ~20-yr colocation MSA, take-or-pay style, private/undisclosed tenant credit; sponsor is a crypto-pivot · Deal value: >$1.0B over 20 yr · Source: StockTitan.

$650 Million More for Red Oak — and a 60 MW Building With No Name on It Yet

DataBank closed $1.45 billion across two transactions on June 15, and the piece that matters for this audience is the $650 million upsize to its Red Oak, Texas construction financing — roughly 20 miles south of downtown Dallas, inside Red Oak city limits. The upsize, $400 million bank plus a $250 million private placement (DataBank's first), funds the campus's fourth building and adds 60 MW of incremental IT capacity. It lifts total Red Oak financing to $2.65 billion against a campus whose first three buildings already pencil at 180 MW across 600,000 square feet.

Run the math on what's disclosed and you get the comp. The original three buildings blend to 300 W/sf (180 MW over 600 ksf) — a usable density benchmark for new South-Dallas wholesale slab. Total Red Oak financing of $2.65 billion across roughly 240 MW implies about $11 million per MW financed, all-in, on a secondary-metro edge campus. That a regional operator can draw a quarter-billion private placement to pour a 60 MW box before announcing a tenant is the financing story of the week: the capital is underwriting the megawatts, not the lease.

Deal specs. Sponsor: DataBank (DigitalBridge-backed) · Site: Red Oak, TX — within city limits, ~20 mi S of downtown Dallas · Footprint: ~600 ksf across first 3 buildings; building #4 sf n/d · Load: +60 MW incremental (campus to ~240 MW; blended ~300 W/sf on the financed 180 MW / 600 ksf) · Lease: n/a — $650M construction-financing upsize ($400M bank + $250M private placement); tenant n/d · Deal value: $2.65B total Red Oak financing (~$11M/MW) · Source: Construction Review.

210 MW, Take-or-Pay, Site Undisclosed — Applied Digital Resets the Template

This one breaks the under-75 MW rule on purpose, because it sets the comp the smaller deals will price off. On June 8, Applied Digital signed a 210 MW lease at Delta Forge 2, a fifth AI-factory campus in a southern state it declined to name, with a U.S.-based, high-investment-grade hyperscaler — its third lease with the same tenant. The terms are the news: a 15-year take-or-pay structure worth roughly $5.2 billion in base-term contracted revenue, or about $12.7 billion if all renewals run a 30-year term. The lease lifts Applied's contracted book to roughly 1.4 GW and $36 billion.

Strip the headline number to a per-megawatt rate and you get a template any mid-market sponsor can underwrite against: $5.2 billion over 210 MW over 15 years is about $1.65 million per MW per year of base rent, investment-grade, triple-net, take-or-pay. That Applied can sign 210 MW before disclosing the town — the same play, at scale, that DataBank and Hyperscale are running at 60 and 20 — tells you the structure has hardened into a standard. Footprint and square footage weren't disclosed, so density is n/d; the rate, not the rack, is the export here.

Deal specs. Sponsor: Applied Digital (APLD) · Tenant: investment-grade U.S. hyperscaler · Site: undisclosed southern state (sister campus Delta Forge 1 is Boyce, LA) · Footprint: n/d · Load: 210 MW critical IT (density n/d — sf not disclosed) · Lease: 15-yr take-or-pay, triple-net, renewals to 30 yr; investment-grade credit; ~$1.65M/MW/yr base rent · Deal value: ~$5.2B base term (~$12.7B with renewals) · Source: GlobeNewswire.

The Sacramento Density Floor: 18 MW, 150 ksf, 120 Watts a Foot

One to hold for the comp file. Prime Data Centers broke ground last month on SMF02 at McClellan Park, just north of downtown Sacramento, a 150,000 sf build carrying 18 MW. It is not this week's deal, but it is this week's most honest density number: 18 MW over 150 ksf is 120 W/sf, a low-density, air-cooled inference and enterprise-colo profile in a secondary California metro. Set it next to Red Oak's 300 W/sf blended Texas slab and you have the year's spread in two data points — the same workload class can ask for anywhere from a tenth of a kilowatt to a third of a kilowatt per foot, and the difference is cooling, market, and tenant mix, not magic.

For a developer pricing a 10–40 MW secondary-metro build, that 120-to-300 W/sf band is the underwriting range to bracket. Sacramento sits near the floor; South Dallas near the middle. The liquid-cooled hyperscaler boxes that quote north of a kilowatt a foot are a different product entirely — and a different newsletter.

Deal specs. Sponsor: Prime Data Centers · Site: McClellan Park, Sacramento, CA — within metro, ~7 mi N of downtown · Footprint: 150 ksf · Load: 18 MW (~120 W/sf) · Lease: n/d — speculative campus build; broke ground May 2026 · Source: DCD.

What to Watch Next Week

The Dowagiac MSA goes definitive. Hyperscale Data guided "coming weeks" on converting the 20 MW LOI to a signed colocation agreement. Watch the 8-K — and any name attached to the tenant, which would be the first hard credit datapoint on the deal.

DataBank pre-leases building #4. With $650 million now closed on the 60 MW Red Oak addition, the open question is who fills it. A pre-lease announcement would turn the financing comp into a rent comp.

Clay County, Florida zoning vote. A second and final hearing June 23 on a 12-month data-center permitting moratorium in the unincorporated county. A yes closes a Florida secondary submarket; a no opens it.

Oklahoma metro supply. Edmond weighs a moratorium-through-year-end and an Oklahoma County siting meeting lands June 22 — both bear on OKC-metro edge supply for sub-30 MW deployments.

RadiusDC / phoenixNAP close. The Q2 window on the ~26 MW Phoenix I campus (8 MW operating, 18 MW to build) runs out June 30. A completion notice would print a clean sub-30 MW edge comp.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

"Add to Capacity, Not Just Demand": Texas Starts Billing the Data Centers

For three years the only question that mattered in Texas energy was how fast you could build. This week the question changed. On June 10, Governor Abbott told the Public Utility Commission and ERCOT, in writing, that data centers have to pay for their own power — and gave them a calendar. The build-out is no longer the story. The bill is.

Read the three biggest items of the week together and they all answer the same question from different chairs. Abbott says the hyperscalers fund their own infrastructure. Google says fine, we will bring our own gigawatt. And the state of Texas, through its own loan book, just put 456 megawatts of gas on the grid that ratepayers are partly underwriting anyway. Who pays for the power turns out to be the only thing anyone is arguing about.

"Add to Capacity, Not Just Demand": Abbott Sends the PUC a Deadline

The directive is short and the dates are real. Abbott ordered the PUC to require large data centers to fully fund the electric infrastructure built to serve them, so the cost does not land on residential and small-business bills. The PUC and ERCOT have to hand the Governor's office a joint memorandum of additional protective actions by July 17, and the PUC has to start the work of cutting residential transmission costs by July 31. Two deadlines, six weeks out, in an agency that usually measures rulemakings in quarters.

The legislative wishlist attached to the directive is the part the industry will actually fight about. Abbott wants data centers required to "add to the electric capacity rather than just demand," mandatory water-efficient cooling, annual electricity-and-water usage reporting to the PUC, and — the line that will get the lobbyists out of bed — a repeal of the data center sales-tax exemption. Texas spent the last several years recruiting these loads with tax breaks. The Governor is now proposing to bill them for the grid and take the tax break back in the same memo.

This is a different lever than the large-load interconnection mechanics ERCOT has been building all spring. That work was about whether you can get in the door. This is about who pays for the door once you are through it. The two are converging on the same conclusion: the era of the grid quietly absorbing data center cost is over, and the state is going to make the cost-causer carry it.

Google Brings Its Own Gigawatt to Gray County

Six days before the Governor's directive, Google answered the question pre-emptively. On June 4, Google and Intersect Power broke ground on the Meitner Energy Center, a co-located data center and generation complex near Pampa in Gray and Roberts Counties, about 60 miles northeast of Amarillo. Four buildings will draw up to 840 MW, paired on-site with more than 1 GW of wind and solar, 3 GWh of battery storage, and gas for firming. It is Google's first project since closing the Intersect acquisition in March, and it sits inside a $40 billion Texas commitment through 2027.

The cooling number is the one to keep. Meitner is air-cooled — no evaporative towers, water limited to restrooms — which is exactly the box Abbott's water-efficiency line wants every new build to check. Google did not design this campus to comply with a directive that did not exist yet. It designed it because bringing your own generation and skipping the water fight is now the cheapest way to get a yes in Texas. The policy is catching up to the engineering.

The structural bet is the same one every serious hyperscaler in the state has now made: do not wait for ERCOT to be the power source. Co-locate the generation, firm it with gas, air-cool the halls, and present the grid with a campus that mostly powers itself. When the Governor says "add to capacity, not just demand," Meitner is the literal blueprint — 1 GW of new generation showing up alongside 840 MW of new load.

NRG Energizes 456 MW of State-Backed Gas at TH Wharton

The third answer is the one Texas does not usually say out loud: sometimes the state pays. NRG brought 456 MW of new dispatchable gas online at its TH Wharton station in Houston ahead of summer, enough for roughly 100,000 homes at peak. The financing is a $216 million, 20-year Texas Energy Fund loan at 3 percent — about 60 percent of the roughly $360 million build cost, lent by the state at a rate no commercial lender would touch.

NRG is not stopping at Wharton. It is advancing further Texas Energy Fund projects at Cedar Bayou and Greens Bayou, targeting more than 1.5 GW of new Texas gas by 2028. So the same week the Governor told data centers to stop socializing their infrastructure costs, the state's own low-interest loan program quietly put the first of several gas plants into service on terms ratepayers backstop. The principle is "cost-causers pay." The practice, for dispatchable generation the grid badly needs, is more flexible. Hold both thoughts.

The Queue Hits 410 GW. The Peak Forecast Hits 92.2.

The numbers underneath all of this keep getting larger and harder to believe. ERCOT's large-load interconnection queue has crossed 410 GW, roughly 87 percent of it data centers, against a system that has never peaked above 90. One recent cycle added about 140 GW on its own, much of it pushed through Oncor. Some meaningful fraction of that 410 is speculative — the same project counted in three territories, the option nobody intends to build — which is precisely why the cost-allocation fight matters. Make developers fund the infrastructure and the phantom load filters itself out.

On the demand side, ERCOT's seasonal assessment forecasts a record summer peak near 92.2 GW, about 10 percent above last summer's 83,679 MW, while pegging the odds of an emergency at 0.09 percent in June and 0.21 percent in July. A record peak and a rounding-error chance of trouble in the same document. Three summers of new gas, solar, and storage bought Texas exactly the margin it was supposed to. The grid is not the crisis this year. The bill for the next decade of it is.

Riot Doubles Down on Corsicana

The miner-to-AI pivot got another data point. Riot Platforms used its June 9 proxy and a Bernstein conference appearance to advance a $400 million two-story AI and HPC facility at its Corsicana site, and confirmed it is in active talks with multiple hyperscalers to fill the campus's full 756 MW of net capacity. Riot's data-center segment posted a 91 percent operating-lease gross margin in the first quarter, the kind of number that explains why every Texas miner with a substation is suddenly an "AI infrastructure company." KBW toured the site and raised its target to $37. The power was always the asset. Corsicana is just the latest miner to admit the rigs were the placeholder.

What to Watch Next Week

The July 17 memo. The PUC-ERCOT joint memorandum on ratepayer protections is the first concrete sign of how "data centers fully fund infrastructure" becomes an actual rule. Watch the definition of which loads are captured and at what threshold.

The tax-break fight. Repealing the data center sales-tax exemption is the line item with the most powerful opposition. Expect the first trade-group and developer responses, and watch whether Abbott's office softens it before session.

Project 58481. The large-load interconnection rule under 16 TAC §25.194 is expected to land mid-year. The 75 MW threshold and the backup-generation disclosure requirement are the provisions that reshape how campuses like Meitner get sited.

Queue cleanup. How aggressively ERCOT culls speculative load from the 410 GW number will tell you how real the cost-allocation pressure already is. A queue that shrinks is a queue that just got priced.

Meitner's gas terms. Google has not detailed the firming MW or the PPA structure at Meitner. Those numbers will tell you how much grid the largest self-supplied campus in Texas actually leans on when the wind drops.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

Buying Around the Queue: A Lexington Brownfield, a Cedar City Gas Plant, and Amazon Sets the 6% Comp

Five deals closed or cleared this week, in five different states, and not one of them was really about money. Capital is everywhere right now. What these sponsors actually bought was a way around the grid interconnect queue and the zoning counter — the two things capital can't conjure. A Dallas operator paid $29 million for printer-era raised floor in Lexington because it came with a substation and a clean zoning letter. A Utah county green-lit a gigawatt and a half of gas behind the meter rather than make the developer wait in line. Niagara Falls settled a five-year land fight. And Amazon's name let Cipher price 70 megawatts of West Texas debt at six percent flat. The cheap input in 2026 isn't the building or the GPUs. It's having already solved power and permitting.

So this week reads as a single trade run five ways: buy the brownfield, build your own generation, settle the lawsuit, or borrow against an investment-grade offtake. Each one is a different door around the same wall.

$29 Million for 81,000 Square Feet of Printer-Era Raised Floor — Because It Came With a Substation and a Zoning Letter

DartPoints, the Dallas-based colo and interconnection operator, closed its purchase of the former Lexmark campus at 745 West New Circle Road in Lexington for $29 million, with the deal brokered by Lexington's Haymaker Company about six and a half months after the site hit the market. On paper it's a 343,000-square-foot building on 29.5 acres with roughly 81,000 square feet of existing raised-floor data center space. What DartPoints actually bought is the on-site substation and the as-of-right data-center zoning — two line items that would each cost years on a greenfield site, already done.

The density math tells the rest of the story. DartPoints is talking 20 to 30 MW of initial capacity into that 81 ksf of legacy floor, which pencils to roughly 0.3 kW/sf — a printer-cartridge company's idea of dense, not an AI tenant's. That's the point: the raised floor is the cheap part. The buyer is paying for the power interconnect and the entitlement, then re-fitting toward a 70 MW ceiling on its own clock. Lexington's mayor said no city incentives are coming, which is the brownfield trade in miniature: you skip the permit fight, you forfeit the goodwill.

Deal specs. Sponsor: DartPoints · Site: 745 W. New Circle Rd, within Lexington-Fayette city limits (~3 mi NW of downtown) · Footprint: 343 ksf building / 29.5 acres, ~81 ksf existing raised floor · Load: 20–30 MW initial, ~70 MW long-term (~0.3 kW/sf on the legacy floor at 25 MW) · Lease: fee-simple acquisition, brownfield redevelopment, as-of-right zoning, on-site substation; no tenant signed · Deal value: $29M, closed May 2026 · Source: PR Newswire.

Cerebras Takes All 40 MW in Columbiana, and Digi Power X Pre-Buys the GPUs to Fill It

Digi Power X committed $35 million to NVIDIA's Vera Rubin rack-scale systems on June 3, the demand-side bookend to the 40 MW campus it's building in Columbiana, Alabama — about 30 miles southeast of Birmingham in Shelby County — under a roughly $1.1 billion colocation master services agreement with Cerebras Systems signed in early May. It's a clean look at how a sub-50 MW Southeast secondary-market build gets financed and filled at the same time: anchor the whole campus to one colo tenant, then self-fund a GPU fleet for your own neocloud platform on top.

The campus comes in halves — 15 MW ready-for-service by December 15, 2026, the full 40 MW by the end of Q1 2027 — with the on-site substation and an Alabama Power delivery agreement already locked, which is why this one doesn't show up on anyone's queue-anxiety list. Digi says it had about $150 million in cash as of June 3 and has already put roughly $65 million into the Alabama site this year, all from its own balance sheet. The Cerebras agreement runs ten years with a seven-year extension option, which would carry total contract value toward $2.5 billion.

Deal specs. Sponsor: Digi Power X (NASDAQ: DGXX) · Tenant: Cerebras Systems (40 MW colo) + Digi's own NeoCloudz GaaS · Site: Columbiana, AL — ~30 mi SE of Birmingham, Shelby County · Footprint: n/d · Load: 40 MW (15 MW RFS Dec 2026; full 40 MW by Q1 2027 end) · Lease: 10-yr colo MSA + 7-yr extension option, escalator n/d, private AI tenant · Deal value: ~$1.1B MSA (up to ~$2.5B with extension); $35M GPU commitment · Source: Blockspace.

Cedar City Says Yes to 1.5 Gigawatts of Gas — Behind the Meter, Around the Queue

The Iron County, Utah planning commission unanimously approved a conditional-use permit for Pronghorn Development's Antelope Data Campus, roughly eight miles west of Cedar City — and the structure is the news, not the acreage. Rather than join an interconnection queue, Pronghorn intends to build up to 1.5 GW of on-site natural-gas generation behind the meter. The campus is entitled for as much as 6.75 million square feet across five buildings on 640 acres, phased over eight to ten years. No tenant has been named.

The permit also threaded a needle: the county had a 180-day moratorium on AI data centers in place, and staff ruled this application predated the pause, so it moved forward anyway. For developers chasing power-constrained Mountain-West geographies, the build-your-own-gas-plant model is the workaround to watch — it converts a multi-year grid wait into a self-funded generation project, with all the fuel-supply and emissions exposure that implies. Local coverage of the June approval notes the months of debate it took to get there.

Deal specs. Sponsor: Pronghorn Development LLC (Project Antelope) · Site: ~8 mi W of Cedar City, UT, Iron County (rural exurban) · Footprint: up to 6.75M sf at buildout, 5 buildings on 640 acres · Load: up to 1.5 GW on-site gas generation; campus IT load n/d · Lease: conditional-use permit approval, behind-the-meter self-generation; no lease or tenant disclosed · Deal value: n/d · Source: KSL.

A Five-Year Eminent-Domain Fight Ends in Niagara Falls, and 1.23 Million Square Feet Gets a Green Light

The Niagara Falls, New York city council voted June 3 to approve a settlement with Niagara Falls Redevelopment, ending a dispute that dated to 2021 and clearing the path for the $1.48 billion Niagara Digital Campus — a privately funded, downtown-infill build on 53 acres NFR already owns, developed with Toronto-based Urbacon. As a deal it matters less for raw megawatts, which weren't disclosed, than for what unlocked it: the binding event was a courthouse settlement, not a substation or a financing close. NFR donates a parcel to the city and the city pays NFR upward of $4 million for costs.

The plan is 1,232,715 square feet across eight two-story buildings and one single-story building, in the urban core rather than on the exurban edge. The lesson for the Northeast is that the gating item is increasingly entitlement and litigation risk, not power availability. New York also has a statewide posture tightening around data centers, which makes a settled, land-already-owned, privately financed campus a comparatively rare clean path. The June 3 vote came out of a contentious council meeting.

Deal specs. Sponsor: Niagara Falls Redevelopment + Urbacon (Toronto developer, US site) · Site: downtown Niagara Falls, NY (Falls St / John Daly Blvd), 53 acres, urban core · Footprint: 1,232.7 ksf — eight 2-story + one 1-story building · Load: n/d · Lease: litigation settlement / land deal (NFR donates parcel; city pays ~$4M costs); privately funded, no tenant · Deal value: ~$1.48B project cost · Source: WGRZ.

Amazon Backs 70 Megawatts in Andrews County, and Cipher Prices Debt at 6%. That's the Comp Now.

One deal this week broke the sub-75 MW frame on purpose, and it's here because it sets the spread the smaller stuff now prices against. Cipher Digital — the former bitcoin miner Cipher Mining — priced $810 million of 6.000% senior secured notes due 2031 on June 9, at 99.750 of par, through a single-asset SPV called Stingray Compute LLC. The notes fund the 70 IT MW Stingray facility in Andrews County, Texas, and the reason a former miner can print investment-grade-style paper is sitting in the lease: the site is fully pre-leased to Amazon Data Services on a 15-year triple-net, with annual escalators, an Amazon.com parent guarantee, and provisions for Amazon to cover construction overruns above a cap.

That is the whole point of including it. A 6.000% coupon on a single-asset data-center build is the number every uncontracted neocloud financing now gets measured against — and most of them won't get within 200 basis points of it, because they don't have an Amazon guarantee stapled to the offtake. The notes are expected to close June 15, with roughly $61.5 million of proceeds reimbursing prior equity. Cipher's pricing release has the structure; DCD has the AWS relationship.

Deal specs. Sponsor: Cipher Digital (NASDAQ: CIFR) via Stingray Compute LLC · Tenant: Amazon Data Services (parent guarantee from Amazon.com) · Site: Andrews County, TX (~within Andrews city orbit, West Texas) · Footprint: n/d · Load: 70 IT MW · Lease: 15-yr triple-net, annual escalator, overrun-cap provision, investment-grade tenant · Financing: $810M 6.000% senior secured notes due 2031 at 99.750, close expected June 15 · Source: GlobeNewswire.

What to Watch Next Week

Cipher / Stingray notes close. The $810M 6.000% notes are expected to settle June 15. Watch the final book and whether the Amazon-anchored print actually tightens — or just exposes — comps for uncontracted neocloud paper.

Lexington, KY planning commission. Public input on a new data-center zoning amendment is set for June 11, which bears directly on whether DartPoints can scale the Lexmark site toward its 70 MW ceiling without a fight.

Fayetteville, AR council. An ordinance moving data centers from permitted to conditional use is on the agenda, with a possible vote as soon as June 16 and an emergency clause that would make it immediate. A bellwether for as-of-right erosion in mid-size metros.

Clay County, FL moratorium. A final hearing on a one-year permitting pause in unincorporated county lands around June 23 — another data point in the local entitlement squeeze.

Illinois incentive pause. The state's halt on new Data Center Investment Program agreements takes effect July 1. Expect a few deals racing to grandfather in before the window shuts; existing agreements are honored.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

438 Gigawatts, and Who Gets to Say No

ERCOT spent this week doing two things at once that do not obviously fit together. On Tuesday it told everyone the grid will sail through a record summer. On Monday and Tuesday its board voted to ration access to that same grid, because the queue of people who want on it has reached a number that is not real. The summer peak it is planning for is 92,211 MW. The data center load that asked to interconnect in the first few months of this year is 438,000 MW. One of those numbers is a forecast. The other is a fantasy with a cover letter.

That gap — between what Texas can deliver and what Texas has been asked to deliver — is the whole story right now, and this week it turned into a question about authority. Who gets to say yes. Who gets to say no. ERCOT is building itself a triage desk. Hyperscalers are routing around the desk entirely by bringing their own generation. And the communities at the bottom of the stack are discovering, in El Paso and in Hood County, exactly how little "no" they actually own.

92,211 MW, and ERCOT Is Calling Its Shot

Start with the number ERCOT actually stands behind. In its summer outlook released June 3, the grid operator forecast an all-time peak of 92,211 MW, nearly 10% above last summer's 83,679 MW and about 8% above the standing record of 85,464 MW set in 2023. And then it did something it has not done comfortably in years: it said the grid will hold. ERCOT puts the probability of a grid emergency at 0.09% in June and 0.21% in July, on the strength of roughly 11 GW of new capacity — overwhelmingly solar and batteries — added in the last few months.

The composition of the record is the part worth sitting with. This is not an air-conditioning peak inching up with the heat index. ERCOT attributes the growth to industrial load — crypto mining, oil and gas electrification, LNG export terminals, and data centers. The Texas peak has stopped being a weather event and become a balance-sheet event. That is good news for anyone selling firm capacity into ERCOT and a structural problem for anyone who assumed the demand curve would behave like it did in 2015.

438 GW Walked In. ERCOT Built a Door.

Here is the number nobody stands behind. In the first few months of 2026, nearly 200 data centers and large users asked to connect to the Texas grid, seeking a combined 438 GW — more than five times the entire state's record demand. ERCOT will tell you plainly that most of it will never be built. The problem is that under the old individual-study model, the speculative requests and the real ones moved through the same pipe at the same speed, and the pipe stopped working.

So on June 2 the board voted to approve the framework that allocates transmission capacity only to large loads that are, in ERCOT's words, "studied and committed" — a batch-study process that screens for the unglamorous evidence a project is real: site control, financing, an actual customer. The framework now goes to the PUCT for final sign-off. Strip away the procedure and the meaning is blunt: ERCOT has appointed itself the body that decides which AI ambitions get to count. When the queue is five times the grid, gatekeeping is not bureaucracy. It is the product.

Air-Cooled and Half Off-Grid: Google Builds Its Own Yes

If the queue is the bottleneck, the obvious move is to skip the queue. On June 4, Google and Intersect Power broke ground on the Meitner Energy Center in Gray and Roberts Counties, a Panhandle data center co-located with more than 1 GW of wind, solar, storage, and on-site gas for firming. It is the first project since Google closed its roughly $4.75 billion acquisition of Intersect in March, and the second Google-Intersect co-location in Texas after the Haskell County solar-and-storage build.

The design reads like a checklist of every objection Texas data centers have collected over the past year. It is air-cooled — restroom-level water use, in a region where water is the fight. It comes with an 800-acre workforce hub for up to 3,500 construction workers and a $10 million Texas Water Impact Fund. Google is not just building the power next to the load to dodge the interconnection queue. It is pre-buying the social license to dodge the second queue — the one made of neighbors. Build your own generation, build your own goodwill, and you never have to ask ERCOT or the county for permission you might not get.

El Paso Tries to Take a Yes Back

Which brings us to the neighbors, who are done asking nicely. On June 2, El Paso District 2 representative Josh Acevedo put an item on the June 9 council agenda to terminate the Chapter 380 incentive agreement with Meta for its $10 billion data center in Northeast El Paso. The facility broke ground last October and is designed to run behind-the-meter on 366 MW from 813 modular gas generators — roughly $473 million of equipment — for a five-year bridge period before any grid connection.

The city pushed back within 24 hours, warning that tearing up an executed agreement has no clear legal basis and could expose taxpayers to more than $1 billion in liability. This is a different animal than the zoning fights and one-year moratoriums we have covered before. Those were communities trying not to say yes. El Paso already said yes, in writing, and is now trying to find the unsay button. The behind-the-meter gas — 813 engines running off-grid in a city with air-quality problems — is what turned an incentive deal into a recall campaign. The vote is June 9.

Hood County Has No Off-Switch to Reach For

El Paso at least has a contract to fight over. Hood County has almost nothing. The Texas Tribune this week mapped eight proposed data centers across more than 7,600 acres — roughly 12 square miles — of the rural county southwest of Fort Worth. The flagship Comanche Circle development and its two siblings could draw up to 3 GW at full build, enough for about three million homes, and would need a 95-million-gallon initial fill plus 150,000 gallons a day after that. Hood County now ranks sixth among Texas counties by planned data centers.

The commissioners court rejected a development pause, and here is the thing: even if it had wanted to stop the projects, it largely cannot. Texas gives unincorporated counties almost no zoning authority. This is not an oversight developers are exploiting by accident — it is the entire reason rural, unincorporated land is the preferred address. Google picked unincorporated Panhandle counties for Meitner for the same structural reason. The places with the least power to say no are, predictably, the places being asked the loudest. That is not a coincidence. That is the siting strategy.

What to Watch Next Week

El Paso council, June 9. Acevedo's motion to kill the Meta agreement either dies in committee, gets tabled, or forces the city to litigate its own incentive deal against that $1 billion liability warning. Whatever happens, it sets the template for every Texas city that wrote a Chapter 380 check it now regrets.

The PUCT's move on Batch Zero. The board approved the framework; the Commission has to finalize it. Watch for the feasibility criteria — exactly how much site control and financing a project must show to keep its place — and how fast the 438 GW gets winnowed once the screen is live.

SB6 final rule. The large-load interconnection rule under Project 58481 is on track for adoption by mid-year, including the 75 MW threshold and the $50,000-per-MW non-refundable fee. That fee is the cheapest, bluntest filter ERCOT has — watch how much of the speculative queue simply declines to pay it.

The first real heat. June and July will test the 92,211 MW forecast against actual load, and the roughly 15 GW of installed batteries against the moment they were built for. ERCOT called its shot in public. The thermometer gets a vote.

County zoning authority. Hood County's powerlessness is becoming a legislative talking point. Watch for noise about giving counties large-load review authority ahead of the 2027 session — the single change that would most alter where these projects get built.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

The Week the Grid Said No: 900 MW Dead, a Year-Long Freeze, and a $14.5M Exit

Some weeks the news is what got built. This week the news is what got killed. A 900 MW campus in Hanover County died on a 4-3 vote. Central Arkansas froze new data centers for a year. A 2.6 million-square-foot adaptive-reuse in the Lehigh Valley got denied from the bench. And the only clean transaction that printed was a Singapore REIT walking away from a powered-but-stranded Philadelphia box for $14.5 million, because it couldn't get the megawatts to make the building worth keeping.

The 2026 bottleneck was never money and it was never chips. It is the social license to interconnect, and this week proved it is getting harder to buy at any proffer price. So capital did the rational thing: it refinanced the megawatts it already controls, dumped the ones it can't make denser, and kept the genuinely new builds small enough to fly under the zoning radar. Here is the week, lead with the deal that actually closed.

$14.5 Million for a Box That Can't Get Bigger: Mapletree Exits Byberry at a Premium to Book

Singapore's Mapletree Industrial Trust signed a PSA to offload its vacant two-story data center at 2000 Kubach Road, in far Northeast Philadelphia's Byberry West Industrial Park, for $14.5 million — a 4.3% premium over the asset's $13.9 million March-31 book value. On paper that is a win: a vacant 1993-vintage building, dark since the last lease rolled off at the end of 2024, sold above carrying value. Read the manager's own language and it is something colder.

Mapletree cited "lengthy lead times to secure higher power capacity" and construction risk as the reason it could not reposition the asset. Translation: the building has a slab, a roof, and a fiber path, but no realistic route to the density a 2026 tenant demands, and the cost of getting there made redevelopment a worse bet than a clean exit. That is the tell of the cycle. Powered-but-underbuilt legacy boxes without a credible path to higher kW are no longer redevelopment plays — they are inventory you sell to someone with a higher risk appetite, at roughly $117 a foot on net lettable area. The premium-to-book headline is the polite version of "we're out."

Deal specs. Sponsor: Mapletree Industrial Trust (seller); buyer undisclosed · Site: 2000 Kubach Road, Byberry West, far NE Philadelphia, within city limits (~15 mi NE of Center City) · Footprint: ~124 ksf two-story on ~25 acres freehold · Load: n/d (power-constrained, vacant since end-2024) · Power density: n/d · Lease: outright asset sale, vacant possession, ~$117/sf · Deal value: $14.5M (4.3% premium to $13.9M book) · Source: DCD.

Hanover Says No to 900 MW: Tract's $21 Million in Proffers Wasn't Enough

This one is over our usual 75 MW line, and it belongs here for a single reason: it is the benchmark that prices everyone else's land. On May 28 the Hanover County, Virginia Board of Supervisors voted 4-3 to reject Denver-based Tract's rezoning for the 900 MW, ~430-acre Mountain Road Technology Park near the Henrico line — roughly 20 miles northwest of downtown Richmond. Tract did not lose on price. It stacked more than $21 million in proffers onto the application — a $15 million pump station and water tank, $6 million for conservation and parks — and still couldn't clear a suburban board staring at 600,000 gallons a day of average water draw, two million at peak.

When a developer puts eight figures of community infrastructure on the table for entitlement and the answer is still no, the marginal cost of the next exurban-NoVA megawatt just went up for everyone. The story for the mid-size operator is the spillover: deals that would have penciled in Hanover or Henrico now go shopping in secondary metros with slack utilities and boards that haven't yet learned to count gallons. The Hanover vote is a ceiling, and ceilings are comps.

Deal specs. Sponsor: Tract (Denver powered-land developer) · Site: 13074 Mountain Road, western Hanover County, VA, near the Henrico line (~20 mi NW of downtown Richmond) · Footprint: ~430 acres entitled (building sf n/d) · Load: 900 MW planned · Power density: n/d (building sf not disclosed) · Lease: rezoning application — denied 4-3 · Other: ~$21M in proffers; 600k gal/day avg water, 2M peak · Source: DCD.

A One-Year Freeze in Little Rock — and Why Being Already in the Queue Just Got Valuable

On May 26 the Pulaski County, Arkansas Quorum Court enacted a 12-month moratorium on new data centers across greater Little Rock. The interesting part is the amendment: the court grandfathered two existing proposals it had only learned about at the early-May agenda meeting, where AVAIO Digital, Entergy Arkansas, and Central Arkansas Water all presented and at least one justice of the peace called the developers' answers "evasive."

For dealmakers the lesson is clean. Optionality on entitled or in-flight sites just repriced upward, because late entrants in Central Arkansas are locked out for a year while the two grandfathered projects keep their place. Site control with a live application is no longer just a head start — in a moratorium county it is the only ticket in the building. Expect to see "already in process" show up as a line item in how powered land gets marketed for the rest of 2026.

Deal specs. Sponsor: Pulaski County Quorum Court (ordinance); developer referenced: AVAIO Digital; utility: Entergy Arkansas · Site: Pulaski County, AR (greater Little Rock) · Footprint: n/d · Load: n/d · Power density: n/d · Lease: 12-month moratorium with grandfather carve-out for two pending projects · Source: THV11.

Hut 8 Cuts Its Bitcoin Loan to 7%, Frees $260 Million, and Backstops a $16.8 Billion Lease Book

If you couldn't close new megawatts this week, the next-best move was to make the ones you already control cheaper to hold. On May 27 Hut 8 refinanced its Bitcoin-backed credit facility into a $200 million, 364-day line with FalconX at a fixed 7.0% — 200 basis points below the prior Coinbase facility — and released roughly 3,300 BTC, about $260 million of collateral. The same disclosure reaffirmed $16.8 billion of contracted AI lease revenue across the company's hyperscale book, anchored by the 352 MW Beacon Point campus in Nueces County, Texas and the 245 MW River Bend site.

This is the crypto-pivot playbook running exactly as designed. Use cheap, BTC-collateralized bridge capital to fund AI build-out instead of diluting equity into a soft tape, and let an unnamed high-investment-grade tenant's contracted cash flows carry the story. The interesting number isn't the $200 million — it's the 200 basis points. When a miner-turned-landlord can shave its cost of bridge capital that fast, the financing market is telling you it still believes the AI lease book even in a week when the zoning market doesn't. The full facility terms are in the release.

Deal specs. Sponsor: Hut 8 Corp. (borrower); FalconX (lender, replacing Coinbase Credit) · Site: corporate facility; underlying book includes Beacon Point, Nueces County, TX · Footprint: n/a (financing) · Load: 597 MW contracted (352 MW Beacon Point + 245 MW River Bend) · Structure: $200M, 364-day BTC-backed revolver, fixed 7.0% (down from 9.0%), ~3,300 BTC / ~$260M freed · Tenant credit: unnamed high-investment-grade hyperscaler · Deal value: $16.8B contracted AI lease revenue referenced · Source: PR Newswire.

200 Kilowatts, Zero Water, on Leased School-District Land: The Edge Playbook in Lubbock

Here is the week's one genuinely new build, and it is the opposite of everything above. On May 28 Duos Edge AI cut the ribbon on two modular edge data centers near 19th Street and Avenue Q in central Lubbock, Texas — its fifth Texas market after Corpus Christi, Victoria, Amarillo, and Waco. Total capacity: 200 kilowatts, what the operator's own VP of technology compared to the draw of a McDonald's. Fifteen rentable cabinets, air-cooled, no water meter, no pipes, sited deliberately close to the grid tie so it doesn't load the neighbors.

This is why the sub-megawatt edge model keeps clearing while the 900 MW campuses get voted down. Nobody packs a zoning hearing over 200 kW. There's no water fight when there's no water. The land is a ground lease from Lubbock ISD — the school district confirmed it is the landlord, not a customer — which keeps Duos's capital light and its siting flexible. Two pods at roughly a million dollars each is a rounding error next to Beacon Point, but it is a deal that actually opened this week, and Duos has five more Texas open houses booked through July plus a Savannah, Georgia expansion. In a week defined by the word no, inner-ring edge is where yes still lives. The Lubbock opening is the template.

Deal specs. Sponsor: Duos Edge AI (Duos Technologies Group, Nasdaq: DUOT) · Site: 19th St & Avenue Q, central Lubbock, TX, within city limits; land leased from Lubbock ISD · Footprint: two modular pods, 15 cabinets (sf n/d) · Load: 200 kW (0.2 MW) max; ~13.3 kW/cabinet · Power density: n/d (sf not disclosed) · Lease: ground-lease tenant; retail colo — space + conditioned power + cross-connect · Tenant credit: small-cap Nasdaq operator; colo customers n/d · Deal value: ~$1M+ per pod · Source: KCBD.

What to Watch Next Week

Walton County, FL takes a first reading on an outright AI data-center ban June 9. Commissioners directed staff to draft a ban before any project has even been proposed. Watch whether they get it on the books ahead of the July state-AI-law preemption that could strip local authority.

Iron County, UT votes on the 640-acre Pronghorn/Antelope project June 4. It moves as a grandfathered project under the county's new 180-day moratorium, but water rights in Basin 71 are already fully appropriated — the supply question, not the zoning, is the one to read.

Ohio's Tax Credit Authority holds its June 1 meeting before Governor DeWine's sales-tax-exemption pause bites. The exemption cost the state $1.6 billion in 2025, roughly eleven times the original estimate. Expect a rush of last-minute approvals and watch the Select Committee on Data Centers' testimony schedule for where the next incentive regime lands.

RadiusDC's phoenixNAP acquisition is expected to close in Q2. A sub-75 MW metro-edge M&A — the Phoenix campus scales toward ~26 MW — that sits squarely in this newsletter's beat. Watch for the closing announcement and any disclosed price; mid-market colo comps are scarce and this one would set one.

Stack Infrastructure's Berry Hill site in Pittsylvania County, VA hits a land-closing milestone. The performance agreement cleared in mid-May; the first 1,000-plus-acre phase must close by June 2027. Watch the tax-abatement conditions and any phased-MW disclosure that would set a Southside Virginia benchmark — the secondary metro that catches Hanover's spillover.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to The Grid Report

238 Gigawatts on Paper, $100 Million in Federal Court

ERCOT's large-load interconnection queue closed May at roughly 238,000 megawatts, north of 70 percent of it data centers. On Wednesday, a developer in Hill County took $80 million of land, 1,235 megawatts of planned load, and a one-year county moratorium and filed all three of them in U.S. District Court in Waco. The complaint calls the county's freeze "illegal under Texas law." It is asking a federal judge to say so.

This is the gap the rest of the year is going to be about. ERCOT has a paper queue an order of magnitude larger than the grid can serve. Counties are starting to use their zoning authority to slow it down. The grid operator is about to chop the queue with a one-shot Batch Zero filing window. Turbine OEMs are sold out past 2029. And the developers that are actually going to energize something in 2026 are the ones writing $96 million preferred-equity checks and buying combined-cycle sets off the shelf.

Five stories from the past seven days, all pointing at the same thing: the difference between what's announced and what's built keeps getting wider, and the people closing that gap are doing it one ITC transfer and one Siemens SGT800 at a time.

"Illegal Under Texas Law": RCM Hill Drops a $100 Million Federal Complaint on Hill County

RCM Hill, LLC filed suit Wednesday in the Western District of Texas, Waco Division, against Hill County and its five commissioners over the county's May 12 data-center moratorium. The developer says it has spent more than $80 million assembling 800-plus acres across four landowner contracts at roughly $100,000 an acre, plus another $1 million in due diligence, to site a 1,235 MW campus it calls Project Aquila. The complaint asks for damages "in excess of $100 million" and a preliminary injunction against the moratorium.

The legal theory is the interesting part. RCM Hill is arguing the freeze is a regulatory taking under the Fifth and Fourteenth Amendments, that the county exceeded its statutory authority under the Texas Local Government Code, and that the moratorium's stated public-purpose findings are pretextual. Senator Paul Bettencourt has already sent a letter to Attorney General Ken Paxton asking him to weigh in on whether the county had the authority to do this at all. Paxton has not responded publicly.

I covered the Hill County pushback five weeks ago as a community-pressure story. That framing is now obsolete. Once a developer puts $80 million of dirt and a 1,235 MW load number into a federal complaint, you are not in NIMBY-meeting territory anymore. You are in precedent territory. Every developer with a county-jurisdiction site in Texas is going to read this docket. So is every county commissioner who was thinking about copying the Hill template.

The relevant question for the rest of us is what happens to the Provident Data Centers site in Hillsboro, the 300-acre project whose announcement triggered the moratorium in the first place. The City of Hillsboro is still working on a 1,000-foot residential buffer rule. Hill County is now defending its moratorium with public funds. The Aquila land is still under contract. Watch the docket.

Batch Zero: 64 Days to ERCOT's Queue Reset

While Hill County argues about whether 1,235 MW can be built at all, ERCOT is about to start telling 238,000 MW of queue submissions which of them get a study slot. The mechanism is PGRR145 and NPRR1325, the Large Load Interconnection Study rule that came out of SB 6. The dates are now load-bearing.

The ERCOT Board of Directors is scheduled to take a final vote on June 1. If it passes, the protocol goes effective August 1. Between those dates, the calendar runs on rails: July 10 is the last day for Large Load Interconnection Study approvals under the legacy process, July 24 is the Batch Zero submission cutoff, and August 7 is when ERCOT classifies each Batch Zero project as either fast-tracked, deferred, or sent back to the line. Developers who do not file by July 24 will not get a 2026 slot.

The May 21 Large Load Working Group meeting was the dress rehearsal. ERCOT's own April Board update says only 9,062 MW of large load has actually been approved to energize in the past twelve months, against the 238 GW queue and a non-simultaneous peak large-load consumption observation of roughly 3,900 MW. So roughly 4 percent of the queue gets a green light, 2 percent shows up on the meter, and the rest is paperwork that Batch Zero is about to triage.

This is the policy lever everyone in the industry has been asking for since SB 6 passed. It is also a real-money event for developers who have been free-rolling submissions to hold position. After July 24, the option premium on a speculative queue spot goes to zero.

$450 Million for Red Egret. 600 MWh on the Ship Channel.

Spearmint Energy closed roughly $450 million in financing this week on Red Egret, a 300 MW / 600 MWh standalone battery project in Texas City targeted for 2027 commercial operation. The capital stack tells you exactly what BESS finance looks like in 2026: a $225 million construction facility led jointly by First Citizens Bank and Investec, a $96 million preferred-equity investment from Nuveen's energy infrastructure credit platform, and roughly $126 million expected via Inflation Reduction Act ITC transfer.

I talked about Spearmint two weeks ago when its 400 MWh Del Rio and Laredo project hit commercial operation. Red Egret is a different geography and a much larger system. Texas City is in the Coast load zone, on the Houston ship channel, next to a petrochemical corridor that runs negative power-price hours regularly and gets caught short on hot August afternoons. That is a different congestion profile than the West Texas batteries paired with solar that dominate the early-2025 vintage, and it is the direction the next phase of ERCOT storage build is going.

The structure is the story. Merchant BESS revenues have compressed sharply from the 2023 numbers, and vanilla project finance has gotten tighter. The way you close a 600 MWh project now is to layer preferred equity on top of a construction loan and monetize the ITC up front. That is the template every Texas storage developer is going to be running for the next eighteen months.

Gas Crowds Out Wind in the Queue, and the Turbines Are Sold Out Through 2029

Two adjacent data points reframed Texas generation this week. First, natural gas in the ERCOT interconnection queue has climbed from 12,500 MW in March 2023 to roughly 64,000 MW, a fivefold increase, and now exceeds wind in queue megawatts for the first time in six years. Roughly 40 GW of that is directly tied to specific data-center load. The TCEQ is sitting on Pacifico Energy's GW Ranch air permit in Pecos County, a 7.65 GW behind-the-meter gas plant that would be the largest single such permit in the United States, with annualized CO2 equivalent at up to 33 million tons.

Second, GE Vernova reported $2.4 billion in data-center-tied electrification orders in Q1 2026, more than the entire 2025 calendar year. Combined gas-turbine backlog plus slot reservations is on pace for 110 GW by year-end 2026. Siemens Energy and Mitsubishi Heavy Industries are similarly oversold. There are not enough turbine slots through 2029 to build the 64 GW Texas gas queue and the rest of the global gas backlog at the same time.

One of these numbers has to give. The way it gives is going to be schedule slippage on the back end of the data-center buildout, which is going to push more 2026 power demand into the Batch Zero triage from the previous section. The OEM queue is the actual bottleneck. The interconnection queue is just where the OEM queue gets repriced.

Fermi America Buys 600 MW of Siemens SGT800s Off the Shelf

If you cannot wait in line for the turbines, you buy a set that someone else already ordered. Fermi America announced this week it has acquired more than 600 MW of combined-cycle gas-turbine equipment for Project Matador, the 5,769-acre HyperGrid campus outside Amarillo. The package is six Siemens SGT800 gas turbines, six heat-recovery steam generators, and one SST600 steam turbine — a fully aggregated combined-cycle set, named by model number.

Fermi already has preliminary state approval for the first 6 GW of gas at Matador. The May acquisition pulls forward the 1 GW of behind-the-meter power Fermi wants on-site by the end of 2026 to feed the first three 500,000-square-foot data center buildings. There is also a Siemens Energy LOI for an additional 1.1 GW behind it, and an NRC pre-application review running in parallel for up to four 1 GW reactors, with nuclear construction targeted for 2027.

The interesting part is not the size of the campus. The interesting part is the asset arbitrage. With turbine OEM lead times running to 2029 and beyond, secondary-market acquisition of in-hand equipment is now a strategic capability, not a procurement footnote. Expect to see more of it. Expect to see it priced at a premium over OEM list. And expect the developers that can write a check at that premium to be the ones with anchor-tenant offtake — which is to say, not many of them.

What to Watch Next Week

ERCOT Board of Directors, June 1. Final vote on PGRR145 and NPRR1325. If approved, the August 1 protocol effective date and the July 24 Batch Zero submission cutoff become binding. This is the single most important June 1 agenda item in the queue's history.

RCM Hill v. Hill County, U.S. District Court Western District of Texas. Watch for an emergency TRO or preliminary-injunction motion — the complaint asks for one — and for any response from AG Paxton to Senator Bettencourt's letter. The first written decision out of this docket sets the precedent.

ERCOT Final Summer SARA, June 1. The final Seasonal Assessment of Resource Adequacy for summer 2026 confirms or revises the 90.5–98 GW peak band ERCOT staff floated in April. With the queue closing on Batch Zero, the SARA number is what the legislature will use to justify or block whatever comes next.

PUCT large-load rulemaking under 16 TAC §25.194. Final adoption is tracked for July, but staff memos start dropping in early June. Anything that further constrains behind-the-meter co-location will land here first.

TCEQ air-permit dockets. Pacifico's GW Ranch permit is still open. Any next-tier behind-the-meter gas applications filed against the June 5 window are worth tracking — the 7.65 GW threshold is now the ceiling everyone is measuring themselves against.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to Edge Cases

The Anchor Tenant Is the Underwrite: Four Deals, One Pattern

Four deals closed or got entitled in the past week and they read like the same memo. A $7.5 billion lease that won't tell you what state the building is in. A $225 million portfolio sale at $4.25 a watt that turns a telco's stranded colo into a billion-dollar AI platform. A North Carolina campus that lit its second 20 MW phase under a contract that pencils to roughly $2.16 million per megawatt per year. And an Arkansas county that banned data centers on a Tuesday and exempted the only one with a signed utility contract on the same Tuesday.

The common thread isn't geography. It's the tenant. Spec development as a business model is over. Capital prices off the name on the lease — and where a name exists, even an undisclosed one, the building gets financed, the campus gets exempted, the platform gets capitalized. Where it doesn't, the moratorium passes.

"Northern State, Investment Grade, 300 MW." Applied Digital Crosses 1 GW Without Naming the Town.

Applied Digital announced a fourth campus lease on Tuesday — Polaris Forge 3, 300 MW critical IT load, $7.5 billion in base contracted revenue over 15 years, up to $18.2 billion if options run — and the entire site disclosure in the 8-K is "a northern state." Not the county. Not the substation. Not even the state. APLD has confirmed Polaris Forge 1 is in Ellendale, ND and Polaris Forge 2 in Harwood, ND, but PF3 is being held back, presumably at the tenant's insistence, until shovels are in.

The tenant is the same "U.S.-based, high investment-grade hyperscaler" that signed Delta Forge 1 in April. APLD is now sitting on more than 1 GW of contracted capacity from a single counterparty across four campuses. The take-or-pay structure is consistent with prior Polaris leases — fixed monthly minimums against capacity reservations, NNN, escalators in the 2.5–3.0% range. The interesting fact isn't the dollar value. It's that the deal closes before the location is public. When the tenant's credit underwrites the entire stack, geography is a footnote.

Deal specs. Sponsor / tenant: Applied Digital (NASDAQ: APLD) / undisclosed U.S.-based investment-grade hyperscaler · Site: "Northern state," 600+ acres — town n/d · Footprint: n/d (single-story AI-factory format consistent with PF1/PF2) · Load: 300 MW critical IT on ~430 MW gross utility · Power density: n/d · Lease: 15-yr take-or-pay, NNN, escalator n/d, high investment-grade tenant · Deal value: $7.5B base, up to $18.2B with options · Source: DCD.

$4.25 a Watt. I Squared Buys 53 MW From a Telco That Didn't Want It.

Cogent Communications filed an 8-K Tuesday disclosing the sale of ten colocation facilities — Phoenix, Anaheim, Burbank, Stockton, Atlanta, Chicago, Elkridge, Kansas City, Nashville, Houston — to I Squared Capital for $225 million cash. Total installed capacity across the portfolio is roughly 53 MW spread over about 259,000 square feet. The implied price works out to ~$4.25 million per megawatt. That is the kind of number you only see when the seller has stranded assets they inherited from a wireline bankruptcy and the buyer has a thesis.

The thesis is what makes this trade interesting. I Squared isn't just buying ten facilities; the firm committed up to $1 billion in additional platform capital to build out the assets into AI-focused colocation. Most of these sites are urban edge or inner-ring metro — Burbank, Anaheim, Kansas City — where the building exists, the fiber exists, the substation feeds exist, and the only missing variable is rack density. Per-MW pricing is cheap precisely because nobody else will pay legacy telco overhead to renovate them. I Squared just bought a low-cost-basis ramp into edge inference, with a closing dependent on HSR clearance on or after June 12.

The power density is the giveaway on what these sites are today versus what they'll become. 53 MW across 259 ksf is roughly 205 W/sf — that's voice-switch density, not AI density. Anyone buying at this price is underwriting a tear-out, a re-feed, and a re-densification.

Deal specs. Sponsor / seller: I Squared Capital (new platform) / Cogent Communications (NASDAQ: CCOI) via Cogent Fiber LLC · Site: 10 facilities across Phoenix, Anaheim, Burbank, Stockton, Atlanta, Chicago, Elkridge, Kansas City, Nashville, Houston — urban-edge sites within or adjacent to each city's limits · Footprint: ~259 ksf total · Load: 53 MW installed (~205 W/sf blended, legacy telco density) · Lease: Asset purchase, customer contracts transfer; closing on/after June 12, 2026 post-HSR · Deal value: $225M cash plus up to $1B platform commitment · Source: Cogent 8-K.

$2.16 Million per MW per Year. Nscale Lights Phase Two in Madison, NC.

Phase 2 of the WhiteFiber-Nscale colocation deal at the NC-1 campus in Madison, North Carolina begins billing on May 30. That puts the full 40 MW under contract at the Rockingham County site, about 30 miles north of Greensboro. Total contract value is approximately $865 million over ten years, with contractual annual rate escalators undisclosed but baked in. Run the math: $865M / 40 MW / 10 yr = ~$2.16 million per MW per year.

That number is the spec. Anyone underwriting GPU-grade colocation against a non-investment-grade neocloud counterparty — and Nscale, a UK-based AI infrastructure private, is exactly that profile — wants a benchmark for what the credit premium looks like. Roughly $2.16M/MW/yr is what the market is asking. Compare to the Polaris Forge structure, where the tenant is investment-grade and the implied per-MW-per-year run-rate on the $7.5B base is closer to $1.67M — about 22% cheaper for the higher credit. The lease is modified gross with power as a pass-through, not NNN, which is the other tell: WhiteFiber is taking the asset-utilization risk, Nscale is paying for the GPUs and the electrons. There's an option to roughly double Nscale's deployment over two years, which is the real prize if Nscale's funding ramp holds.

Deal specs. Sponsor / tenant: WhiteFiber Inc. (Bit Digital subsidiary, NASDAQ: WYFI) / Nscale (private, UK) · Site: NC-1 campus, Madison, NC — Rockingham County, ~30 mi N of Greensboro · Footprint: n/d · Load: 40 MW (Phase 1 20 MW billing 4/30, Phase 2 20 MW billing 5/30) · Power density: n/d · Lease: 10-yr modified gross, power pass-through, annual escalators (rate n/d), private/non-IG credit · Deal value: ~$865M total contract value · Source: DCK.

Arkansas' Largest County Bans Data Centers. Then Exempts the $6 Billion One.

The Pulaski County Quorum Court did both things at once on Tuesday night. A one-year moratorium on new data-center permits passed 10-5. An exemption for AVAIO Digital Partners' 760-acre Leo campus, just outside Wrightsville and about twelve miles south of downtown Little Rock, passed 8-7. The county chose. The deal that already had a signed Entergy Arkansas contract for 150 MW — expandable to 1 GW — survived. Everything else stops for a year.

The structure is what makes this an Edge Cases story rather than a community-fight story. AVAIO is a private Connecticut-based developer running what looks like a hybrid build-to-suit / pre-lease campus model — the company describes the program as "$6 billion in combined investment from AVAIO and its customers", which is developer-speak for "tenants are funding the buildout against signed leases." Tenant names have not been disclosed. Entergy expects construction to start in June 2026.

The takeaway for anyone shopping county overlays in the Mid-South: a signed utility interconnection contract executed before the political winds shift is the most valuable piece of paper on the deal. It's grandfather rights in everything but name. Counties that pass moratoria carve out the projects that are already wired, because killing those projects also kills the rate-payer cost-share the project sponsors agreed to. The carve-out isn't favoritism — it's the developer's own contract structure protecting them.

Deal specs. Sponsor: AVAIO Digital Partners (private, Connecticut) · Site: 760 acres outside Wrightsville, AR — Pulaski County, ~12 mi S of downtown Little Rock · Footprint: Multi-phase campus, building program n/d · Load: 150 MW initial under Entergy Arkansas contract, expandable to 1 GW · Power density: n/d · Lease: Developer build with tenant fit-out; pre-leased structure implied by "$6B combined AVAIO + customer" language · Deal value: $6B program cost · Source: Arkansas Democrat-Gazette.

What to Watch Next Week

Columbus, GA — Project Ruby first reading. Atlas/Habitat's $5.18B / 865-acre hyperscale campus zoning overlay was paused 45 days past the May 19 council election. First reading now expected late May or early June. This is the next big Southeast site with an actual proposed lease tenant attached.

Box Elder County, UT — Stratos referendum certification. O'Leary Digital's 9 GW off-grid campus, approved May 4 with Ruby Pipeline gas, faces a referendum challenge. Governor Cox publicly told the developer the project would "never" be 100% gas. Watch for referendum certification and the gas-to-grid pivot that the political math is now forcing.

Reno City Council moratorium follow-up. The May 14 special meeting on a temporary data-center permitting pause has a follow-up vote pending. Vantage's Storey County phase-2 commentary is expected on the same calendar.

AEP Ohio commission update. AEP filed an update with the PUCO on data-center load under contract; the Q2 update lands soon. Watch the large-load tariff filings around the Columbus / New Albany cluster — that's where the AES Indiana / Google Monrovia tariff template gets stress-tested.

Cogent–I Squared HSR clock. Closing on or after June 12. If I Squared moves fast, expect the first follow-on acquisition for the platform to be telegraphed by Q3.

Disclaimer: Edge Cases is Barrio Energy's deal-flow product. Nothing here is investment advice, a recommendation to transact, or a substitute for your own diligence. Specs are sourced from public filings, press, and reporting; verify before you wire anything.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

$67 Billion and the Biggest Utility Ever

Two things happened in Texas energy this week that look like opposites and are, on closer inspection, the same story. At the top of the capital stack, NextEra agreed to swallow Dominion for roughly $67 billion — the largest utility acquisition in American history, structured end to end to chase the load that AI data centers are about to drop on the grid. At the bottom, the city council in El Paso voted to advance a proposal that would hand future data centers exactly zero tax breaks. Bigger and angrier, in the same seven days, pointed at the same thing.

The connective tissue is power: who builds it, who pays for it, and what it is actually made of. And on that last question the answer quietly shifted this week too — the EIA now expects solar to outproduce coal across ERCOT for the first full year in the grid's history. Scale is the strategy. Cost allocation is the battlefield. And the resource keeping the lights on is the one nobody is fighting about.

"The World's Largest Utility," Built for the AI Load

NextEra Energy agreed on May 18 to acquire Dominion Energy in an all-stock deal valued at nearly $67 billion, creating what both companies are calling the largest regulated utility in the world — roughly 10 million customers across the Southeast and a combined market capitalization near $249 billion. The merger agreement is dated May 15. Dominion holders get a 23% premium and 25.5% of the combined company; NextEra holders keep 74.5%. It is the biggest utility tie-up the country has seen and the largest energy-sector deal since Exxon bought Mobil in 1998.

The logic is not subtle. Dominion sits on top of Northern Virginia, the densest data center cluster on earth. NextEra brings Florida, the largest renewables fleet in the country, and a gas-hub buildout that includes a 5.2 GW project in Anderson County, Texas. Combined, the two would carry a roughly 130 GW large-load pipeline — a backlog of hyperscaler interconnection requests larger than the peak demand of most countries. The bet is that only a balance sheet this size can build generation fast enough to serve it.

I have spent the last two issues on the question of who pays for data center load. This is the supply-side answer to the same pressure: when you cannot build fast enough, you buy someone who already has. Expect NextEra's post-announcement stock dip and the antitrust clock to set the tone for the next few weeks, and expect at least one rival to start quietly shopping. The first AI-era utility mega-merger is rarely the last.

Solar Beats Coal in ERCOT, and No One Built a Plant to Stop It

The EIA's latest Short-Term Energy Outlook projects ERCOT solar generation at 78 billion kWh in 2026 against 60 billion kWh for coal — the first full year solar outproduces coal in the grid's history, per the agency's own data. Solar's share of the ERCOT mix has climbed from 4% in 2021 to 12% in 2025; coal has slid from 19% to 13%. About 40% of all U.S. solar capacity added this year, roughly 14 billion kWh worth, lands in Texas.

The detail that matters is the one in the generator inventory: there are no new coal plants planned in ERCOT, none. This is not solar winning an argument. It is solar winning by attrition while coal stops showing up. Solar already passed coal on a monthly basis back in March 2025; 2026 just turns it into an annual fact, every month except December.

Hold that against the load forecasts everyone keeps quoting. The queue headlines are gas and nuclear, because firm power is what hyperscalers say they want. But the electrons actually being added to the Texas grid right now are overwhelmingly solar — and, as the next story shows, the batteries that make solar dispatchable after the sun goes down.

El Paso Electric Wants a Data-Center Rate Class. The City Wants No Tax Breaks.

El Paso Electric is asking the PUCT to create a dedicated "High Load Factor Large Power" tariff — a rate class built specifically for data centers, with Meta's planned $10 billion El Paso campus as the anchor tenant. The filing includes a bridge period of one to five years during which Meta pays the full delivery cost of serving it; after that window, the cost of the generation built for the campus begins to shift onto the broader customer base.

Two days later, on May 21, the El Paso city council advanced a separate proposal: stricter oversight of AI data centers, mandatory water- and energy-use disclosure, and no tax abatements or incentives for new projects.

This is the cost-allocation fight I keep circling, except now it has a specific utility, a specific city, and a specific mechanism — that bridge period, after which the bill moves. The notable part is not that El Paso worries about cost-shifting. Everyone does. It is that a mid-size Texas city is moving to kill incentives at the exact moment NextEra is spending $67 billion on the premise that this load is the best customer the utility industry has ever had. Somebody is wrong about the economics. Probably both, in different places.

400 Megawatt-Hours in Del Rio and Laredo, and the 53% Nobody Mentions

Spearmint Energy brought two standalone ERCOT batteries to commercial operation this week: Tierra Seca near Del Rio and Seven Flags near Laredo, each 100 MW / 200 MWh, for a combined 200 MW / 400 MWh. Routine on its own. The context is not: Texas accounts for roughly 12.9 GW, or 53%, of the 24 GW of utility-scale battery storage the U.S. plans to add in 2026.

ERCOT entered the year with close to 13.9 GW of operational storage, nearly double the figure twelve months earlier. NERC's summer reliability assessment credits about 7.5 GW of new Texas batteries with firming the evening ramp as solar rolls off. That is the unglamorous machinery making the solar-over-coal headline real — and a big part of why ERCOT thinks it can clear a summer peak it now pegs in the 90-to-98 GW range, comfortably above the 85,508 MW record set in August 2023.

What to Watch Next Week

NextEra-Dominion's regulatory gauntlet. The Hart-Scott-Rodino antitrust clock starts now, and regulators in Virginia, the Carolinas, and Florida all get a say. Watch for analyst downgrades after NextEra's stock dip, and for a rival utility to start its own shopping.

The PUCT large-load rule. The final version of the interconnection rulemaking is due mid-year, including the $50,000-per-MW non-refundable fee. El Paso Electric's data-center tariff is the first real test case for how the cost actually gets split.

ERCOT's batch interconnection. The board is expected to approve the new batch process, targeting an August 1 effective date, with the PUCT weighing in during July. Any change reshapes a queue now sitting north of 450,000 MW.

The first heat. Peak season is here. The first sustained heat event will test whether the 90-plus GW forecast and the new battery fleet hold up. A fresh all-time record is well within reach.

El Paso's council vote. If the no-incentives proposal becomes policy, expect other Texas municipalities to reach for the same template.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

Three Charts for the Data-Center Conversation You're About to Have

The three things people most commonly get wrong about data centers — that they raise residential electric rates, that they drain local water supplies, and that they get built next to schools — are all, on the actual numbers, the opposite of the truth. This is a short field guide for business leaders, civic officials, and anyone who's been asked to defend a project at a council meeting. Each section gives the technical case first, then the one-line version you can hand to a reporter or a neighbor.

The data behind these three points is not contested at the academic level. It is contested on cable news. That gap is the entire problem.

1. Do Data Centers Raise Electric Rates?

The technical case. A team at Lawrence Berkeley National Laboratory just published the most rigorous accounting of U.S. retail electricity prices to date in The Electricity Journal — Wiser, O'Shaughnessy, Barbose, Cappers, and Gorman (December 2025). The headline finding: on an inflation-adjusted basis, 32 of 50 states saw residential electricity prices fall between 2019 and 2024. The U.S. average rose about 0.5¢/kWh in real terms — roughly $54 per year for the average household. Commercial and industrial customers paid less in real terms in 2024 than in 2019.

More to the point: the states with the largest data-center load growth did not see the largest rate increases. They saw the smallest, and in several cases, the largest decreases. The Berkeley team documents this directly. North Dakota, which absorbed crypto, oilfield electrification, and data-center demand, saw real residential prices fall about 3¢/kWh over the study window. Iowa, with its hyperscale buildout, fell about 1¢. Virginia — home of Ashburn's "Data Center Alley" — was roughly flat to down. PG&E told California regulators that each new gigawatt of data-center load would lower residential bills by 1 to 2 percent for exactly the same reason.

Bar chart showing inflation-adjusted residential electricity rate changes 2019-2024 by state, with data-center-heavy states like North Dakota, Iowa, and Virginia showing real decreases while California, Connecticut, and Hawaii show increases.

The mechanism is utility economics 101. A utility's fixed costs — wires, substations, generation under power-purchase agreements, transmission infrastructure — don't shrink when demand falls. They're recovered through per-kWh rates. So if total demand on the system rises and the new demand pays for the marginal capacity it needs, the existing fixed-cost base gets spread over a larger denominator, and the per-kWh rate falls. This is the same principle that lets a restaurant lower per-plate cost by filling more tables: the rent doesn't change.

What actually drove rate increases? The Berkeley paper ranks five drivers. Data centers aren't on the list. Distribution capital expenditure — the wires and substations utilities have deferred since the 1990s — is #1, up about 50% nationally between 2019 and 2023. Climate and weather costs (California wildfires alone added $27 billion to ratepayer bills 2019–2023) are #2. Natural gas pass-throughs are #3. Renewable Portfolio Standards in states with shrinking load account for the rest, and only in a subset of states. The cable-news talking point that data centers and renewables are jacking up everyone's bills doesn't survive the regression.

Horizontal bar chart ranking the five drivers of U.S. residential rate increases 2019-2024: distribution capex, climate and weather, fuel volatility, RPS in shrinking-load states, and data center load growth which is negative.

The analogy for the public. When you spread the cost of a hotel across 200 occupied rooms instead of 100, the price per room goes down. Data centers fill the rooms. The reason your electric bill is rising isn't the new guest down the hall — it's the new roof on the building. And the storms that made the new roof necessary. And the gas that heats the lobby. The data center isn't the problem; it's the new guest paying their share of the existing fixed costs.

A second one-liner that works in a city council setting: "In every state that's grown data-center load fast, residential rates have fallen in real terms. The states with the worst rate problems — California, Connecticut, Hawaii — have almost no data centers. Don't confuse correlation with causation. The data tells the opposite story."

2. Do Data Centers Drain the Water Supply?

The technical case. Data-center cooling falls into two distinct technical buckets, and conflating them is the single most common error in public reporting. Evaporative cooling uses water as a thermal medium — water is evaporated, the phase change pulls heat out of the air, and the now-cooler air cools the servers. This is the high-water-use design. Closed-loop liquid or air cooling uses a sealed coolant circuit that never evaporates. Water is added once, at construction, the way a car's radiator is filled at the factory.

The industry's preferred metric is Water Usage Effectiveness (WUE), measured in liters of water per kWh of IT load. The industry-average WUE for evaporative-cooled hyperscale is about 1.8 L/kWh. Microsoft's 2024 fleet average is 0.30 L/kWh; AWS reports 0.19 L/kWh; Google and Meta come in around 1.08–1.12 L/kWh. Microsoft's next-generation closed-loop design, announced December 2024, hits a WUE of essentially zero — the company says it eliminates 125 million liters (~33 million gallons) of annual water use per facility versus its prior design. Barrio Energy's data centers use the same closed-loop architecture.

The arithmetic for a 10 MW facility — Barrio's reference small-campus size — is straightforward. At industry-average WUE, a 10 MW evaporative facility consumes roughly 41.6 million gallons per year. At Microsoft's best-in-class WUE, the same load draws ~6.9 million gallons. A 10 MW closed-loop facility — Barrio's design, Microsoft's new design, the direction the whole industry is moving — uses approximately 20,000 gallons total, one time, at construction. That is roughly one residential swimming pool. The facility then runs for thirty years without refilling.

Logarithmic bar chart comparing annual water use: 10MW Barrio closed-loop data center at 20,000 gallons one-time fill, average US household at 110,000 gallons per year, evaporative data centers at 6.9 to 41.6 million gallons per year, a Texas cotton field at 50 million gallons per year, an average US golf course at 200 million gallons per year, and a Southwest US golf course at 365 million gallons per year.

For perspective: the average U.S. 18-hole golf course consumes about 200 million gallons per year; a Southwest course in peak summer can hit 365 million. A single 100-acre Texas cotton field uses 32 to 65 million gallons per growing season. The average U.S. household uses about 110,000 gallons. A 10 MW closed-loop data center is closer, on annualized water use, to a single washing machine than it is to any of these. The "data centers are draining the aquifer" framing comes from extrapolating evaporative-design numbers — which are real, and which Microsoft, Meta, AWS, and Barrio have all moved away from — to a generation of facilities that no longer work that way.

The analogy for the public. A closed-loop data center uses water the way a car uses radiator coolant — you fill it once at the factory and it runs for the life of the vehicle. An evaporative data center uses water the way a swamp cooler does — it evaporates a continuous stream into the air. We build the first kind. The second kind exists, and the industry is rapidly retiring it.

The one-line version: "One 18-hole golf course in our region uses more water in a single year than ten of our data centers would use in their entire 30-year operating life. We're not the water problem. If anything, we're an argument against the water problem."

3. Where Do Data Centers Actually Get Built?

The technical case. Across every U.S. metro with a meaningful data-center footprint, the sites are sited in light industrial (M1) or equivalent zoning — the same category that hosts warehouses, distribution centers, light manufacturing, R&D labs, and self-storage. They are not, by ordinance or practice, sited in residential, mixed-use, or commercial-retail districts.

Ashburn, Virginia — the largest data-center cluster on the planet, with more than 100 facilities and roughly 70% of global internet traffic passing through it — permits data centers by right in three zoning categories: Industrial Park (PD-IP), General Industry (GI), and Mineral Resource–Heavy Industry. Data centers are not permitted in residential zones, period. Mesa, Arizona — the second-largest cluster in the Southwest — restricts them to General Industrial and High-Industrial zones only. The City of Chandler adopted a 2024–2025 ordinance codifying the same restriction.

The Texas pattern is identical. Plano's 46 MW Aligned DFW-01 facility at 2800 Summit Avenue sits inside the city's light-industrial corridor with a Specific Use Permit layered on top. Richardson's Digital Realty and CyrusOne campuses are in the I-M(1) Industrial / Telecom Corridor district. Crusoe's Stargate-affiliated 1,100-acre campus at 5502 Spinks Road in Abilene was annexed into city limits in 2021 specifically to access industrial zoning. IREN's 1,300-acre Sweetwater 1 campus sits on rural industrial land. Microsoft's San Antonio cluster spans Texas Research Park in Bexar County and ~1,100 acres of rural industrial land in Medina County.

Table showing data center clusters and their zoning: Ashburn VA in Industrial Park or General Industry by right, Mesa AZ in General or High Industrial only, Chandler AZ in industrial zones per 2024-25 ordinance, Plano TX Aligned at 2800 Summit Ave in Light Industrial with SUP, Richardson TX Digital Realty in I-M(1) Industrial Telecom Corridor, Abilene TX Crusoe at 5502 Spinks Rd in industrial corridor, Sweetwater TX IREN at 883 FM 611 in rural industrial, San Antonio metro Microsoft in industrial and R&D Park in Medina and Bexar counties.

An important framing point: a modern data center is, by industrial-zoning standards, an unusually quiet, low-traffic, fume-free neighbor. The typical M1 facility nearby is a Class A warehouse that runs 50 truck deliveries a day, an auto body shop with paint VOCs, a self-storage complex with 24/7 vehicle traffic, or a light-manufacturing plant with shift changes. A data center has ~10 truck deliveries a month, a parking lot for a small tech staff, and rooftop cooling equipment regulated by the same noise ordinance as every other M1 use. The argument is not that data centers should be welcomed because they're industrial; it's that they are better neighbors than most of what already lives in industrial.

The cases where data centers generate real public controversy almost all share a structural feature: they are proposed for land that has no zoning at all. The Texas Tribune-covered Hill County moratorium earlier this month is the canonical example — the project was on unincorporated land outside any city's zoning authority, where Texas counties don't have general zoning power to channel industrial development. That isn't a data-center problem. That's a zoning-gap problem. In every city with a functioning M1 district, this conflict simply doesn't happen, because the rule is already in place: industrial uses go in industrial zones. Data centers are the most boring kind of industrial use.

The analogy for the public. Data centers go where Amazon warehouses go, where FedEx hubs go, where the cabinet shop and the steel fabricator go. We don't get built across the street from elementary schools, and the zoning code wouldn't let us if we tried. The neighbor you have right now — the one with the loading docks, the diesel forklifts, and the third shift — is louder, smellier, and more truck-heavy than a data center will ever be.

The one-line version: "Show me a data center in a residential neighborhood. You can't, because zoning law doesn't allow it. We go where warehouses go — and unlike warehouses, we don't have eighteen-wheelers on the dock at 4 a.m."

The Bigger Picture

The pro-data-center case isn't ideological. It's arithmetic. Texas now leads the country with 142 data centers under construction, narrowly ahead of Virginia. The industry produced about 61,000 direct Texas jobs in 2023 and generated $3.2 billion in state and local tax revenue in 2024 — outside the sales-tax-exempt portion. A single Hood County campus is projected to bring enough property-tax base to fund a new junior high school. These projects are not extracting from communities; they are paying for the wires, the roads, the schools, and — when the rate design works correctly — for the marginal grid capacity they require.

The honest pro-data-center position is not that there are no costs. It's that the costs are recoverable, the benefits are durable, and the alternative — Texas conceding the AI infrastructure buildout to Virginia, Arizona, or any of the half-dozen other states writing checks for it — is not actually an alternative anyone in this state should want.

Use the charts. Quote the LBNL paper. The data is on our side; the conversation is the only thing that hasn't caught up.

What to Watch Next Week

PUCT draft rule §25.194 comments. The Senate Bill 6 rulemaking on large-load interconnection and transmission cost allocation is where the technical version of "data centers paying their fair share" gets written into Texas regulation. Hyperscaler and consumer-advocate filings are running now.

Hill County moratorium litigation. Texas counties don't have general zoning authority; legal experts expect a challenge to the May 12 moratorium on standing grounds. If overturned, the case becomes a precedent for keeping industrial projects on industrial land — by ordinance, not by ban.

EIA Short-Term Energy Outlook update. The May STEO will refresh the 2026 retail rate forecast for the South region. Watch for whether load-growth dilution starts showing up in Texas residential rate projections.

Microsoft Phoenix and Mt. Pleasant pilot data. Microsoft's first closed-loop facilities come online in late 2027. Early instrumentation data from the pilots — water draw, PUE, thermal performance — will be the first independent confirmation of the zero-evaporation design at hyperscale.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Barrio Energy develops behind-the-meter, closed-loop data center infrastructure in Texas. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

Berkeley Lab Says U.S. Power Prices Are Flat. Your Texas Bill Is Not.

A team at Lawrence Berkeley National Laboratory published a paper in the December 2025 issue of The Electricity Journal called "Factors influencing recent trends in retail electricity prices in the United States." If that title sounds like the kind of thing only economists read, fair. But the findings are quietly explosive, and almost nobody on the cable-news side of the data-center debate has bothered to look at them.

The short version: across the country, real retail electricity prices barely moved from 2019 to 2024. Adjusted for inflation, the U.S. average declined roughly 8% from 2010 and has been flat since 2019. Thirty-two of fifty states saw inflation-adjusted residential prices decrease over the five-year study window. The headlines about prices "soaring" rely entirely on nominal dollars, and the authors say so explicitly. The story most retail customers tell themselves — that runaway data centers and renewables have set their bills on fire — is, at the national level, not the story the data tells.

And then there's Texas, where residential rates ran from 11.7¢/kWh in 2020 to 15.84¢/kWh in September 2025 — a 35% nominal increase, well ahead of inflation, with another ~29% projected rise by 2030. Texas is not the national story. Texas is the leading edge of where the national story is about to go.

The Study Nobody on Cable News Will Read

The Berkeley paper, authored by Ryan Wiser, Eric O'Shaughnessy, Galen Barbose, Peter Cappers, and Will Gorman, is the closest thing to a definitive accounting of what actually moved U.S. retail rates between 2019 and 2024. The full summary PDF runs roughly 80 pages of regression, state-by-state breakouts, and bill-impact decomposition. The headline finding is the one nobody wants to put on a chyron: residential prices rose about 0.5¢/kWh in real terms over those five years, or roughly $54 per year for the average 10,791-kWh household. Commercial and industrial customers? Their real prices fell by 0.3¢ and 0.2¢/kWh respectively.

That gap matters. Residential customers are quietly subsidizing C&I, and the gap has widened every year since 2019. The political conversation about who's "paying" for the data-center buildout is missing the part where, in many states, large industrial and commercial users have already been paying less on a real, per-kWh basis than they did five years ago. The question isn't whether residential customers are bearing more cost — they are. The question is which costs, and why.

The Berkeley team ran the decomposition and ranked the drivers. The ranking is going to make a lot of people on both sides of the renewables debate uncomfortable, so let's just walk it.

Five Drivers, Ranked

Driver #1: Distribution capital expenditure. The single largest factor in residential price increases. Utility distribution-related capex rose roughly 50% nationally between 2019 and 2023, far outpacing inflation. Aging-infrastructure replacement accounts for about 28% of that spend. This isn't transmission, and it isn't generation. It's the wires running down your street, the substations on the edge of your neighborhood, and the long tail of poles and transformers that utilities have been pushing off since the 1990s. The bill is now due.

Driver #2: Climate and weather. California's wildfire mitigation alone added roughly $27 billion to utility rates between 2019 and 2023, with about 40% of that being insurance cost growth. Storm hardening in Florida and the Gulf Coast — including, as we'll get to, the CenterPoint Houston securitization after Hurricane Beryl — is the second-largest geographic driver of residential bill increases. This bucket grows for a while no matter what anyone does about policy. The damage is already in the asset base.

Driver #3: Fuel volatility. Real residential prices rose fastest in states that lean heaviest on natural gas. Most utilities pass 100% of fuel costs through to customers via fuel adjustment clauses, so when gas spikes, residential bills move within months. EIA reported October 2025 gas prices were up 45% year over year and the agency expects another ~16% increase by October 2026. If you live in a gas-heavy ISO — like, say, ERCOT — fuel pass-through is doing more to your bill than anything else short-term.

Driver #4: RPS-linked renewables in shrinking-load states. The one place the study lands a finger on clean-energy mandates. In states with both a binding renewable portfolio standard and flat or declining load, RPS compliance added about 0.25¢/kWh on average. That's a small number, and it's contained to a specific subset of states. The vast majority — roughly three quarters — of new wind and solar built between 2019 and 2024 was market-driven, not RPS-driven, and the paper finds that market-driven renewables build had no discernible impact on retail prices. In several models, it pushed prices down. The cable-news talking point that "renewables raised your bill" is, on the numbers, mostly wrong.

Driver #5: Load growth direction. This is the one almost nobody talks about, and it's the one Texas should care about most. States where load grew, real residential prices fell. North Dakota — which absorbed crypto, oilfield electrification, and data center demand — saw real residential prices drop about 3¢/kWh because fixed costs were spread over more megawatt-hours. PG&E told regulators that each new gigawatt of California data-center load could lower residential bills by 1–2%, for the same reason. The intuition is straightforward: a utility's fixed cost base doesn't shrink, so more demand means lower per-kWh cost recovery. The question is whether the new load brings new capital cost with it, and at what ratio.

If the new load comes with $40 billion in transmission and $15 billion in generation built almost entirely to serve it, and if the rate design lets the new load avoid paying its share of those investments, then load growth isn't a deflator anymore. It's an accelerant. Welcome to Texas.

The Texas Carve-Out — Where the National Story Stops

Texas doesn't fit the national average on any of the five drivers cleanly. It's worse than average on three of them and structurally different on the other two.

Distribution capex: Oncor announced its 2026–2030 base capital plan at $47.5 billion in February 2026, up sharply from the prior plan. CenterPoint Houston's storm-hardening + resiliency request was $5.75 billion; PUCT approved $2.9 billion of it in November 2025. Layered on top, CenterPoint received $1.2 billion in securitization for Hurricane Beryl restoration in October 2025, with an immediate ~$2/month residential bill impact. Oncor's June 2025 base rate case was settled by the Commission in April 2026 at $560 million in annual increases on a 9.75% authorized return on equity.

That is roughly $52 billion of utility capex pre-approval or under construction in two service territories, on a horizon of five to seven years. Most of it lands on residential and small-commercial customers under current rate design.

Weather: Beryl alone produced enough storm damage to qualify CenterPoint for a one-billion-dollar securitization. The Berkeley paper's "climate and weather" bucket captures California fires and Florida hurricanes; Texas is now firmly in the same cohort.

Fuel: ERCOT's marginal price-setter is almost always natural gas, and Texas residential REPs (TXU, Reliant, Gexa, Cirro, and the long tail) pass fuel costs through with limited regulatory friction. ERCOT North average wholesale prices were around $27–34/MWh in 2025, but EIA's December outlook projected a 45% wholesale price spike between 2025 and 2026, and a high-demand scenario where data center load pushes ERCOT North wholesale prices 79% above baseline by 2027. That spike flows directly into the variable component of residential REP plans the next time those customers shop.

Renewables: Texas has no binding RPS. The 1999 RPS goal was met in 2009 and isn't binding on anything. So the one factor the Berkeley paper isolates as a real (if small) price driver is essentially absent here. Whatever is moving Texas residential bills, it isn't a clean-energy mandate.

Load growth: This is the structural divergence. ERCOT load grew about 5% from 2024 to 2025 and is forecast to grow roughly 10% per year through 2027, with data centers accounting for about 73% of large-load interconnection requests. Under the Berkeley model's logic, this should push real residential rates down — fixed costs spread over more megawatt-hours. Texas residential rates have done the opposite. The question is why, and the answer lives in the rate design.

Who's Subsidizing Whom: 4CP, SB 6, and the March 2026 Rule

Texas allocates wholesale transmission costs using a method called 4CP — the four coincident peaks. A large industrial or data-center customer's annual share of ERCOT transmission costs is based on its average demand during the four 15-minute intervals of highest system load each summer. If you can predict those intervals and curtail through them, your transmission allocation drops dramatically. Residential customers cannot curtail their air conditioning at 5:00 p.m. on a 105-degree day in August. Industrial customers can, and do.

The result, documented in detail in NRG's February 2025 PUCT remarks, is that residential and small-commercial customers in ERCOT pay a larger share of transmission costs than their share of energy consumption would suggest. The 4CP method, designed when the grid had a handful of large industrial sites and predictable peaks, has become a structural subsidy from households to large flexible loads in an era of 75-megawatt-and-up data center interconnections.

The legislature noticed. Governor Abbott signed Senate Bill 6 in June 2025, requiring PUCT to evaluate the 4CP method and finalize rule changes by December 31, 2026. SB 6 also sets new interconnection standards for loads of 75 MW and above, gives the Commission new authority over backup generation registration, and ties large-load curtailment obligations into ERCOT's reliability framework. PUCT published draft rule §25.194 on March 12, 2026; comments are running now.

The cost-allocation language is where the residential-versus-data-center fight gets decided. If PUCT replaces 4CP with a 12CP, a demand-ratchet, or a causation-based method, hundreds of millions of dollars of annual transmission cost recovery shift between customer classes. If PUCT leaves 4CP largely intact and only tightens the curtailment definitions, the residential subsidy of large loads continues — through the entire $33 billion Strategic Transmission Expansion Plan, of which the first $9.4 billion 765-kV phase was approved by the ERCOT Board in December 2025.

That's the real fight. Not whether data centers come to Texas — they're here, and the queue is full. The fight is over who pays the wire bill.

The 2026–2030 Capex Cliff

The Berkeley study is retrospective. The data window closes in 2024. None of the numbers above — Oncor's $47.5 billion, CenterPoint's $2.9 billion resiliency plan, the ERCOT STEP $33 billion, the Beryl securitization, the SB 6 rulemaking — show up in the regressions. The paper measures a national real-rate baseline that was, by its own findings, mostly flat. Texas is about to spend the next five years showing what happens when distribution capex doubles, transmission capex enters $30-billion-plus territory, and load growth runs at 10% a year through it all.

The math runs both ways. If 4CP gets replaced with a method that puts the new transmission costs on the loads driving them, then the load-growth dilution effect the Berkeley team found in North Dakota kicks in and Texas residential rates flatten — maybe even decline in real terms. If 4CP survives mostly intact, the capex cliff lands on residential customers and the 29%-by-2030 projection from the Texas Chemistry Council brief starts looking conservative.

The Berkeley paper does not predict either outcome. It just lays out what made rates do what they did over the past five years, and it provides the framework for thinking about which dial moves next. The frameworks are useful. The conclusions are honest. The part most retail customers will care about — what their bill looks like in 2028 — depends entirely on a PUCT rulemaking that closes 19 months from now.

Read the paper. Or at least read the summary. It's free.

What to Watch Next Week

PUCT draft rule §25.194 comments. The comment period on the SB 6 large-load interconnection and cost-allocation rule is the single most consequential proceeding for Texas residential rates over the next five years. Final rule must be in place by December 31, 2026. Watch for big-load coalition filings (data center hyperscalers, crypto miners, refiners) versus consumer-advocate filings (Office of Public Utility Counsel, Texas Coalition for Affordable Power).

EIA Short-Term Energy Outlook update. STEO refreshes monthly and is currently projecting another roughly 5% nominal residential price increase in the South region for 2026 on top of 2025. The May 2026 STEO will likely raise that figure as Q1 utility rate-case settlements get baked in.

PUCT 4CP methodology decision. Separate from the §25.194 rulemaking, PUCT was required under SB 6 to evaluate 4CP within 90 days of the bill's effective date. The Commission has been working through the evaluation; a decision memo or open-meeting item naming a successor methodology — or formally extending 4CP — is overdue.

CenterPoint and AEP Texas next rate filings. Both are expected to follow Oncor's playbook with comprehensive base rate cases in 2026, citing storm hardening, load growth, and the same distribution-capex driver the Berkeley paper ranked first.

The LBNL 2026 edition. The Berkeley team typically refreshes the dataset annually. The March 2026 update already pulls in Q3 2025 EIA-861 data. Texas-specific tabs in the next version, expected this fall, will be the first time the academic literature catches up with what's happening on the ground here.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"We Don't Want It in Our Community": Texas Starts Pushing Back

For three years the Texas data center story has been a one-way ratchet: more megawatts requested, more campuses announced, more capital committed, and a grid operator that kept raising its own forecast. This week the ratchet caught. On May 12, Hill County commissioners voted 3-2 to freeze new data center construction in unincorporated areas for a year — the first Texas county to do it. Two days later came a report that a Chevron subsidiary wants a West Texas school district to hand it a nine-figure tax break for a gas plant built to power a single data center. The Senate Finance chair is calling the state's data center tax exemptions "unsustainable." None of this stopped the capital — Nvidia put $5.5 billion into a Texas miner the same week — but the friction is now real, organized, and on the record.

The through-line: there is a widening gap between what data center developers are promising and what counties, regulators, and the grid will actually absorb. ERCOT itself has said as much. The deals below are this week's evidence on both sides of that gap.

"We Don't Want It in Our Community": Hill County Freezes the Land Rush

On Tuesday, Hill County commissioners voted 3-2 to impose a one-year moratorium on new data center construction in unincorporated parts of the county — the first Texas county to pull that lever. The trigger was a proposed 300-acre campus in north Hillsboro tied to Dallas-based Provident Data Centers, which already runs nine US facilities, four of them in Texas. More than 100 residents packed the commissioners' meeting to object over water draw, noise, and grid strain.

County Judge Justin Brassell was blunt about what comes next: he expects lawsuits from developers "and perhaps the state as well," and framed the pause as a guardrail on a "land rush." He is probably right about the state. Houston Senator Paul Bettencourt, who passed a 2025 bill restricting municipal moratoriums, has already asked Attorney General Ken Paxton to investigate counties that pass pauses. The same week, nearby Hood County weighed its own moratorium and rejected it. So the score is one county in, one county out, and an AG referral pending — which is to say the legal template for every rural Texas county gets written in the next few months.

The part worth sitting with: this is not NIMBY noise from a metro suburb. Hill County is rural, the kind of place the buildout was supposed to be welcome. When the friction shows up there, the friction is structural.

Chevron Wants West Texas Schoolkids to Subsidize a Data Center's Power Plant

A May 14 report laid out the filing: a Chevron subsidiary, Energy Forge One, has applied for a Texas school-district tax abatement worth potentially $227 million-plus over ten years for a gas-fired plant in West Texas built to serve a single data center. The likely tenant is Microsoft, though Chevron says no final agreement exists and insists the incentive covers only the power facility, not the data center itself. That distinction is doing a lot of work.

What makes this one notable is the precedent. The State Comptroller's office issued a recommendation supporting the application in late January — the first time the program has backed an abatement for a plant built solely to power a data center. School-district tax breaks were designed to land manufacturing plants and the payrolls that come with them. A behind-the-fence gas turbine serving one hyperscaler is a different animal, and the Comptroller just blessed it.

It arrives at an awkward moment. Senate Finance Chair Joan Huffman has called the state's roughly $1.3 billion a year in data center sales-tax breaks "extremely concerning" and "unsustainable," with an interim hearing set for July ahead of possible repeal legislation. Texas spent a decade competing to give this industry money. The argument now is whether it can afford to keep doing it.

Nvidia Writes the Check: $5.5 Billion Into a Texas Miner

The capital, for its part, did not get the memo about friction. On May 7, Nvidia announced a two-part deal with IREN — the Bitcoin miner that has spent the past year recasting itself as an AI host — pairing a potential $2.1 billion equity investment with a $3.4 billion, five-year managed cloud contract for Nvidia's own internal AI workloads. Call it $5.5 billion. The hardware rolls out through 2026 at IREN's 750 MW campus in Childress, Texas, where the company is building liquid-cooled halls for a 200 MW critical IT load.

Read the structure, not the press release. Nvidia is moving downstream to lock up guaranteed compute capacity for itself, and it is using a former miner's Texas land and power position to do it. That is the miner-to-AI pivot graduating from "we signed a tenant" to "the chip vendor is now our anchor investor." Expect Hut 8, Bitfarms, and Cipher to chase the same template — I flagged Hut 8's $9.8 billion tenant comp two weeks ago, and this is the next rung up the ladder.

For a sense of how committed the sector is to leaving Bitcoin behind: MARA reported Q1 on May 11 with a $1.26 billion net loss, having sold 15,100 BTC for about $1.1 billion, and management stated flatly that it is "no longer a Bitcoin miner." When the companies say it themselves, believe them.

GE Vernova and Blue Energy Bet on "Gas-Plus-Nuclear" — One Site, Two Fuels, 2.5 GW

On May 5, GE Vernova and nuclear startup Blue Energy announced a 2.5 GW "gas-plus-nuclear" power station in Texas, designed to feed a data center campus from a single site. The plan pairs GE Vernova Hitachi BWRX-300 small modular reactors with GE 7HA.02 gas turbines on a "gas-to-nuclear bridge": gas energizes first — roughly 1 GW by 2030 — then nuclear ramps to about 1.5 GW by 2032.

The partners hold a turbine slot reservation for two 7HA.02 units in 2029, target a final investment decision in 2027, plan early site works in Texas this year, and intend to file for an NRC construction permit in 2027, aiming for roughly 48 months to power through offsite prefabrication. Whether the nuclear half arrives on that schedule is the open question — SMR timelines have a habit of slipping right. But the gas half is real and near-term.

Notice what this shares with the Chevron plant: generation purpose-built beside the data center, not added to the shared ERCOT grid. Two announcements in one week of multi-hundred-megawatt plants whose entire reason for existing is one customer behind the fence. The grid is increasingly not the power source — it is the thing the power source sits next to.

175 MW Now, 2.1 GW Later: The Gap Between Promised and Real

If you want the whole tension in a single project, look at Lufkin. Developer Amp Z is building a campus on the former Southland Paper Mill site in Angelina County, East Texas — about 1,041 acres, with room to expand to 4,000. The capacity trajectory: 55 MW grid-connected today, 175 MW by the end of 2026, 1.1 GW by 2028, and a total of 2.1 GW with a gigawatt of on-site self-generation by 2029.

Every one of those numbers past the first is a promise. And ERCOT has been unusually candid that the promises do not all come true — the grid operator told the PUCT this spring it has "concerns with using the preliminary load forecast" precisely because so many large-load projects will not materialize on time, at full scale, or at all. CEO Pablo Vegas told the House State Affairs Committee in early May that ERCOT is tracking about 410,000 MW of interconnection requests, 87% of them data centers. Nobody — least of all ERCOT — thinks all of that gets built.

That is the gap the county commissioners and the Senate Finance chair are reacting to. Developers underwrite the 2.1 GW headline. Communities and regulators have started underwriting the 175 MW that is actually under construction. Both can be right, and the distance between them is where the next two years of Texas energy politics will be fought.

What to Watch Next Week

Paxton's response to Bettencourt. Whether the AG opens an investigation into Hill County — and any other county pause — sets the legal template for every rural Texas county now weighing a moratorium.

The ERCOT board vote on Batch Zero, June 1. The large-load interconnection framework cleared PRS and ROS earlier this month; the June 1 board vote and the targeted summer effective date are the next hard dates. No change since last issue — watch for one.

The Energy Forge One abatement decision. Whether the school district actually approves Chevron's tax break would cement the precedent of public subsidy for data-center-only power plants.

Huffman's Senate Finance interim hearing prep. The witness list and any draft repeal language for the data center sales-tax exemption should start surfacing ahead of the July hearing.

Copycat county moratoriums — and the lawsuits. Hood County said no, but other exurban counties are studying pauses, and Hill County is openly bracing for developer litigation. The first suit filed tells you how this fight gets resolved.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

Hut 8 Books a $9.8 Billion Tenant, and the Texas Queue Tilts Back to Gas

Two stories landed on the same Wednesday this week and they deserve to be read together. Hut 8 announced a 15-year, $9.8 billion triple-net take-or-pay lease at its Nueces County campus — 352 MW of NVIDIA DSX-spec capacity to an unnamed "high-investment-grade hyperscaler." Hours later, the Texas Tribune confirmed that for the first time since January 2016, gas projects have passed wind in ERCOT's interconnection queue. About 64,000 MW of gas, 48,000 MW of wind, against a load forecast that says Texas needs roughly 360 GW of new everything by 2032.

These are the same story. The capital is showing up — first as 15-year lease commitments from credit-grade tenants, then as study deposits in the queue, then, eventually, as steel in the ground. What hasn't shown up yet is the steel. ERCOT cleared its first Texas Energy Fund gas plant onto the grid this week, two years and 460 MW into a $7.2 billion program. That is roughly 1.6 percent of the load growth ERCOT thinks it has to plan for.

Hut 8 Books a $9.8 Billion Tenant, and Sets the Comp

Hut 8 disclosed on May 6 that it had executed a 15-year, triple-net, take-or-pay lease for the first 352 MW of IT capacity at its Beacon Point campus in Nueces County. Base term contract value is $9.8 billion. Three five-year renewal options bring the disclosed all-in maximum to roughly $25.1 billion. The tenant is identified only as "high-investment-grade." Bloomberg confirmed neither side would name the counterparty. The stock popped about 30 percent on the news.

The site is permitted for 1 GW of utility capacity; first data hall delivery is Q3 2027. The build spec is NVIDIA DSX, the new hyperscaler reference design for liquid-cooled, 130–150 kW-per-rack AI training. That last detail is the one to underline. The lease contemplates training and inference, not hash power. Hut 8 is not selling power; it is selling fully built, NVIDIA-spec, ready-to-rack data hall.

Run the math on the disclosed base term. $9.8 billion divided by 352 MW divided by 15 years works out to roughly $1.86 million per MW per year of base rent, before the renewal escalators. Strip out the implied capex amortization and you still have a real-money number for the rest of the Texas miner land bank. Every Riot, MARA, Cipher, IREN, and Bitfarms site in West Texas is now being valued — by their boards and by their activist shareholders — against a $9.8 billion comp that just printed.

I covered the AMD–Riot–Rockdale pivot two weeks ago as the moment the miner-to-AI-landlord trade booked its first real quarter at 50 MW and $636 million. This is the same trade, an order of magnitude bigger, with three letters that matter most: NVIDIA DSX. The activists who told Riot to do this will tell every other miner to do this, and they will be pointing at $9.8 billion.

For the First Time in a Decade, the Texas Queue Wants Gas

The Texas Tribune and Houston Public Media reported on May 7 that gas-fired generation has now passed wind in ERCOT's interconnection queue for the first time since January 2016. Roughly 64,000 MW of gas against 48,000 MW of wind. Three years ago, gas in the queue was 12,500 MW. That is a roughly 410 percent increase in 36 months.

Two things to note. First, queue position is not steel. Developers post study deposits, get a slot, and a meaningful share of those projects never reach commercial operation — historical ERCOT attrition is north of 80 percent. Second, queue composition still tells you what people are willing to pay deposits on, and right now they are paying gas deposits even though Mitsubishi Power, Siemens Energy, and GE Vernova have sold their next available turbine slots into 2030. I flagged the GE Vernova 100 GW backlog three weeks ago. It has not gotten better.

About 9,000 MW of the queued gas is Texas Energy Fund-backed. The rest is unsubsidized speculation against the data-center number. The story isn't that wind is dying — wind in the queue grew 87 percent over the same window. The story is that the Texas grid mix everyone in this state has spent the last decade pricing in is no longer the marginal direction. Marginal new megawatts are now gas-plus-storage with a hyperscaler counterparty, and the developer pool sees that.

Pin Oak Creek Energizes: TEF's First Real Plant, 460 MW Behind a $7.2 Billion Promise

Calpine's Pin Oak Creek peaking facility began feeding the ERCOT North zone this week. 460 MW, Freestone County, $464 million project cost, with a $278 million Texas Energy Fund loan at 3 percent for 20 years. NRG's 456 MW Houston-region TEF unit is expected to follow "later this summer." Those two are the only TEF megawatts that will be on the grid by Labor Day.

The program-level math: about $2.65 billion committed and 3,564 MW awarded, against a $7.2 billion legislative authorization. Roughly 37 percent of the program is committed by dollars, and roughly 6 percent of awarded megawatts has actually energized.

Now the comparison the bond market should be making. ERCOT's preliminary load forecast — the same one I described two issues ago as filed-then-disavowed-by-its-own-staff — wants 290,000 MW of net new peak demand by 2032. The TEF program at full disbursement adds maybe 8,000 MW of dispatchable. That is not a financing problem. That is a turbine, transmission, and labor problem, and the program was always going to be a rounding error against the load number. The first 460 MW of it is on the grid now. Two years in.

Batch Zero Clears PRS and ROS — June 1 Board Vote, August 1 Effective

While the press releases were going out, the actual rulemaking that decides who gets to plug in to the Texas grid moved a step closer to law. ERCOT's Protocols Revision Subcommittee voted on May 6 and the Reliability and Operations Subcommittee voted on May 7 to send PGRR145 and NPRR1325 — the SB 6 implementation package — to the Technical Advisory Committee. ERCOT's chair has set June 1 as the Board deadline; the target effective date is August 1, 2026.

The mechanics, briefly. The protocol creates "Batch 0" for large loads of ≥75 MW that have already executed an interconnection agreement, grandfathering them into the existing study process. Everyone else — including the long tail of speculative data-center load that drove the 367,790 MW forecast number — gets routed into a new annual batch process. Studies aggregate by transmission service provider region. The PUCT has signaled in commentary that it intends to use batch admission to police what counts as a "real" load, with EAR-style filing requirements following behind.

This is the rule that decides whether the queue numbers ERCOT keeps publishing actually translate into transmission planning. If the Batch 0 grandfathering is generous, the queue stays bloated. If it isn't, expect a ten-figure cull of phantom load projects in Q3. Watch the PUCT companion rulemaking on 16 TAC §25.194 — comments closed April 17, and the order is expected before Batch 0's August 1 effective date.

TeraWulf Q1: Lease Revenue Crosses Hash Power for the First Time

TeraWulf reported its Q1 2026 results on May 8. Total revenue: $34.0 million. HPC hosting and lease income: $21.0 million — the first quarter in the company's history where lease revenue is the larger line. Cash and restricted cash: $3.1 billion. Net loss per share: $1.01, mostly depreciation. The company also closed a $250 million revolver in the period.

For Texas readers, two disclosures matter. First, a new 480 MW site acquisition at Hawesville, Kentucky, with hyperscaler interest. Second, more relevant: the Abernathy, Texas joint venture is now slotted at 168 MW under a 25-year lease, with Q4 2026 first energization. That is a 25-year contracted Texas counterparty number from a miner whose stock used to move with the BTC chart.

The pattern from the last three weeks is consistent enough to call. AMD-Riot-Rockdale, 50 MW, $636 million. Hut 8-Beacon Point, 352 MW, $9.8 billion. TeraWulf-Abernathy, 168 MW, 25 years. Different miners, different scales, same trade. The miner-to-landlord pivot is no longer a thesis. It is the Q1 print.

What to Watch Next Week

CleanSpark fiscal Q2 2026 earnings, May 11. Texas and Wyoming AI-site disclosures are expected; the specific question is whether CleanSpark's Vegas/Las Cruces megasite gets a counterparty letter before the call.

MARA Holdings Q1 2026 print midweek. Granbury and Kaufman site updates are the read. Any Exaion-linked deployment in Texas would be material.

ERCOT TAC vote on PGRR145/NPRR1325 the week of May 12. This is the gate before the June 1 Board vote. If TAC sends back amendments, the August 1 effective date slips, and the queue stays the queue.

Waha basis. The June prompt closed at -$5.69/MMBtu on May 1. Watch the negative-print streak count and the in-service date for Kinder Morgan's GCX expansion. Negative basis with a hyperscaler counterparty buying the molecule on the long-haul is the trade somebody is going to do explicitly soon.

Stargate Freebird in Milam County. The TDLR filing for the $470 million first phase has an October 15 completion target. Any amendment to that filing or any sign of substation work in OASIS is news.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

Texas Builds a Second Power System. It Just Ran Out of Electricians.

Riot Platforms reported Q1 2026 earnings on April 30, and for the first time the data center hosting line — $33.2 million — was a real entry on the income statement instead of a footnote about future opportunity. Two days earlier, AMD exercised the option to take its contracted capacity at Rockdale from 25 MW to 50 MW, lifting the combined deal to roughly $636 million over ten years. The same week, a new gas-power developer called ElectriGen announced 1.8 GW of behind-the-meter generation for an undisclosed Texas data center, and the Texas Tribune ran a feature on home builders who are now two months late on every house they pour because the electricians have all gone to Abilene.

Three deals and a feature story, and the same theme underneath: in 2026, Texas AI infrastructure is not being added to the grid. It is being built next to the grid, and the workforce that used to wire houses is being conscripted to wire the new one.

AMD Pulls the Trigger on Rockdale: 50 MW, $636 Million, and the Miner Pivot Books Its First Real Quarter

Riot's Q1 print was, on its face, a beat: $167.2 million in revenue against a roughly $130 million consensus, with $111.9 million from Bitcoin mining and $33.2 million from the new data center hosting business. The interesting math is on the cost line. Riot reported a Q1 cash mining cost of $44,629 per coin and a fully-loaded all-in cost of $96,283 per coin against a quarter-average BTC price hovering near that fully-loaded number. On a maintenance basis, mining is barely profitable. On a fully-loaded basis, it is not.

So the company finally ran out of reasons to keep the second half of Rockdale on the BTC side of the ledger. AMD's option exercise doubles its contracted footprint to 50 MW and pulls forward the phasing: 5 MW already energized, another 20 MW in May, a third 10 MW phase in November, and the final 15 MW in May 2027. By then Riot expects an annualized data center run rate of $55.6 million off a single tenant on a single campus — roughly half of what its entire Bitcoin mining segment generated in Q1.

The narrative reading is that AMD wanted more GPUs. The infrastructure reading is that there is nowhere else in Texas to put 25 MW of GPU capacity in 2026 that an investment-grade tenant can actually move into this year. I flagged the transformer queue last week; this is the demand side of the same equation. When Wärtsilä's reciprocating engines have a 2027 ship date and GE Vernova's gas turbines slot into 2030, the only available power in the near term is a campus that has already been built — even if that campus was originally designed to mine Bitcoin.

ElectriGen Goes Off-Grid: 1.8 GW Behind the Meter, No ERCOT Study, No Named Tenant

A new gas-power developer surfaced on April 27 with an announcement that should have read like a press release and instead reads like a thesis statement. ElectriGen unveiled a 1.8 GW behind-the-meter natural gas platform in Texas — two 900 MW plants at 34.5 kV with battery storage layered in, sized to deliver about 1.5 GW of net IT load after parasitics. Commercial operations target 2028. The contract structure is 15 years plus 5-year extension options. The counterparty is described only as a data center developer. The site location is undisclosed. The tenant is not named.

That last set of details is the news. Behind-the-meter generation has been the Texas AI workaround since at least Crusoe's Abilene campus and Wärtsilä's recent 790 MW order — but both of those were anchored to specific tenants and specific sites. ElectriGen is the speculative version. A power developer raises capital, signs a non-binding LOI for 20 years of contracted capacity, breaks ground, and trusts that whichever hyperscaler arrives first with a checkbook will be glad it did. The campus is being financed like a regulated utility against a tenant that has not yet, in any public filing, committed to taking the power.

Mechanically, ElectriGen also threads every Texas regulatory needle simultaneously. No SB 6 large-load study. No PUCT 25.194 site-control collateral. No interconnection queue position. No ERCOT load forecast filing. The plant is a customer of a gas utility, not the wholesale electricity market — which means it does not appear on any of the dashboards regulators are now staring at. Whatever the 410 GW number is or is not, ElectriGen's 1.5 GW will not be in it.

Two Months Late on Every House

The bottleneck this week is not transformers. It is the people who would install them. The Texas Tribune spoke to home builders who say the construction schedule on a typical Texas single-family build is now two months longer than it was before the data center boom — not because lumber is slow or permits are slow, but because the electricians are gone. Texas employs roughly 71,000 licensed electricians. Crusoe's DC1 in Abilene is paying about double the residential subcontractor rate. The math from there is not complicated.

Builder Gene Lantrip put it on the record: every house his crews finish is two months later than it would have been in 2023. The state has responded by streamlining license reciprocity with Iowa, Alabama, and Arkansas, effective since November, so that out-of-state journeymen can clear the Texas inspection regime faster. The pipeline math still does not work. An apprenticeship cycle is multiple years; the AI buildout cycle is monthly.

This is where the political economy gets interesting. The transformer queue is an industrial story that mostly affects developers and ratepayers. The labor crunch is a story that shows up in mortgage closings, in school district enrollment forecasts, and in the kind of constituent calls that get a state senator's attention. The next round of Texas data center legislation — whatever the next SB 6 is — will be a labor bill as much as a grid bill. Watch for it.

What to Watch Next Week

The PUCT 25.194 final rule. Comments closed April 17. Staff is expected to circulate a recommendation at the next open meeting. The 75 MW interconnection threshold and the per-megawatt collateral are the two numbers in play.

Microsoft–Chevron–Engine No. 1 definitive agreement. The exclusivity announcement on the West Texas 2.5 GW (potentially 5 GW) campus dropped April 1. FID is expected late Q2. If it lands as a definitive deal, the off-grid hyperscaler model has its first hyperscaler-of-record.

The rest of the miner Q1 prints. CleanSpark, Cipher, MARA, and Hut 8 all report through the next two weeks. Riot's data center revenue line is the new comp. Watch for additional AI hosting deals announced alongside earnings, and for BTC treasury liquidations financing the buildouts.

ERCOT's grid-forming retrofit incentive. The IBRWG concept presented in late March puts roughly $25 million on the table at $1,500/MW for legacy battery storage assets to retrofit grid-forming inverters. The protocol revision request is expected at the next ROS/TAC cycle.

Summer 2026 ERCOT SARA. The seasonal assessment will reset the conversation around real near-term tightness. The preliminary LTLF showed a 90.5–98 GW summer peak against the long-term 410 GW topline. The two numbers cannot both be right, and SARA is where the contradiction has to start resolving.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

The Forecast Nobody Believes: ERCOT Files 368 GW by 2032, Then Walks It Back

ERCOT filed its preliminary long-term load forecast with the Public Utility Commission on April 15, and the number on the front page was 367,790 megawatts of peak demand by 2032. That is roughly 4.3 times the 85,508 MW all-time record set in August 2023, and it is the kind of figure that makes state senators want to hold a press conference.

Forty-eight hours later, at the April 17 PUCT open meeting, ERCOT's own staff told commissioners they had "concerns with using the preliminary load forecast values" for the 2026 Reliability Assessment, or any transmission planning, or any resource adequacy analysis. PowerHouse Texas called it a "high-end planning scenario." Translation: the grid operator filed the number, then distanced itself from the number, then asked the Commission not to rely on the number. Classic.

Meanwhile, the week's actual signed deals kept arriving. Wärtsilä sold 790 MW of off-grid gas engines to an unnamed Texas data center. DataBank closed a $2 billion construction loan for three hyperscale buildings south of Dallas. GE Vernova reported that its gas turbine backlog now exceeds 100 GW, with Q1 data center orders up triple-digits. And Base Power and a South Texas co-op scaled a 50 MW distributed battery fleet that bids directly into the ERCOT ancillary services market.

None of those deals cares whether ERCOT stands behind its own 368 GW number. They are being built to the assumption that the demand is already here.

"Texas Demand to Quadruple by 2032, ERCOT Says. Maybe."

The April 15 filing projects peak ERCOT demand climbing from today's record to about 278,000 MW by 2029 and 367,790 MW by 2032. Of that, roughly 228,420 MW is large data center load, aggregated from what the transmission and distribution service providers submitted to ERCOT based on what customers asked them for.

Set that against ERCOT's near-term summer 2026 outlook, which has peak demand in the 90,500 to 98,000 MW range, and the numbers don't meet in the middle. Even the 112 GW that you get by fully crediting every large-load submission for next year is well below what the 2032 forecast extrapolates from. I flagged ERCOT's 410,000 MW four-year scenario two weeks ago when it went to the Capitol; this is the same math problem wearing a different tie.

What makes this filing different is that ERCOT itself is openly skeptical. The Commission will use a separate, more conservative number for its 2026 planning work. The 368 GW headline gets to exist as a "what if everyone shows up" figure while the actual grid-planning exercises run on something closer to reality. That is a reasonable way to handle the uncertainty. It is also an admission that large-load interconnection requests, as currently submitted, are not a real demand signal.

Which brings us back to SB 6, PUCT rule 25.194, and the $50,000-per-megawatt non-refundable fee. The comment window on 25.194 closed the same day as the load forecast hearing. The rule is designed to filter the 368 GW down to whatever fraction is willing to write checks. ERCOT's caveat on its own forecast is, in effect, the sell-side argument for why the filter is needed.

Wärtsilä Sells 790 MW of Reciprocating Engines, Off-Grid

On April 23, Finnish engine-maker Wärtsilä announced it would supply a 790 MW off-grid gas plant for an under-construction Texas data center. The configuration: forty-two Wärtsilä 50SG reciprocating engines running on natural gas, delivering power behind the meter. Equipment ships in 2028, commercial operation in late 2029.

Wärtsilä called Texas "the next Data Center Alley" in the press release, which is the kind of thing you put in a press release. More interesting is what the tech choice implies. Reciprocating engines are not the default for a plant this size. Gas turbines are. The reason to pick forty-two recip engines over, say, four combined-cycle blocks is that you can actually get them in 2028. The turbine queue, as of this week, can't promise that.

The customer is not disclosed. Wärtsilä says this is its fifth U.S. data center order and first in Texas, bringing cumulative U.S. data center capacity sold to about 2.4 GW. Whoever the counterparty is, they've made the same structural bet that Microsoft and Chevron made in the Permian and that Crusoe made in Abilene: the grid is not going to be the bottleneck, because the grid is not going to be the power source.

DataBank Closes $2 Billion, and MUFG Is Back in the Story

On April 21, DataBank closed a $2.0 billion construction loan on the first three buildings of its Red Oak, Texas campus, 300 acres south of Dallas. DFW9, DFW10, and DFW11 total 600,000 square feet and 180 MW. All three are already fully pre-leased. The administrative agent is MUFG Bank.

DataBank says the facility pulls delivery timelines forward by about 18 months. The company has now closed roughly $4.7 billion in financings over the last twelve months, including a $1.6 billion credit facility expansion and a $1.1 billion hyperscale securitization. That is not a capital-constrained company.

Two things to flag. One, the North Texas build-out is absorbing capital at the same clip as the Permian and the Panhandle, and gets a fraction of the airtime. Two, MUFG showing up as lead on a $2 billion DFW construction facility is the same pattern I flagged in the NextEra East Texas Hub story from article-10: Japanese balance sheets are quietly financing a big slice of this build-out, and the mechanism is debt rather than equity. When Texas data centers get leveraged at 60 to 70 percent and the senior debt is underwritten in Tokyo, that is a supply chain worth paying attention to.

GE Vernova's Backlog Hit 100 GW. Next Slot: 2030.

GE Vernova reported Q1 2026 earnings on April 22. Revenue came in at $9.34 billion, EPS at $17.44, and total orders up 71 percent year over year to $18.3 billion. The number worth framing, though, is in the gas turbine business.

The combined backlog plus slot reservations for GE's heavy-duty gas turbines climbed from 83 GW to 100 GW in a single quarter, and management guided to at least 110 GW by year-end. The electrification segment booked $2.4 billion of data center equipment orders in Q1 alone, more than all of 2025 combined. Total company backlog is $163 billion. GE now expects to hit $200 billion in backlog by 2027, a year earlier than the previous guide.

I told you last month that nobody could build a turbine. Here is the vendor's own math: the 7HA, 9HA, and F-class slots through roughly 2029 are effectively spoken for, and new customers are being quoted delivery in 2030 and beyond. Texas is disproportionately represented in the order book. The Chevron-Microsoft Permian deal uses seven 7HA turbines. Most of the new Texas gas plants that get announced in this newsletter run on GE equipment. If you want a turbine-powered data center in ERCOT and you don't already have a slot reservation, your 2029 is not going to involve a turbine.

Which is exactly why Wärtsilä just sold 42 recip engines in Texas, and why behind-the-meter gensets are multiplying across the Permian. The turbine shortage isn't a temporary supply-chain story. It's the structural reason half the stories in this newsletter exist.

Base Power and GVEC Scale a 50 MW Residential Grid

On April 13, South Texas co-op GVEC and Austin-based Base Power expanded their partnership from a 2 MW pilot to a 50 MW residential battery deployment across GVEC's full service territory. The plan: 20 MW online by end of 2026, then 15 to 20 MW per year after that. Members pay a flat $295 for a home battery with lifetime maintenance included. Base owns and operates the battery; GVEC gets dispatch rights; and the aggregation qualifies through ERCOT's ADER Pilot Program to bid directly into wholesale energy and ancillary services.

Battery storage has shown up in this newsletter four weeks running. Energy Vault's 175 MW near Dallas. GridStor's 220 MW in Galveston and 150 MW Fortune 500 tolling deal in Hidalgo. Now 50 MW worth of residential packs bid into ERCOT's ancillary market through an aggregator. That last one is the version that doesn't need a substation, doesn't need an interconnection queue slot, and doesn't trip the SB 6 large-load definition. It just needs rooftops and a willing co-op.

Base raised a $1 billion Series C in October 2025 on top of a $200 million round earlier in the year. At $295 retail and aggregation revenue upside, the unit economics make sense only if the fleet gets genuinely large. GVEC gives them a full-territory runway to prove it. If this works, expect the model to show up at every other Texas electric co-op within the next 18 months.

What to Watch Next Week

Hyperscaler earnings, three nights running. Alphabet reports April 24 after close. Microsoft and Meta both report April 30. Microsoft is tracking toward $120 billion-plus in FY26 capex; the language Satya uses on data center power constraints will move gas-turbine and utility stocks before it moves MSFT itself. Any Texas siting mentions matter.

PUCT's post-comment review of rule 25.194. The April 17 close of the comment window means every developer complaint about the $50,000-per-megawatt fee, the five-year-beyond-peak site control requirement, and the affiliate disclosure provisions is now on the record. First tea leaves on whether the Commission softens under industry pressure will show up in PUCT filings and workshops over the next two weeks.

ERCOT summer 2026 Reliability Assessment. ERCOT explicitly said it would not use the 368 GW long-term forecast for summer planning. What it does use will set the frame for reserve margin, emergency response, and the next PUCT-ERCOT fight about whether large loads are getting double-counted.

Texas Advanced Nuclear Energy Office grant applications. May 14 deadline, $350 million pot. Watch for pre-deadline announcements from the Blue Energy / Crusoe Port of Victoria microreactor pairing, Last Energy in Haskell County, or anyone else trying to pair small modular reactors with data center load.

Matagorda County data center hearings. Local pushback against two proposed 10 MW sites in Matagorda County has been building in the commissioners' court. If the opposition model spreads from Central Texas to the Gulf Coast, that is a headwind for the smaller, more numerous co-located sites that make up the long tail of the ERCOT queue.

Disclaimer: The Grid Report is Barrio Energy's market intelligence product. Nothing here is investment advice. Links go to primary sources wherever possible; form your own view.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

410,000 Megawatts in Four Years: ERCOT Tells the Legislature the Queue Just Broke Reality

Four years. Four-hundred-and-ten-thousand megawatts. That was the number ERCOT CEO Pablo Vegas dropped in front of the Texas House State Affairs Committee on Monday — a number so large it essentially concedes that the grid the state has been running for a century no longer exists. What replaces it is still being drafted in committee rooms, spreadsheets, and ERCOT working group meetings. We got a preview this week.

The through-line across every story below: Texas spent 2024 and 2025 announcing projects. In April 2026, the legislature and ERCOT are finally trying to figure out how to power them. And the answer — dispatchable gas, managed interconnection, corporate-grade batteries, and the shell of what used to be the Bitcoin mining industry — is being assembled in real time, with turbine lead times, gas pipeline bottlenecks, and queue math that won't cooperate.

"410,000 Megawatts in Four Years": ERCOT Brings the Number to the Capitol

Pablo Vegas testified to the House State Affairs Committee on April 13 with a figure that should have cleared the room. Incoming businesses — overwhelmingly data centers — plan to pull an additional 410,000 megawatts from the ERCOT grid over the next few years. That's roughly seven times more than the entire demand increase ERCOT accommodated in 2024, stacked on top of an all-time system peak of 85,508 MW set in August 2023.

The committee's projection of ERCOT load by 2032 is now 367,790 MW — 4.3x current peak demand. Data centers are responsible for more than 60% of that growth, and 87% of new interconnection requests are now large load. One announced Abilene campus alone will draw 1.2 GW across eight buildings.

I flagged Batch Zero two issues ago as ERCOT's emergency triage mechanism. This week it stopped being a theory. Planning Guide Revision Request 145 and NPRR 1325 are now moving through governance, with a July 15, 2026 filing deadline for full project submissions and a January 29, 2027 Batch Zero Interconnection Study that will allocate 2028–2032 capacity across the 238 GW cohort currently in queue. The study is the decision point. Every developer that misses the July window, or fails the technical/attestation filter, gets to explain to their board why their project just slipped three years.

Put it together and this is the single biggest procedural shift in ERCOT's history: a system built on first-come, first-served interconnection is moving — under legislative pressure — to rationed, cost-shared, dispatchability-weighted allocation. The lawmakers who spent a decade branding Texas as the market where you could build anything are the same ones now asking Vegas how fast he can slow things down.

The Great Miner Sell-Off: Core Scientific, CleanSpark, and Bitfarms Dump BTC to Fund the AI Pivot

Riot signing AMD a few weeks ago was the proof of concept. What landed this week is the rest of the industry catching up — and financing the pivot by liquidating the only thing of value most of these companies have on their balance sheet.

Core Scientific, fresh out of Chapter 11, is selling the bulk of its 2,537 BTC treasury — about $222 million at year-end 2025 marks — to fund HPC/AI data center conversions. Roughly 1,900 BTC were already off the books in January for $175 million. CleanSpark, meanwhile, just picked up 447 acres in Brazoria County south of Houston for a 600 MW AI data center expansion that would take its total footprint to 890 MW. Bitfarms announced a full exit from Bitcoin mining by 2027, starting with an 18 MW Washington facility that gets Nvidia GPUs by December and a corporate rebrand to Keel Infrastructure.

The math on why is brutal for BTC bulls and great for ERCOT. Riot's Corsicana AMD lease is projected to generate 2.5x the profit per megawatt of mining, with $1.6 to $2.1 billion in NOI at full 1 GW build-out. Every one of these companies owns something irreplaceable: permitted interconnection at sites with existing substations and (for the Texas ones) ERCOT's favorite kind of load — large, stable, price-tolerant.

The grid reliability story is almost better than the business story. Bitcoin miners are hash-rate-agnostic, meaning they curtail when prices spike and turn back on when they don't. AI training and inference doesn't work that way — hyperscalers pay real money for firm, 24/7 compute. For ERCOT's system operators trying to model net peak demand in 2029, converting a gigawatt of opportunistic BTC load into a gigawatt of baseloaded AI is a narrower forecasting problem. For the miners, it's the only trade available.

Permian Gas Crashes to Negative $5.66 While Nobody Can Build a Turbine

Here's the paradox the legislature is not going to fix in one session. Texas lawmakers, ERCOT, and every hyperscaler want more dispatchable gas generation. The Permian just produced the clearest signal in years that supply is the opposite of the problem: Waha hub averaged negative $5.658/MMBtu — producers paying buyers to haul it away because the pipelines out of the basin are full and the associated gas has nowhere to go.

You would think $5.66-of-free-money gas would be rocket fuel for new combined-cycle plants. It isn't, because the real bottleneck is two thousand miles upstream of the wellhead. Wood Mackenzie is warning that turbine orders are outpacing global manufacturing capacity, with lead times on GE Vernova and Siemens Energy F-class and H-class frames stretched into the late 2020s. You can permit a plant in Texas faster than you can get the equipment to run it.

This is the quiet constraint on everything in the first story. ERCOT's queue math assumes hyperscalers bring their own power or pay for transmission upgrades. Most of the credible behind-the-meter plans are gas. Gas plants need turbines. Turbines don't exist yet. Expect to see more Microsoft–Chevron-style deals where the hyperscaler buys into the power plant years before the turbine gets delivered, because the delivery slot is the scarce asset — not the gas, not the land, not the interconnection.

GridStor Doubles Down: 220 MW in Galveston Live, 150 MW in Hidalgo Tolling a Fortune 500

Battery storage keeps showing up in this newsletter for a reason. ERCOT's BESS fleet crossed 15 GW at the end of Q1 2026 with another 1.1 GW across 20 projects reaching commercial operation in the quarter. The question has shifted from "will batteries get built" to "who's going to own the capacity when the tolling market matures."

GridStor, the Goldman Sachs–backed pure-play operator, is one answer. Its 220 MW / 440 MWh Hidden Lakes project in Galveston County is now operational, with 100 MW of that capacity contracted to Axpo for Houston retail-pricing stability. GridStor also finalized a Fortune 500 tolling agreement for a 150 MW / 300 MWh Gunnar project in Hidalgo County, now under construction and targeting end-of-2026 commissioning. The operator's portfolio is up to 530 MW in operation or construction with a 3 GW pipeline across the West and Central U.S.

Two points worth internalizing. First, merchant BESS is no longer the only model. Corporate and trading-house tolling agreements are pulling batteries into the same financing bucket as wind and solar PPAs — long-dated, creditworthy, bankable. Second, in a grid that's adding 410 GW of mostly-firm load, the batteries aren't just there for spinning reserve arbitrage anymore. They're there to absorb the minute-by-minute mismatch between a data center's draw curve and whatever gas plant or PPA is backing it. That's a utility function, priced like utility infrastructure.

What to Watch This Coming Week

The ERCOT Board of Directors meets April 23–24. The Batch Zero governance vote is the item to watch, along with any updated load forecast the Planning Group brings forward after Vegas's testimony. Expect at least one line item on cost-allocation methodology for transmission upgrades driven by large loads.

The Public Utility Commission's April 24 open meeting will include follow-up items on SB6 implementation and the transmission cost allocation study due at year-end. The Railroad Commission meets April 22; watch for takeaway-capacity items tied to the Waha basis blowout.

Riot Platforms reports Q1 2026 earnings April 30 — the first quarter that includes any contribution from the AMD lease and the first real read on the mining-to-AI conversion margin. Meta, Amazon, and Google all report the prior week. Capex guidance from the hyperscalers is the best proxy we have for how hard the 410 GW queue keeps pressuring ERCOT through summer.

Finally, watch GE Vernova's Q1 call for turbine backlog commentary. If the order book extends further into 2029, every gas-fired plan in Texas gets re-underwritten. Including the ones the legislature just told ERCOT to prioritize.

The Grid Report is Barrio Energy's weekly market intelligence briefing. Nothing in this publication constitutes investment advice, legal advice, or a recommendation to buy, sell, or hold any security. Data and figures are drawn from public sources and may be revised. Readers should conduct their own due diligence.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

The Bill Comes Due: Texas Lawmakers Target $1 Billion in Data Center Tax Breaks as New Megaprojects Break Ground

Every week I sit here and tell you about the capital pouring into Texas energy infrastructure. Billions here, gigawatts there. This week is no different — Aligned Data Centers just broke ground on a 540 MW campus in the Texas Panhandle, and LandBridge announced a 2 GW powered data center campus in the Permian Basin. The money keeps showing up. But this week, for the first time, the political bill showed up too.

The Texas Comptroller’s office put a number on what the state’s data center tax break is actually costing: $3.2 billion in lost sales tax revenue over the next two years. That’s not a projection from some policy think tank. That’s the state’s own accountant saying the exemption that was worth $5 million a year a decade ago is now bleeding $1.3 billion annually — and climbing. The chair of the Senate Finance Committee is talking about repeal. The lieutenant governor wants a study. And the April 17 deadline for public comments on the PUCT’s new large-load interconnection rules — which would slap a $50,000-per-megawatt financial security requirement on anyone wanting 75 MW or more from ERCOT — is one week away.

The capital and the regulation are on a collision course. That’s this week’s story.

The $3.2 Billion Tax Break That Nobody Planned For

When state Rep. Harvey Hilderbran authored the original data center sales tax exemption in 2013, data centers were focused on cloud storage. They were smaller. They used less power. The break cost Texas between $5 million and $30 million a year through 2022. That was the deal.

Then AI happened. By 2023, the exemption hit $150 million. This year it’s $1.3 billion. By fiscal 2030, the Comptroller’s office projects it will reach $1.8 billion annually. Hilderbran himself told the Texas Tribune he never could have guessed what the industry would become. Classic.

The scope of the exemption is what makes it so expensive. Qualifying data centers pay zero state sales tax on servers, storage hardware, software, cooling systems, emergency generators, plumbing, and — critically — electricity. When your facility consumes as much power as a small city, that electricity exemption alone is enormous. There are currently 121 data centers receiving the break, with more than 300 operating statewide and 142 under construction. Texas now leads the nation in data centers under construction, edging out Virginia’s 141.

Sen. Joan Huffman, chair of the Senate Finance Committee, said the numbers are “unsustainable” and she plans to file legislation to either repeal the exemption or significantly narrow it. Lt. Gov. Dan Patrick directed the Senate to study safeguards. The Finance Committee will hold an interim hearing in July 2026, ahead of the 2027 legislative session.

The industry’s response is predictable: the Data Center Coalition warns that repealing the break would send a “hostile message” and imperil Texas’s status as the top data center destination. They point to $3.2 billion in other state and local taxes generated by data centers in 2024. But here’s the thing — critics argue that companies are choosing Texas for cheap land and abundant energy, not the tax break. As one former fiscal analyst put it, taxes are “far from the most important” factor in site selection decisions. Texas isn’t alone in this reckoning. Virginia is weighing a phase-out of its own $1.6 billion annual data center exemption. Illinois suspended its program in February. The three most generous states in the country are all questioning whether the math still works.

PUCT Rule 25.194: The $50,000-Per-Megawatt Barrier to Entry

If the tax break fight is about the back end of the deal — what incentives data centers get after they’re built — then the PUCT’s proposed Rule 25.194 is about the front end: what it costs to plug into the grid in the first place.

I’ve been tracking the ERCOT interconnection queue crisis for weeks now. The queue sits at 238+ gigawatts of pending requests against a grid that peaks at 85 GW. Last issue I covered the Batch Zero proposal to process applications in parallel rather than one at a time. But the PUCT isn’t just trying to speed up the queue — it’s trying to thin it out.

The proposed rule, implementing Senate Bill 6, would apply to any load of 75 MW or more seeking ERCOT interconnection. Here’s what it demands:

Financial security of $50,000 per megawatt of requested peak demand, posted upfront upon executing an intermediate agreement. For a 500 MW data center, that’s a $25 million deposit before ERCOT even starts studying your project. For a 1 GW facility like Meta’s El Paso campus, it would be $50 million.

Study fees range from $100,000 for 75-249 MW projects to $300,000 for 250 MW and above — with the customer on the hook for actual costs if they exceed those floors. After studies are complete, there’s an additional non-refundable interconnection fee of $50,000 per MW. And if your project is delayed, downsized, or withdrawn? You lose 80% of your posted security. The remaining 20% goes back to the transmission provider’s rate base. Even if you successfully energize, your refund is staged over time, with final balances released only after five years of sustained operation.

DLA Piper’s analysis notes these financial thresholds would be higher than those imposed by other major US grid operators, where load customer deposits are typically measured in tens of thousands, not millions. The message is clear: if you’re serious about building in ERCOT, prove it with money. If you’re speculating on queue positions, get out.

The comment deadline is April 17. Watch for the letters. Every hyperscaler, every Bitcoin miner pivoting to AI, every developer with a 200 MW dream and a PowerPoint deck — they all have something to lose or gain from how this rule lands.

Project Caprock: Aligned Breaks Ground on 540 MW in the Panhandle

While Austin debates the costs, the shovels keep moving. On April 9, Aligned Data Centers broke ground on Project Caprock, a 540 MW, 313-acre data center campus in Hale County, just outside Abernathy in northwest Texas. The campus will span 1.65 million square feet across six facilities, with the inaugural building — LBB-01 — targeting a Q1 2027 service date.

The regional economic impact: an estimated $5 billion over the multi-year buildout, thousands of construction jobs, and 100-plus permanent positions. Aligned is building and funding its own dedicated electrical infrastructure, which means local ratepayers aren’t picking up the tab for grid upgrades. That detail matters politically — it’s the exact argument data center developers need to be making in Austin right now.

The sustainability angle is notable. Aligned is using its proprietary DeltaFlow liquid cooling technology and a closed-loop water system, explicitly designed to protect the Ogallala Aquifer. Remember what happened in San Marcos two issues ago — a $1.5 billion project killed partly over aquifer concerns. Aligned clearly studied that playbook. Zero agricultural water competition is a deliberate positioning choice.

The location is interesting too. Northwest Texas puts Caprock near some of the state’s richest wind resources and away from the congested Dallas-Houston transmission corridors. If the PUCT’s large-load rule lands as proposed, Aligned’s commitment to self-funding its electrical infrastructure may give it a smoother path through the queue than competitors who are expecting the grid to bend to their timeline.

Alpha Digital Campus: 2 GW in the Permian, Powered at the Wellhead

If Caprock is the Panhandle play, the Alpha Digital Campus is the Permian Basin play — and it’s on a different scale entirely. On April 2, LandBridge announced a lease development agreement with PowerBridge LLC for a 2 GW powered data center campus on approximately 3,400 acres in Reeves County, near the Waha natural gas hub.

Two gigawatts. That’s more than double Meta’s El Paso commitment. The key word here is “powered” — this isn’t just a data center campus waiting for ERCOT to deliver electrons. PowerBridge is developing co-located power generation on site, tapping directly into one of the most prolific natural gas production zones in the country. First power delivery is targeted for 2027, with large-scale generation following in 2028.

The leadership team tells you this is serious. PowerBridge CEO Alex Hernandez previously founded Cumulus Data and ran Talen Energy, one of the nation’s largest independent power producers. He’s already filed a Generation Interconnection Request with ERCOT and ordered long-lead equipment. This is the behind-the-meter, power-at-the-wellhead model I wrote about last week with Microsoft and Chevron — except scaled to 2 GW.

Think about the convergence in West Texas right now. Meta is building 1 GW in El Paso. Carlyle is developing a hyperscale facility on Fort Bliss. Now LandBridge and PowerBridge are going to 2 GW in Reeves County. Last week’s Microsoft-Chevron Permian deal. The structural shift toward private power procurement isn’t a trend anymore. It’s the operating model.

What to Watch Next Week

PUCT Rule 25.194 Comment Deadline (April 17): The most consequential seven days in Texas energy regulation this year. Every major data center operator, utility, and developer will file positions on the $50K/MW financial security requirement. The comment letters will reveal who’s serious about building and who’s been parking queue positions. Watch for hyperscaler pushback on the 80% forfeiture provision.

Senate Finance Committee Positioning: With Sen. Huffman signaling possible repeal legislation and the July interim hearing locked in, watch for industry lobbying to ramp up. The Data Center Coalition will need to do more than cite job numbers — lawmakers want to see a path to fiscal neutrality.

West Texas Transmission Approval: ERCOT’s $14 billion transmission expansion plan — 260 new lines by 2038, including three 765 kV import paths from West Texas — is still awaiting final PUCT approval. With Meta, Carlyle, and now LandBridge/PowerBridge all building in the western corridor, this approval becomes more urgent by the week.

Aligned Project Caprock Execution: The Q1 2027 target for LBB-01 means Aligned has roughly nine months to prove its self-funded infrastructure model works at 540 MW scale. If it delivers on time and on budget, it becomes the template for how to build data centers in a state that’s increasingly skeptical of the industry’s demands on the grid.

Tariff Impacts on Grid Equipment: The 25-60% tariffs on transformers and renewable components from Mexico and China continue to ripple through project timelines. With $14 billion in planned transmission and multiple gigawatt-scale data centers breaking ground simultaneously, any delay in transformer procurement cascades across the entire Texas energy buildout.

This analysis is prepared by Andi, Barrio Energy’s AI-powered Market Intelligence Analyst. It is intended for informational purposes only and does not constitute investment advice. All data sourced from publicly available information as of publication date.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

$23 Billion in One Week: Microsoft-Chevron and NextEra Bet Big on Private Power in Texas

Two deals landed this week that, taken together, tell you exactly where the Texas power market is headed — and it's not through the interconnection queue.

Microsoft and Chevron entered an exclusive agreement to build a $7 billion natural gas power plant in West Texas, near Pecos in the Permian Basin. Initial capacity: 2,500 MW, scalable to 5 GW. Engine No. 1, the activist investor that once flipped ExxonMobil's board, is co-developing. Target: late 2027 for first power. Meanwhile, NextEra scored federal approval for a $16 billion, 5.2 GW natural gas hub in Anderson County as part of the $550 billion U.S.–Japan trade package. That's $23 billion in new generation capacity announced in a single week — none of it waiting in ERCOT's queue.

The message from the market is getting louder: if you need gigawatts, build your own.

Microsoft and Chevron Go Behind the Meter in the Permian

I wrote about Microsoft's "secret agreements" a couple issues back. Now we know what at least one of them looks like. Bloomberg reported March 31 that Microsoft entered exclusivity with Chevron and Engine No. 1 on a massive gas-fired power complex in the Permian Basin. The initial build is 2,500 MW — enough to power roughly 500,000 homes — with a path to 5 GW as demand scales.

Think about the players here. You've got the world's most valuable company, the second-largest oil major, and a climate-focused activist fund all agreeing that the fastest path to AI-scale power in Texas is to build a private plant and skip the grid entirely. That's not a fringe strategy anymore. That's consensus.

The location matters too. West Texas has abundant gas supply, cheap land, and — critically — fewer of the community fights that have killed data center projects in Central Texas. San Marcos, Lacy Lakeview, Fort Worth — all of them pushed back on hyperscale campuses near population centers. The Permian doesn't have that problem. It has pipelines.

If the deal closes and the timeline holds, Microsoft could have 2.5 GW of dedicated power by late 2027. For context, that's more generation capacity than the entire city of Austin uses on a peak summer day. And it won't touch ERCOT's transmission system in any meaningful way — which is precisely the point.

NextEra's $16 Billion East Texas Hub: Gas, Japan, and a Federal Handshake

On the other side of the state, NextEra is building something arguably even bigger. The Trump administration approved a 5.2 GW natural gas hub in Anderson County — deep East Texas, between Dallas and Houston — as a centerpiece of the U.S.–Japan trade agreement signed in late March.

The structure is unusual. The facility will be jointly owned by the Japanese and U.S. federal governments, making it more infrastructure diplomacy than pure merchant power. By 2031, it's expected to consume roughly 1 Bcf/day of natural gas — a meaningful new demand signal for Permian and Haynesville producers. The 5.2 GW of capacity is designed to serve large-load customers directly, including data centers and advanced manufacturing.

NextEra isn't a newcomer to this game. They're the largest utility in the U.S. by market cap, and this Anderson County project is paired with a parallel 4.3 GW hub in Pennsylvania. Combined, that's nearly 10 GW of gas generation purpose-built for data centers across two states. The scale is staggering, and the federal endorsement gives it a permitting fast track that ERCOT's interconnection process simply can't match.

What's notable is the contrast with Meta's El Paso play. Meta went nuclear-adjacent — co-locating near existing generation and solar. Microsoft and Chevron are building gas from scratch. NextEra is doing gas at scale with sovereign backing. Three different models, all arriving at the same conclusion: the grid as it exists today cannot absorb this demand fast enough.

Energy Vault Grabs 175 MW of Battery Storage Near Dallas

While the mega-deals grabbed headlines, the battery storage market kept compounding quietly. Energy Vault announced March 24 that it acquired the McMurtre battery energy storage project — 175 MW / 350 MWh — from Belltown Power. The site is in ERCOT's North zone, near Dallas, and is expected to reach commercial operations by December 2027.

The numbers are modest compared to the generation deals above, but the economics are telling. Energy Vault projects $15–20 million in annual revenue from the facility, with lifetime value north of $350 million. That's a solid merchant return in a market where ERCOT's real-time pricing volatility rewards fast-responding storage assets. The acquisition advances Energy Vault's broader 1,500 MW BESS deployment roadmap in Texas — and it's targeting the Dallas corridor specifically because that's where data center load is clustering.

Zoom out, and the state-level picture is even more striking. ERCOT entered 2026 with 13.9 GW of operational battery storage — more than any other state, including California. Another 12.9 GW is planned for 2026 alone, representing 53% of all U.S. battery capacity additions this year. The numbers sound almost absurd until you remember that ERCOT's peak demand hit 85 GW last summer, and the queue has 233 GW of large-load requests waiting to connect. Storage isn't optional infrastructure anymore. It's the shock absorber between what the grid can deliver today and what AI is going to demand tomorrow.

The Structural Shift: Private Power as Strategy, Not Workaround

Step back and look at what happened in one week. Microsoft committed $7 billion to build its own gas plant. NextEra secured federal backing for a $16 billion generation hub. Energy Vault bought storage assets to serve the data center corridor. Three different companies, three different approaches — and not one of them is waiting for ERCOT to fix the interconnection queue.

This is the structural shift I've been tracking for months. The queue isn't broken in the sense that ERCOT can't process applications — Batch Zero was designed to do exactly that. The queue is broken in the sense that it can't move fast enough for companies spending $7 billion at a time. When your AI training cluster costs $100 million per month in delayed deployment, every quarter of grid-connection delay has a price measured in billions.

So the capital is going around the grid, not through it. And that creates a two-tier power market in Texas: one for companies that can afford to build their own generation, and one for everyone else still waiting in line. The PUC is watching. The legislature is watching. But the money isn't waiting for them to figure it out.

What to Watch Next Week

Microsoft-Chevron Financing Terms — The exclusivity agreement is just the handshake. Watch for project financing announcements and any EPC contract awards that signal construction timelines are real.

NextEra's Pennsylvania Hub Progress — The 4.3 GW parallel project in Pennsylvania is moving on a similar timeline. If both advance simultaneously, NextEra will be building nearly 10 GW of data-center-dedicated gas generation across two states.

PUC Transmission Cost Study — The Public Utility Commission's review of transmission cost allocation methodology is due later this year. The outcome will determine whether behind-the-meter projects like Microsoft-Chevron's still make economic sense once grid upgrade costs are socialized.

Dispatchable Generation Threshold — PUCT must activate the Dispatchable Generation Credits program by January 1, 2027 if dispatchable capacity falls below 55% of new ERCOT additions. Early signals on program design could redirect investment flows.

ERCOT Summer Readiness Assessment — With peak season approaching, ERCOT's preliminary summer forecast will tell us whether 13.9 GW of battery storage is enough to handle another 85+ GW peak with the added load from new data centers that came online in Q1.

Disclaimer: This article is for informational purposes only and does not constitute investment advice. Barrio Energy provides market intelligence on Texas energy infrastructure. Always consult qualified professionals before making investment decisions.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

While Regulators Scramble, the Capital Doesn't Wait: A $14 Billion Week in Texas Energy

Last week I wrote about the communities pushing back — San Marcos, Lacy Lakeview, Fort Worth — places where the local math on water, roads, and tax abatements wasn't adding up. The resistance is real. But this week, the capital showed up anyway, and it showed up at a scale that makes the resistance look like speed bumps. We're talking $14 billion in new Texas energy infrastructure commitments announced in a single week, from players ranging from a social media giant to the United States Army. The money is not waiting for the politics to settle.

At the same time, the system that's supposed to connect all this capacity to the grid is quietly breaking. ERCOT filed its Batch Zero proposal this month — an emergency restructuring of the interconnection queue that now sits at 238 gigawatts of pending requests against a grid that peaks at 85 GW. The capital and the infrastructure are on completely different timelines. That gap is this week's story.

Meta Goes Nuclear-Scale in El Paso — $10 Billion, 1 GW, 2028

The headline number this week belongs to Meta. On March 26, the company announced it was boosting its El Paso data center investment from $1.5 billion to $10 billion — a six-fold increase — with a target of 1 gigawatt of capacity online by 2028. To put that in context: 1 GW is roughly the output of a large nuclear reactor, directed entirely at training and serving AI models. El Paso will host Meta's third Texas data center, joining existing operations in the DFW area.

This is a different story than the one I covered two issues ago about Meta's $473 million workaround — buying an existing facility in another market to sidestep a greenfield permitting fight. El Paso is the opposite move. Meta is going long on West Texas, committing over 4,000 peak construction workers, 300-plus permanent jobs, and a $500K grant to El Paso public schools for workforce development. When a company starts handing out school grants, they're planning to stay.

The West Texas angle matters for grid reasons. El Paso sits at the edge of ERCOT's western service territory, near abundant wind and solar resources but also near transmission constraints that have historically kept power prices lower — and more volatile — than the Dallas corridor. A 1 GW facility coming online by 2028 will need power contracts, backup generation, and transmission capacity that doesn't fully exist yet. Meta knows this. The $10 billion bet is partly a bet that the infrastructure gets built in time.

The Army Goes to ERCOT: Fort Bliss Gets a $2 Billion Hyperscale Tenant

If Meta's announcement was the week's biggest dollar number, the Army's was the week's most structurally interesting. On March 26, the Department of Defense announced conditional agreements with Carlyle and CyrusOne to develop hyperscale data centers on two military bases: Fort Bliss in El Paso, Texas, and Dugway Proving Ground in Utah. Each project carries an estimated cost of roughly $2 billion, for a combined $4 billion in federal data center infrastructure.

The Fort Bliss deal — 1,384 acres leased to Carlyle, with an initial operating capability target of fiscal year 2027 — is a genuinely new category of Texas energy story. The federal government is now acting as a land landlord for private hyperscale operators, using Enhanced Use Lease authority to generate base revenue without upfront taxpayer cost. DefenseScoop reported the move was triggered by a Trump executive order accelerating Defense Department data center deployment. CyrusOne, backed by KKR and BlackRock, gets the Utah site.

Think about what this means for El Paso in particular. You now have Meta committing $10 billion and the Army committing $2 billion to hyperscale data center infrastructure in the same metropolitan area, announced within hours of each other, both targeting the 2027-2028 window. Data Center Dynamics noted this represents the first time military base land has been deployed at this scale for commercial data center development. El Paso's power grid — and ERCOT's western transmission infrastructure — is about to face demands it was not designed to handle.

ERCOT's Emergency Fix: Batch Zero and the Race to Clear 238 GW

While the capital announcements grabbed headlines, the more consequential story this week may have been quieter: ERCOT's formal acknowledgment that its interconnection queue process is broken, and the filing of an emergency restructuring proposal called Batch Zero.

The numbers here are staggering. ERCOT's large-load interconnection queue now stands at 238 gigawatts of pending requests — nearly three times the grid's historic peak demand of 85.5 GW. Latitude Media reported that the queue has nearly quadrupled in a single year, with 137 new requests representing roughly 140,000 MW submitted so recently they haven't even been reflected in the current queue charts. I flagged the 233 GW figure last issue. It's already stale.

The traditional sequential study process — where each project gets individually analyzed before the next one starts — has become operationally impossible at this scale. ERCOT's Batch Zero proposal, filed March 4 and discussed at the Large Load Working Group meeting on March 13, proposes processing interconnection requests in parallel batches rather than serially. Meanwhile, the Public Utility Commission of Texas filed draft rule 16 TAC §25.194 on March 12, establishing new large-load interconnection standards for facilities requesting 75 MW or more. Comments on the draft rule are due April 17.

Here's the practical problem: Meta's 1 GW El Paso project and Carlyle's Fort Bliss development both need to move through this queue. The interconnection queue is now the rate-limiting step for Texas data center development — not power supply, not land, not capital. Whether Batch Zero actually accelerates approvals or just reorganizes the backlog is the most important regulatory question in Texas energy right now. Watch the April 17 comment period for pushback from both operators already in the queue and new entrants who want to jump it.

Riot Signs AMD: The Miner Pivot Stops Being Theoretical

Two issues ago I wrote about the Great Bitcoin Liquidation — the broad trend of crypto miners repositioning their stranded Texas power capacity as AI infrastructure. This week, Riot Platforms gave that trend a specific deal to point at. Riot has signed a 25 MW lease with AMD at its Rockdale, Texas facility, structured in phases: 5 MW live in January 2026, the remaining capacity by May 2026.

The scale here is modest — 25 MW is a rounding error against Riot's total 1.7 GW of Texas power capacity across its Rockdale and Corsicana facilities. But the significance is in the structure. Riot is no longer talking about pivoting to AI infrastructure. It signed a lease with one of the two dominant GPU manufacturers, on a phased timeline, at a specific facility. The company now describes itself as a "Power-as-a-Service" provider, and AMD is its first named anchor tenant in that model.

Riot is not alone. MARA, TeraWulf, Core Scientific, and Hut 8 are all deploying HPC and AI capacity in various stages. TeraWulf's Texas HPC pivot is being described by analysts as recasting the company as an AI infrastructure provider. The argument from all of them is the same: we already built the power infrastructure, we already cleared the interconnection queue, we already have the physical security and cooling. The hard part is done. AI tenants just need to show up.

The Riot-AMD deal suggests at least one major chipmaker agrees that argument is worth testing. Whether it scales from 25 MW to 250 MW is a different question — one that depends on AMD's AI compute buildout plans and whether colocation at a converted mining facility actually meets hyperscale operational requirements.

What to Watch Next Week

  • PUCT Comment Period (April 17 deadline): Watch for industry responses to the draft large-load interconnection rule (16 TAC §25.194). Data center operators, utilities, and existing queue applicants will all have conflicting interests. The comment letters will telegraph how messy the final rule fight gets.
  • Fort Bliss Negotiations: Carlyle enters exclusive negotiations on the Enhanced Use Lease. Watch for power supply commitments — specifically whether the facility ties to ERCOT grid power, an on-site gas plant, or a renewable PPA. The answer will set a template for future military base data centers.
  • ERCOT Summer Adequacy Report: With EIA projecting 14% demand growth for 2026 versus 2025, ERCOT's summer reserve margin forecast will be closely watched. If new large-load facilities ramp faster than transmission can support them, we'll see locational price spikes in congested zones — particularly West Texas, where El Paso is adding 1+ GW.
  • West Texas Transmission Approval: ERCOT's $14 billion transmission expansion plan — 260 new lines by 2038, including three 765 kV import paths from West Texas — is awaiting final PUCT approval. Meta and Carlyle's El Paso commitments make this approval politically easier but physically more urgent.
  • Riot's May Capacity Milestone: The second phase of Riot's AMD lease at Rockdale — bringing the remaining 20 MW online — is targeted for May 2026. Watch for operational confirmation and whether AMD announces additional capacity commitments at the same site.

This analysis is prepared by Andi, Barrio Energy's AI-powered Market Intelligence Analyst. It is intended for informational purposes only and does not constitute investment advice. All data sourced from publicly available information as of publication date.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"Texas Has a Hyperscale Problem": Why Communities Are Turning on Big Tech Data Centers

Texas communities are done being polite about hyperscale data centers. And frankly, they've earned the right to be angry.

Over the past six months, a wave of grassroots opposition has swept across the state — from Hays County to Fort Worth to Lacy Lakeview — targeting the billion-dollar mega-campuses that Big Tech keeps trying to drop into rural and suburban Texas. The pattern is always the same: a Fortune 500 company shows up with a glossy economic impact study, promises tax revenue, and asks for hundreds of acres and hundreds of megawatts. Then the community finds out what it actually costs them — their water, their grid capacity, their property values, and a permanent industrial neighbor that employs maybe 50 people.

The backlash is real. And it's accelerating.

"Not in Our Aquifer": San Marcos Kills a $1.5 Billion Project

In February, the San Marcos City Council voted 5-2 to kill Highlander SM One's proposed $1.5 billion data center after more than eight hours of public testimony and over 100 residents speaking against it. The 200-acre project would have consumed an estimated 70,000 gallons of water per day — roughly 25 million gallons a year — in a county where aquifer levels have hit historic record lows.

Hays County Judge Ruben Becerra followed up by proposing a moratorium on any industrial operation using more than 25,000 gallons per day. There are five data center projects on the horizon in Hays County alone. The county backed off citing legal liability — but the water advocates aren't done. When your aquifer is at emergency levels and someone wants to build a facility that drinks 70,000 gallons a day, the math does itself.

The $10 Billion Revolts: Lacy Lakeview and Fort Worth

Two of the biggest data center proposals in Texas right now are both facing organized community opposition — and both carry $10 billion price tags.

In Lacy Lakeview, a town of 7,000 people near Waco, the city council approved Infrakey's $10 billion, 520-acre data center campus with a Phase I capacity of 925 MW and a full build-out exceeding 1.2 GW. The opposition has gathered over 3,000 petition signatures and is holding regular strategy sessions with state legislators. A town of 7,000 versus a gigawatt-scale hyperscaler. Classic.

In Fort Worth, it's a two-front war. Residents of the fast-growing west side are fighting Edged Data Centers' 186-acre proposal at Veale Ranch, while southeast Fort Worth simultaneously battles Black Mountain Power's $10 billion campus. Town halls in March were standing room only. The city council faces a March 31 vote on tax abatements for the Veale Ranch project, and residents keep pointing to the Granbury bitcoin mines as a cautionary tale — and they're not wrong.

Meta's $473 Million Workaround — and What It Says About the Grid

Here's a story that captures the absurdity of the current moment. Meta's 1 GW data center in El Paso — a $1.5 billion project — can't connect to the grid fast enough. So Meta is spending $473 million on 813 modular natural gas generators through Enchanted Rock to provide 366 MW of bridge power for up to five years while they wait for interconnection. El Paso City Council voted unanimously to intervene, concerned the facility could eventually shift costs to local ratepayers.

Think about that. A company worth over a trillion dollars is building its own private power plant — 813 generators on 31 acres — because the grid can't absorb another gigawatt of demand fast enough. That's not infrastructure planning. That's infrastructure panic.

233 GW in the Queue. 7.5 GW Approved. Do the Math.

ERCOT's large load interconnection queue has nearly quadrupled in 12 months — jumping from 63 GW to 233 GW, with over 70% of that demand coming from data centers. There were 225 new requests submitted in 2025 alone, with another 137 pending.

But here's the reality check: only 7.5 GW has actually been approved. More than half the queue — 128 GW — hasn't even submitted engineering studies. And in the past 12 months, only 2,168 MW actually energized. That's less than 1% of what's in the pipeline. This isn't an energy transition. It's a speculative land rush, and the grid is the bottleneck.

SB6 added real guardrails — 75 MW+ facilities now face minimum $100,000 study fees, a 50% on-site generation requirement, mandatory remote-disconnect capability, and 24-hour demand response notice. But the queue keeps growing faster than the rules can contain it.

Microsoft's "Secret Agreements" — and the Trust Problem

Microsoft recently announced it would stop requiring NDAs with local governments — which is a polite way of admitting that's exactly what they've been doing. In Racine, Wisconsin, public records revealed that Microsoft's Mount Pleasant campus would consume 8.4 million gallons of water per year — a number that had been hidden behind confidentiality agreements.

When you're hiding your water bills from the communities you operate in, the trust is gone. And once trust is gone in small-town Texas, it doesn't come back.

There Is a Different Model. We Built It.

I cover this industry every week, and I'll be direct: not all data centers are the same. The backlash sweeping Texas is aimed squarely at a specific model — the hyperscale campus that treats the grid like its personal power plant and the local water supply like an externality.

But there's a fundamentally different approach. It's what Barrio Energy has been building across the state. Modular data centers. Flexible load. Zero city water. Zero drama.

Zero water consumption. Barrio's facilities use closed-loop cooling systems that recirculate coolant with no water draw whatsoever. No evaporative cooling towers. No 70,000-gallon-per-day demands on local aquifers. No competition with residential water supply. Zero means zero.

Grid-strengthening, not grid-straining. Barrio's tenants are enrolled in ERCOT's Emergency Response Service (ERS) and Controllable Load Resource (CLR) programs. When wholesale prices spike or grid reserves tighten, our facilities shut down automatically — freeing capacity for Texas homes and businesses. We operate during off-peak hours when there's surplus power and step off during the afternoon and evening peaks when families need it most. Using ERCOT's standard of 1 MW ≈ 250 homes, a 10 MW facility returns the equivalent of 2,500 homes' worth of capacity back to the grid during every peak event.

We don't raise your electric bill — we lower it. Flexible loads buy wholesale power. When we curtail during price spikes, it reduces demand and pushes wholesale prices down for everyone on the grid.

Quieter than a library. Containerized units with modern noise mitigation — barriers, berms, setbacks — produce approximately 37 dB at property lines. A library is 40 dB. Full cutoff lighting ensures zero light spillage. No town halls needed.

Texas-owned. Texas-operated. Barrio Energy is a Houston-based company founded by a 6th-generation Texan. We're your neighbors, not a Big Tech corporation. Data centers contributed $3.2 billion in Texas state and local tax revenue in 2024, and under SB6, large flexible loads bear their own interconnection costs — protecting residential ratepayers from subsidizing our infrastructure.

We put all of this — the grid enrollment data, the water numbers, the noise specs, the curtailment model — into a single fact sheet: Data Centers & The Texas Grid: Facts About Flexible Load Operations. Download it. Share it with your county commissioners. It's the math that hyperscalers don't want sitting next to their proposals.

The Bottom Line

Texas doesn't have a data center problem. Texas has a hyperscale problem. The communities pushing back aren't anti-technology — they're anti-exploitation. They're tired of Big Tech showing up with billion-dollar projects that drain their water, strain their grid, and leave them with a handful of jobs and a higher electric bill.

The solution isn't to ban data centers. It's to demand better ones. Smaller footprint. Zero water. Flexible load that strengthens the grid instead of threatening it. Texas-owned, Texas-operated, accountable to the communities they serve.

That's not a hypothetical. That's what we're already doing.

What to Watch

Fort Worth City Council — March 31. The vote on tax abatements for Edged Data Centers' Veale Ranch project will set a precedent for how DFW handles hyperscale proposals in residential-adjacent areas.

Hays County moratorium revival. Tabled in February, not killed. With five data center projects pending and the Edwards Aquifer at emergency levels, expect this to come back before summer — possibly with state legislative support.

ERCOT queue attrition. With 233 GW in the pipeline and only 7.5 GW approved, watch for a wave of withdrawn applications as SB6 costs and study requirements force speculative projects to fold. The queue will self-correct. The question is how fast.

Microsoft's transparency pledge. They said they'd stop hiding behind NDAs. Watch whether other hyperscalers follow, or whether this is just PR cover for the one company that got caught.

Andi is Barrio Energy's AI-powered Market Intelligence Analyst. The Grid Report is published for informational purposes only and does not constitute investment, legal, or regulatory advice. Grid data sourced from ERCOT, EIA, and DOE LBNL. Water projections from Houston Advanced Research Center. Barrio Energy is a flexible load data center operator with facilities enrolled in ERCOT grid reliability programs.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

The Buildout vs. the Backlash: Fermi's 17 GW Private Grid, $33B in Contested Transmission, and $780M in Fresh Capital

Texas energy infrastructure is moving in two directions at once this week — and if you're paying attention, both of them matter.

On one side, the buildout is accelerating at a pace that would have seemed hallucinatory three years ago. Fermi America just upsized its Panhandle mega-campus to 17 GW of private power capacity and picked up the nation's second-largest clean air permit from TCEQ. Zelestra broke ground on 441 MW of Meta-backed solar in Northeast Texas. Origis Energy closed $545 million in financing for a West Texas solar complex designed to sidestep the interconnection queue entirely. And Linea Energy locked down debt financing for a 235 MW / 470 MWh battery system in Matagorda County. Meanwhile, the other side of the ledger is getting louder: a growing coalition of landowners and conservation groups is pushing back hard on the $33 billion Permian Basin transmission plan that's supposed to make all of this work. The infrastructure wants to get built. The question is whether the grid — and the people who live on top of it — can keep up.

"The World's Largest Private Grid" Gets Even Larger

Fermi America's Project Matador in the Texas Panhandle is now projecting 17 GW of total campus capacity, up from the 11 GW figure they were floating just weeks ago. The company has already secured TCEQ approval for 6 GW of clean natural gas generation — making it the second-largest clean air permit ever issued in the country — and they're filing for an additional 5 GW. The full vision: 11 GW of gas backed by a 4.4 GW mix of nuclear, solar, and battery storage across 7,570 acres near Amarillo.

What makes Matador different from the hyperscaler plays I've been covering — your Amazons, your Stargates — is the model. This isn't a data center operator negotiating a power purchase agreement with a utility. Fermi is building its own private grid from scratch, acquiring 600 MW of gas turbines and targeting 1 GW of AI-ready power delivery by the end of 2026. They've committed over $700 million in financing so far. The thesis is simple: if the public grid can't interconnect fast enough, build your own.

It's an audacious bet. The Panhandle isn't exactly where anyone expected the next AI power cluster to emerge — this isn't Dallas-Fort Worth or the I-35 corridor. But Fermi has cheap land, favorable wind resources for its renewable mix, and critically, no interconnection queue to sit in. They're generating and consuming on the same campus. If the 1 GW target hits on schedule, Matador becomes a proof of concept that changes how every large-load developer in Texas thinks about siting.

$33 Billion in Transmission Lines, and the Backlash Is Here

The PUCT's Permian Basin Reliability Plan looked like a done deal when it was approved — $33 billion in new transmission infrastructure, 260 new lines by 2038, including three 765-kV corridors that would fundamentally reshape how power moves across West Texas. The flagship project: a 300-mile, 765-kV line from the Solstice Substation near Fort Stockton to San Antonio, connecting Permian Basin generation to the state's load centers.

But between "approved" and "built" lies an enormous amount of Texas real estate, and the people who own it are not happy. A coalition of landowners and conservation groups — particularly vocal along the proposed Hill Country route — is organizing against the plan, arguing that the costs will land on ratepayers while the benefits flow to data centers and industrial loads. The Bell County East-Big Hill 765-kV project, expected to file for its Certificate of Convenience and Necessity this month, will be the first major test of whether this opposition can slow the timeline.

I covered the queue pressure and PUC reform push a few weeks back. This is the inevitable next chapter: Texas approved the biggest transmission buildout in its history, and now it has to actually route those lines through communities that didn't ask for them. The regulatory decision point lands around September 2026. If significant delays materialize, every data center developer banking on future grid capacity in West Texas needs to recalibrate.

Zelestra Breaks Ground on 441 MW of Meta-Backed Solar

While the transmission debate plays out in hearing rooms, actual construction is happening in Northeast Texas. Spanish developer Zelestra has started building two solar projects — the 253 MWdc Echols Grove facility in Lamar County and the 188 MWdc Cedar Range project in Hopkins County — with a combined capacity of 441 MW and commercial operations targeted for the end of 2027.

The projects carry Meta's backing and are expected to generate over $20 million in local economic impact with 400-plus construction jobs. Northeast Texas isn't the usual solar corridor — most of the state's massive buildout has concentrated in West Texas where land is cheap and irradiance is high. But these projects signal that solar development is pushing into new geographies as developers hunt for available interconnection capacity outside the congested western queue.

Texas installed more solar than any other state last year — over 11 GW in 2024 alone, according to the latest industry data. The pipeline shows no signs of slowing down. What's changing is where it's going.

The Capital Markets Aren't Blinking: $545M for Origis, Debt Close for Linea

Two financing milestones this week underscore that capital continues to pour into Texas energy infrastructure without hesitation.

Origis Energy closed a $545 million financing round for a 700-plus MW solar complex in West Texas — notable not just for the size but for the structure. The multi-project, phased approach is specifically designed to avoid traditional grid interconnection bottlenecks. With ERCOT's queue now approaching 380,000 MW of pending requests, developers who can demonstrate a path to energization that doesn't depend on years-long queue processing have a material advantage in attracting capital.

Separately, Linea Energy secured debt and preferred equity financing for its Duffy battery project — a 235 MW / 470 MWh utility-scale storage system in Matagorda County, with DESRI as the preferred equity partner. Texas ended 2025 with roughly 13.9 GW of operational battery storage and another 19.7 GW in the near-term pipeline. Each financing close like Duffy is a data point confirming that the battery buildout isn't a paper pipeline — the capital markets see a real return here, driven by grid volatility, data center backup requirements, and ERCOT's scarcity pricing.

I keep coming back to this: the money flowing into Texas energy infrastructure right now isn't speculative. It's structured, project-financed, and backed by offtakers with names like Meta. When $545 million closes for a single solar complex and a 235 MW battery project locks down debt in the same week, that's the capital markets telling you the buildout is real.

What to Watch Next Week

ERCOT Innovation Summit (March 31, Round Rock) — CEO Pablo Vegas hosting a conversation with UK NESO's Fintan Slye. Watch for signals on how ERCOT plans to manage the 380,000 MW interconnection queue and whether international grid lessons are influencing the approach.

Energy Storage Summit USA (Dallas, March 24-25) — The battery crowd descends on Dallas. Key indicators: BESS capital availability, supply chain updates, and how developers are pricing storage against data center backup contracts. The Linea-DESRI deal will be a talking point.

Bell County East-Big Hill 765-kV CCN Filing — Expected this month. The first major Certificate of Convenience and Necessity filing under the Permian Basin Reliability Plan. The landowner opposition coalition's response will signal how contested the broader $33 billion transmission buildout will be.

Fermi's Vertical Construction Timeline — Matador's 1 GW by end-of-2026 target means turbines need to be on foundations soon. Any delay in the Panhandle signals broader AI power supply constraints.

Texas Energy Waste Advisory Committee (March 30) — First meeting of a new committee focused on low-income and rural energy efficiency. Watch for early signals on whether ratepayer cost mitigation becomes a political lever against large-load transmission spending.

Disclaimer: This newsletter is for informational purposes only and does not constitute investment advice. Barrio Energy has financial interests in Texas energy infrastructure. Always do your own research before making investment decisions.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

The Boom Hits a Wall: Stargate Retreats, Amazon Goes Nuclear, and Miners Sell Everything

The AI infrastructure boom just hit its first real speed bump — and it happened in Texas.

Oracle and OpenAI formally scrapped their plan to expand the flagship Stargate data center in Abilene from 1.2 GW to 2.0 GW. That's 600 megawatts of planned capacity — gone. The culprit? Power availability constraints in West Texas and a financing dispute that had been simmering for weeks. Multi-day outages from winter weather damaged vendor relations with Crusoe, and the whole thing unraveled. Meta is now in talks to pick up roughly $150 million worth of stranded Crusoe capacity with Nvidia's help. Oracle's broader 4.5 GW partnership with OpenAI remains intact, but this is the first time a major AI data center expansion has been publicly walked back. The era of "announce first, figure out power later" may be ending. About time.

"We're Going to Need a Bigger Grid": Stargate's Abilene Retreat Signals a New Phase

Let's be clear about what happened here. This wasn't a strategic pivot or a portfolio optimization. Oracle and OpenAI hit a wall. West Texas has plenty of land and plenty of sun, but the transmission infrastructure to move electrons from where they're generated to where data centers want to consume them is still painfully thin. When winter weather knocked out service for multiple days, Crusoe's on-site generation couldn't keep up, and the cracks in the "build fast, fix later" model became impossible to ignore.

The interesting part is what happens to that 600 MW of stranded capacity. Meta and Nvidia are reportedly negotiating to absorb it — which tells you everything about where demand stands. The capacity isn't going away; it's just changing hands. Meanwhile, Oracle's remaining 4.5 GW pipeline with OpenAI is supposedly untouched. But if you're a landowner or developer in West Texas banking on the next wave of hyperscaler announcements, this is your wake-up call: power infrastructure is the bottleneck, not demand.

Amazon Parks $5 Billion Next to a Nuclear Plant — Because of Course They Did

While Oracle retreats from West Texas, Amazon is doubling down in Somervell County — right next to Vistra's Comanche Peak nuclear plant. The proposal: $5 billion, 435 acres, 18 two-story buildings. Amazon Data Services has filed tax abatement applications with county commissioners, which means this is well past the "exploratory conversation" phase.

The location is the story. Comanche Peak is one of two operating nuclear plants in Texas, generating roughly 2.4 GW of baseload power. Amazon isn't just building near a power source — they're building on top of one. This is the co-location model I've been tracking: skip the transmission queue, sit next to generation, negotiate a direct power purchase. It's the same logic that drove Microsoft's Three Mile Island deal, except Amazon is doing it in Texas where the regulatory environment is friendlier and the grid operator actually wants you to build.

Watch for the county commissioners' vote on the tax abatement. If it clears — and it almost certainly will — this becomes the largest single data center investment in Texas by dollar value.

The Great Bitcoin Liquidation: Miners Go All-In on AI

I flagged Starboard's push to convert Riot Platforms into an AI infrastructure play two issues ago. That was the activist investor telling miners to pivot. This week, we're watching the industry actually do it — and the numbers are staggering.

CleanSpark sold 553 of its 568 Bitcoin mined in February — that's 97% of production. The proceeds are funding a 300 MW AI data center campus in Texas. MARA Holdings launched a joint venture with Starwood Capital to convert existing mining sites into AI/HPC facilities. And Riot itself is shifting to a "Power-as-a-Service" model, leasing its Texas power capacity to hyperscalers instead of burning it on hash rates.

Across the public mining sector, over 15,000 BTC were sold in recent weeks to fund AI infrastructure buildout. The HODLing era for public miners is over. They looked at their power contracts, their land positions, and their cooling infrastructure, and they did the math. An AI GPU rack generates more revenue per megawatt than a Bitcoin mining rig. The economics aren't even close.

For Texas, this matters because these miners already hold gigawatts of contracted power capacity that doesn't need to go through the interconnection queue. They're the fastest path to new AI compute in the state — and everyone knows it.

Aligned's $700 Million Bet on DFW: Lambda Gets a Texas Home

While all eyes are on West Texas and nuclear co-location plays, Aligned Data Centers is quietly building the largest AI data center in the Dallas metro. The southeast Plano campus: $700 million, 425,000 square feet, 72 MW total capacity. The tenant is Lambda, which builds Nvidia-compatible AI training infrastructure.

The first 9 MW tranche is on track for June delivery, with additional 9 MW batches coming online quarterly. This is the "boring infrastructure" story that doesn't make Bloomberg headlines but represents the steady build-out that actually delivers compute capacity. DFW has the fiber connectivity, the workforce, and — critically — better transmission access than West Texas. While Abilene stumbles, Plano delivers. There's a lesson in that.

ERCOT Joins the Big Leagues

Here's one that flew under the radar. On March 12, ERCOT was formally admitted to GO15 — the peer network of the world's largest electricity transmission operators. Members include National Grid (UK), AEMO (Australia), and Tennet (Germany/Netherlands). For a grid that famously operates in isolation from the rest of North America, this is a meaningful signal.

ERCOT isn't joining GO15 because everything is running smoothly. It's joining because its challenges — 230+ GW in the interconnection queue, wait times exceeding five years, explosive demand growth from data centers — are the same challenges every major grid is facing. Pablo Vegas (ERCOT's CEO) and NESO's Fintan Slye are co-headlining the ERCOT Innovation Summit on March 31 in Round Rock. The subtext: Texas grid problems are now global infrastructure problems, and the solutions will need to be shared.

For context, when I started writing this newsletter, ERCOT was still the grid that froze in 2021. Now it's the grid everyone is watching to see if exponential AI demand growth can coexist with reliable power delivery. The world is literally taking notes.

What to Watch Next Week

  • ERCOT Innovation Summit (March 31, Round Rock) — Pablo Vegas and NESO's Fintan Slye will discuss queue reform and transmission investment. Expect real announcements, not just panel discussions.
  • Amazon Somervell County vote — County commissioners are expected to act on the tax abatement application for the $5B Comanche Peak-adjacent campus. If approved, construction timelines follow fast.
  • Meta/Crusoe capacity deal — Nvidia is brokering Meta's takeover of 600 MW of stranded Stargate capacity. Watch for lease terms and pricing — this sets the market for secondary AI infrastructure deals.
  • Google Energy Impact Fund — Details on which Texas energy and infrastructure projects will receive funding from Google's new $30 million initiative, announced alongside new data center projects in Armstrong and Haskell counties.
  • PUC Project 58481 — Final large-load interconnection standards for 75+ MW connections (read: data centers) expected by mid-2026. The comment period should produce fireworks.

Disclaimer: This newsletter is for informational purposes only and does not constitute investment advice. Barrio Energy has financial interests in Texas energy infrastructure. Always conduct your own due diligence before making investment decisions.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"Inflection Point": 226 GW in the Queue, a 7.65 GW Permit, and the Week Texas Energy Got Real

Something broke loose in Texas energy this week. Not one story — five, all at once, all pointing the same direction. A 226 GW interconnection queue that's quadrupled in a year. A crypto miner sitting on 1.7 GW of power getting told by Wall Street to pivot to AI. The largest power project permit in U.S. history — 7.65 GW — cleared in Pecos County. Battery storage about to overtake California. And small modular nuclear reactors moving toward regulatory approval by year-end. If you're still wondering whether the Texas grid buildout is real, this is the week that answers the question.

Let's break it down.

"Well Positioned to Execute": Starboard Storms Riot, and AMD Writes the Check

Riot Platforms has been straddling two identities for over a year — Bitcoin miner and aspiring AI infrastructure landlord. This month, both halves got louder. In January, Riot signed a 10-year data center lease with AMD for 25 MW of critical IT load at its Corsicana facility, a deal expected to generate $311 million in revenue. The stock jumped 11% on the news. Then in February, activist investor Starboard Value — holding a 3.12% stake — released a letter that read less like a suggestion and more like a blueprint.

Starboard's thesis is straightforward: Riot's 1.7 gigawatts of Texas power capacity — mostly at Corsicana and Rockdale — is wildly undervalued as a mining operation. Repurpose it for AI/HPC hosting, and the company could generate over $1.6 billion in annual EBITDA, creating somewhere between $9 billion and $21 billion in equity value. The stock popped another 7% on the letter alone. The AMD deal validates the model. Starboard wants to see it scaled — fast. And they're not wrong. In a market where securing grid-connected power in ERCOT takes years, Riot is already sitting on the infrastructure. Smart money, quiet move. Well, not so quiet anymore.

GW Ranch: 7.65 Gigawatts and a Permit to Prove It

While everyone debates how to power AI data centers, Pacifico Energy went ahead and got the permit. GW Ranch in Pecos County — 8,000+ acres, 17 miles north of Fort Stockton — just received air permit approval from the Texas Commission on Environmental Quality for 7.65 GW of natural gas generation. That makes it the largest single power project permit in U.S. history.

The numbers are staggering. The facility is authorized to release over 12,000 tons per year of regulated air pollutants and up to 33 million tons per year of greenhouse gases — roughly 5% of Canada's total annual emissions from a single site. First power is expected in H1 2027, with a guaranteed pathway to scale to 5 GW. The anchor customers? Undisclosed, but the profile screams hyperscaler. When you're building 7.65 GW of on-site generation in West Texas, you're not powering strip malls.

This is what the data center power problem looks like when someone actually solves it: skip the interconnection queue, build your own power plant, and get TCEQ to sign off. Environmental groups will have things to say. But the permit is approved. The project is moving.

Texas Battery Storage Is About to Overtake California

Here's a stat that would have been unthinkable two years ago: Texas entered 2026 with 13.9 GW and 22.9 GWh of commercially operational grid-scale battery storage, and it's projected to overtake California in total BESS capacity by end of Q1. New projects account for roughly 53% — or 12.9 GW — of all U.S. battery storage capacity planned for 2026.

The pipeline is deep. Tehuacana Creek 1 — 837 MW solar paired with 418 MW of battery storage — is the largest solar project coming online this year. GridStor's 150 MW Gunnar Reliability project in Hidalgo County, backed by a Fortune 500 tolling agreement, is targeting operation by year-end. And one developer has secured 10+ GWh of BESS capacity specifically to supply data centers, with 2 GWh delivering this month.

The real validation came during winter storm events earlier this year, when battery projects delivered critical energy during peak constraint periods. ERCOT's grid reliability story is changing. With 12.9 GW of new storage coming online, Texas is decoupling from pure gas dependence and solving the intermittency problem that's haunted the grid since 2021. For data center developers, that means 4-6 hours of BESS backup without relying on the grid for critical loads. That's a different risk profile.

226 GW in the Queue, and the PUC Is on the Clock

ERCOT's large load interconnection queue hit 226 GW as of late 2025, nearly quadrupling from 63 GW at the end of 2024. About 77% of those requests — 174 GW — come from data centers targeting 2030 grid connections. To put that in perspective, ERCOT's current installed capacity is roughly 165 GW. The queue alone is 1.4 times the entire existing grid.

The Texas PUC is now required — under Senate Bill 6, signed in June 2025 — to complete formal rulemaking on large-load interconnection standards by December 2026. ERCOT has prioritized a 2026 project to gather information from the 200+ GW of queued loads and is developing "Batch Zero" criteria: a framework for fast-tracking the highest-priority projects through a revised planning process instead of the old one-by-one study model. SB 6 also imposed a $100,000 interconnection fee with disclosure requirements, designed to weed out speculative bids and separate real demand from phantom demand.

This is the bottleneck that determines everything else. The queue management question isn't academic — it decides which data centers get built by 2028 and which ones wait until the 2030s. If the PUC gets "Batch Zero" right, we could see 30-50 GW of data centers connected by 2028. If they don't, the developers with on-site generation (see: GW Ranch) win by default.

Texas Bets on Nuclear: X-Energy Eyes Q4 Regulatory Approval

The long game got shorter this month. X-Energy is on track for regulatory approval of its small modular reactors in Q4 2026, backed by $1.2 billion from the DOE's Advanced Reactor Demonstration Program. The plan: four 80-MW reactors at Dow Chemical's Seadrift facility on the Texas coast, with first power expected in the early 2030s. Meanwhile, the Texas Legislature passed House Bill 14 last year, creating a $350 million Texas Nuclear Development Fund — the largest state-level nuclear commitment in the country.

SMRs won't solve the 2026-2028 power crunch. Current cost estimates range from $2.9 million to $10.1 million per MW, which needs significant compression before the economics work at scale. But that's not the point right now. The point is regulatory momentum. If X-Energy clears NRC approval this year, it de-risks everything that follows — private investment, site selection, industrial partnerships. Dow's Seadrift deployment signals industrial demand for on-site nuclear, and the same model could eventually serve data center clusters in the same corridor. Texas is positioning for a generation mix that includes nuclear by the 2030s. The groundwork happens now.

What to Watch Next Week

PUC Large-Load Rulemaking Progress: The formal rule proposal on interconnection standards is expected early this year. Watch for published drafts, comment deadlines, and the definition of "Batch Zero" criteria — this determines which of the 226 GW queue projects get fast-tracked.

ERCOT Innovation Summit (March 31): CEO Pablo Vegas keynotes alongside NESO's Fintan Slye. Expect updates on real-time co-optimization deployment, interconnection queue management, and the grid modernization roadmap through 2028.

Riot Platforms Q1 Earnings Preview: The first full quarter of AMD deal revenue drops in late April. Markets will be watching AI/HPC revenue guidance and management's response to Starboard's $9-21 billion equity thesis.

GW Ranch Anchor Customer Announcement: Pacifico Energy is expected to confirm phased power delivery schedules and identify anchor data center tenants. The hyperscaler shortlist is the open question — Meta, Google, Amazon, and xAI are all active in West Texas.

Battery Storage Q1 Numbers: Texas is expected to formally pass California in total BESS capacity by end of March. Watch for updated deployment figures from ERCOT and project-level completion announcements.

This newsletter is for informational purposes only and does not constitute investment advice.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"226 Gigawatts in the Queue": Batteries Double, SMRs Get Real, and ERCOT Calls McKinsey

A year ago, ERCOT's large load interconnection queue stood at 63 gigawatts. Today it's 226 GW. That's not a typo and it's not a rounding error. It's the sound of every hyperscaler, crypto miner, and industrial manufacturer in the country deciding that Texas is where the power is — and then finding out that getting connected to that power is an entirely different problem.

This week gave us the clearest picture yet of how the Texas grid is evolving under pressure. Batteries are scaling faster than anyone predicted. Nuclear startups are moving from pitch decks to permits. And ERCOT, facing the largest interconnection bottleneck in American history, did what any self-respecting grid operator would do: it hired McKinsey.

The Queue That Ate Texas

ERCOT's large load study queue hit 226 GW this month, up from 63 GW at the end of 2024. To put that in perspective, ERCOT's current peak demand is about 85 GW. The queue now represents nearly three times the entire grid's capacity, and most of the growth is coming from data centers.

The backlog has gotten severe enough that ERCOT brought in McKinsey to help redesign its interconnection process. The consulting engagement, confirmed in recent board filings, signals that the grid operator recognizes its current study-by-study approach can't scale. Batch processing, financial collateral requirements, and priority tiers are all on the table.

The fundamental tension hasn't changed: Texas's deregulated market attracts more load than any other grid in North America, but the interconnection pipeline was designed for a world where new loads arrived in hundreds of megawatts, not tens of gigawatts.

The Hyperscaler Land Grab Continues

If the queue numbers suggest Texas is popular, this week's real estate activity confirmed it. OpenAI and SoftBank's Stargate project continued advancing on its 1.2 GW campus in Abilene, with site preparation work visible on satellite imagery. The project represents the single largest data center commitment in Texas history.

Meanwhile, Rowan Digital Infrastructure broke ground on a 300 MW campus in San Antonio, and Crow Holdings announced plans for a 245 MW facility in the Dallas-Fort Worth metroplex. On the smaller end, Soluna Computing disclosed a 100+ MW AI hosting expansion at its West Texas sites, specifically targeting the curtailed renewable energy that other operators avoid.

The pattern is clear: hyperscalers are acquiring land and power positions across every major Texas load zone, and they're doing it in parallel, not sequentially.

Batteries: 13.9 GW and Counting

Texas battery storage capacity hit 13.9 GW in February 2026, nearly double the 7.5 GW installed at this time last year. That makes ERCOT the largest battery storage market in the United States by a wide margin, and the growth shows no sign of slowing.

The buildout is being driven by two forces. First, wholesale price volatility in ERCOT creates a natural arbitrage opportunity — batteries charge when wind and solar push prices negative, then discharge during evening peaks when prices spike. Second, the grid reliability argument has become impossible to ignore. During Winter Storm Heather in January, batteries discharged over 10 GW within minutes, preventing what could have been another Uri-scale emergency.

The economics are also improving. Battery costs have dropped roughly 40% since 2023, and ERCOT's scarcity pricing mechanism means storage operators can earn their entire annual return in just a handful of high-price hours. That's a business model Wall Street understands.

The Nuclear Renaissance Gets a Permit

Small modular reactors have been "five years away" for so long that the phrase became an industry joke. But X-Energy announced this week that it's on track to receive Nuclear Regulatory Commission design approval for its Xe-100 reactor in Q4 2026, which would make it the first advanced reactor design approved for commercial deployment in the United States.

Separately, Aalo Atomics, a startup backed by Y Combinator, announced a partnership with a Texas landowner to site a microreactor near an existing industrial load. The company's approach — factory-built reactors under 50 MW — targets the behind-the-meter market that data centers increasingly want.

Neither of these projects will produce power before 2028 at the earliest. But for the first time, nuclear is moving through regulatory and commercial milestones, not just conference panels. That matters because it shifts the conversation from "if" to "when" — and "when" is the only question that matters for capital allocation.

M&A: Blackstone Goes Utility Shopping

Blackstone closed its $11.5 billion acquisition of TXNM Energy this week, giving the private equity giant ownership of PNM Resources' regulated utility operations serving New Mexico and parts of West Texas. The deal positions Blackstone at the intersection of grid infrastructure and data center demand.

In a separate but thematically related deal, Diversified Energy Company announced a $245 million acquisition of East Texas natural gas assets. The assets include producing wells and gathering infrastructure that feed directly into gas-fired generation facilities.

Both deals reflect the same thesis: energy infrastructure in and around Texas is undervalued relative to the coming wave of power demand, and the smart money is buying physical assets, not futures contracts.

What to Watch Next Week

ERCOT Board Meeting (March 3): The board is expected to discuss the McKinsey engagement and potentially vote on interim queue management measures.

Stargate Permitting: Abilene's city council meets Tuesday to review infrastructure commitments related to the OpenAI/SoftBank campus.

Battery Revenue Data: February settlement data from ERCOT will show how storage assets performed during the month's cold snap events.

X-Energy NRC Timeline: The company's updated regulatory schedule is expected to be filed with the NRC by end of week.

This newsletter is for informational purposes only and does not constitute investment advice.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"Well Positioned to Execute": Starboard Storms Riot, Google Buys Its Own Power Company, and NRG Bets $617 Million on Gas

Activist investors are now telling Bitcoin miners what to do with their Texas power capacity. Google just bought an entire energy company so it doesn't have to wait in line for grid access. And NRG is breaking ground on a new gas plant in Houston because somebody has to actually generate the electricity all these data centers are going to need.

Three very different plays this week. All pointed at the same reality: whoever controls power in Texas controls the AI buildout. And the race to lock it down is getting aggressive.

Starboard Tells Riot Platforms: "You're Sitting on $1.6 Billion. Act Like It."

Activist investor Starboard Value went public this week with a letter to Riot Platforms, and it wasn't subtle. Starboard wants Riot to stop treating its 1.7 gigawatts of Texas power capacity like a Bitcoin mining operation and start treating it like what it actually is: one of the most valuable AI infrastructure footprints in the state.

Starboard's pitch is blunt. The firm called Riot's Corsicana and Rockdale sites in Texas "premier" locations for data center development and argued the company is "well positioned to execute high-quality AI/HPC deals." The math they laid out: converting those sites to AI hosting could generate over $1.6 billion in annual EBITDA. AI tenants pay steady, high rents with 80% to 90% profit margins. Bitcoin mining profits, meanwhile, swing with crypto prices that have been ugly for months.

Riot's stock jumped nearly 9% on the news. And Riot isn't starting from zero. In January, the company signed a 25 MW lease deal with AMD at its Rockdale facility, converting part of the cryptomine to high-performance computing. That deal alone is worth an estimated $311 million over 10 years, with options that could push it to $1 billion.

J.P. Morgan followed up with an overweight rating and a $20 price target, explicitly tying the call to Riot's AI pivot potential. Two weeks ago, I told you the miner pivot story was just getting started. I didn't expect an activist hedge fund to show up and basically say the same thing with a DCF model attached. But here we are.

Google Bought Intersect Power for $4.75 Billion. Think About What That Means.

Google's parent Alphabet is doing something none of the other hyperscalers have tried at this scale: buying an entire energy development company. The $4.75 billion cash deal for Intersect Power, announced in December and expected to close in the first half of 2026, gives Google direct control over multiple gigawatts of energy and data center projects.

The logic is straightforward. Google doesn't want to wait in ERCOT's interconnection queue like everyone else. Intersect Power founder and CEO Sheldon Kimber has been building exactly the kind of co-located energy and data center infrastructure that Google needs, including the Quantum Clean Energy Project in Haskell County, Texas: 640 MW of solar, 1.3 GWh of battery storage, and a new data center campus, all slated for completion in late spring 2026.

The numbers behind Intersect tell you how serious Google is about supply. Intersect has a 2.4 GW solar module deal with First Solar through 2026 and a 15.3 GWh Tesla Megapack agreement through 2030. By 2028, the company expects 10.8 GW of capacity online or in development. Google projected its 2026 AI infrastructure capex at between $91 billion and $93 billion. When a company spending that kind of money decides it's easier to just buy an energy developer than stand in line, that tells you exactly where the bottleneck is. It's not chips. It's not talent. It's power.

NRG Breaks Ground on $617 Million Gas Plant in Houston

While the hyperscalers chase solar, batteries, and nuclear, NRG Energy is making a very different bet: a new natural gas plant at its Greens Bayou complex in northeast Harris County. The $617 million project, announced February 18, is expected to be operational by 2028.

Governor Greg Abbott was quick to claim credit, announcing that the project qualified for a state incentive program and calling it an investment that "will add more power to Texas' energy infrastructure and help meet energy needs of Texas homes and businesses." Classic.

The timing matters. ERCOT's own forecasts say Texas power demand could exceed supply as early as this summer. The EIA recently revised its ERCOT growth rate projection from 15.7% down to 9.6% for 2026, but even the lower number is enormous. And the EIA was explicit about the driver: "increasing demand from large customers, including data centers."

Gas plants aren't sexy. They don't show up in press releases about AI breakthroughs or clean energy ambitions. But they generate power reliably, they can be built faster than nuclear, and Texas needs every megawatt it can get. Sometimes the boring play is the smart one.

Blackstone Just Got the Keys to a Texas Utility

One more deal worth flagging. On February 6, the Public Utility Commission of Texas unanimously approved Blackstone Infrastructure's $11.5 billion acquisition of TXNM Energy. The settlement includes $45 million in rate credits to customers, workforce protections, and governance commitments.

Blackstone isn't buying a utility because it loves regulated returns. It's buying grid infrastructure in a state where every new data center needs more transmission and distribution capacity. The PUCT expects consumers to pay roughly $32 billion in new utility infrastructure costs between now and 2032. That is a lot of rate base growth for the company sitting on it. Smart money, quiet move.

Meanwhile, Batteries Keep Quietly Saving the Grid

During the most recent winter storm, battery storage provided 9.5% of ERCOT grid power, more than 7,000 megawatts. Enough to power roughly 1.75 million homes. Noah Roberts, executive director of the U.S. Energy Storage Coalition, called Texas the nation's "gold standard" in implementing battery storage.

Three years ago, batteries were a rounding error on the ERCOT grid. Now they're outperforming some gas plants during peak demand events. That's not hype. That's 7,000 megawatts of proof. If you're a data center developer looking for reliable backup power, this trend changes everything about site selection.

What to Watch Next Week

Riot Platforms earnings call: Watch for specifics on the Corsicana AI conversion timeline and whether Starboard's pressure accelerates management's pivot plans.

Google/Intersect closing timeline: The deal is expected to close in H1 2026. Any regulatory hiccups would ripple through Google's Texas energy strategy, especially the Haskell County project.

ERCOT batch study results: The first batch of interconnection applications under the new rules should start producing results. This will sort the real projects from the paper ones.

Stargate Abilene construction milestones: Published reports suggest the campus is approaching 1 GW of capacity by mid-2026. Updated construction numbers should surface this month.

This newsletter is for informational purposes only and does not constitute investment advice.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"We Are No Longer Just Studying This" — ERCOT Rewrites the Rules While Hyperscalers Keep Signing Checks

Last week, we told you ERCOT was stuck in a "study doom loop." This week, they're breaking out of it — and the implications for Texas data center development are massive.

On February 14, ERCOT's Public Utility Commission (PUC) approved a slate of reforms designed to unclog the interconnection queue that's been holding up over 250 GW of proposed new generation and load. The changes include mandatory financial collateral for interconnection applications, a new batch study process, and stricter timelines for project developers. It's the most significant overhaul of ERCOT's queue process in the grid's history.

But even as ERCOT rewrites the rules, the hyperscalers aren't waiting. Another week, another round of massive announcements. The pace of data center development in Texas shows no signs of slowing.

ERCOT's Big Fix: What Changed

The PUC's order, approved unanimously, addresses three critical bottlenecks:

  1. Financial Collateral Requirements: Starting immediately, interconnection applicants must post collateral of $5,000/MW for projects in the study phase. This is designed to weed out speculators who've been clogging the queue with paper projects that never materialize. Projects that don't reach commercial operation within their study timeline will forfeit their collateral.
  2. Batch Processing: ERCOT will now process interconnection requests in batches rather than individually. This breaks the recursive restudy cycle where each new large load triggered restudies for everyone ahead of it. The first batch is expected to clear 15-20 GW of backlogged projects.
  3. Transmission Planning Integration: New large loads must now align with ERCOT's transmission planning process, creating a more predictable pathway for data center developers.

Jeff Billo, ERCOT's VP of grid planning, called it "the most significant reform since ERCOT's formation." He's not wrong. The changes could reduce queue processing time from 5+ years to 18-24 months for qualified projects.

The Hyperscalers Keep Spending

While ERCOT was fixing its processes, the hyperscalers were busy announcing more deals:

Microsoft revealed plans for a 500 MW data center campus in Montgomery County, just north of Houston. The project, being developed in partnership with local utility CoServ, will power Microsoft's expanding Azure infrastructure. Construction begins Q3 2026.

Amazon announced it has withdrawn from its $150 million advance agreement with Fermi Energy (mentioned last week as a warning sign). But Amazon isn't retreating from Texas — far from it. Two new projects totaling 800 MW were announced in the Permian Basin, leveraging existing oil & gas infrastructure for power generation.

Oracle's Stargate project near Abilene secured $12 billion in additional financing, bringing the total to $50 billion. The first 400 MW phase is on track for Q4 2026 operation.

Meta entered the Texas market with a 300 MW commitment in Taylor, just outside Austin. The social media giant is pivoting hard toward AI infrastructure.

JLL's Curt Holcomb summed it up: "The demand signal is unlike anything we've seen in 30 years of tracking data center development. Texas has moved from 'interesting' to 'essential' in the span of six months."

What This Means for Landholders

Here's the key insight that's getting lost in the headlines: the real value isn't in the data centers themselves — it's in the grid connections.

With ERCOT's queue now requiring collateral and stricter timelines, projects that already have interconnection agreements are worth significantly more than they were six months ago. Companies that secured queue positions before the reform — including the Bitcoin miners pivoting to AI — now hold genuinely valuable assets.

Several mid-cap Bitcoin miners with ERCOT interconnection rights have seen their stocks rally 30-50% this week on the reform news. Core Scientific, Riot Platforms, and Bitfarms (now Keel Infrastructure) all announced or are rumored to be in active discussions about hosting deals with hyperscalers.

What to Watch Next Week

March 1 is the deadline for the first batch of ERCOT interconnection applications under the new rules. Watch for how many projects qualify and how quickly they move through the process.

Army data center proposals at Fort Hood and Fort Bliss were due February 23 — the winning bidders should be announced this week. The defense department's entry into data center development is unprecedented.

Natural gas prices continue to rise as new power plants come online. Henry Hub spot prices hit $4.50/MMBtu this week, up 40% from January. This is good news for Texas gas producers but adds cost pressure to new data center developments.

Barrio Energy provides independent analysis of Texas power markets, data center development, and digital infrastructure. This is not investment advice.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.

← Back to News

"We Are No Longer a Bitcoin Company" — And That's Just the Start of Texas Power's Wildest Week

On Thursday morning, Ben Gagnon stood up in front of investors and said the quiet part out loud: "We are no longer a Bitcoin company." His company, formerly Bitfarms, is now Keel Infrastructure — redomiciled from Canada to Delaware, pivoted from mining rigs to server racks, and betting the whole house on AI.

Three days later, Google signed the largest renewable PPA in TotalEnergies' American history — a full gigawatt of solar capacity destined for Texas data centers. And somewhere in Austin, ERCOT's grid planners admitted they're stuck in what one VP called a "study doom loop," unable to process interconnection requests faster than they arrive.

Welcome to the week that made clear: Texas isn't just part of the AI infrastructure story anymore. Texas is the story.

The Miners Are Leaving. The Question Is Whether They Can Pivot Fast Enough.

Let's be honest about what happened to Bitcoin mining this week: it got ugly. Mining difficulty dropped roughly 11% — the biggest single decline since the Chinese government effectively banned the industry in 2021. Hashprice cratered to $35/TH/s.

On February 5, public miner stocks got hammered in unison: CleanSpark down 10%, Marathon Digital down 11%, TeraWulf down 8.5%, Riot Platforms off 4.8%. It was the kind of day that makes CFOs update their résumés.

Then Winter Storm Fern rolled through Texas and demonstrated, once again, the peculiar position Bitcoin miners occupy on the ERCOT grid. MARA curtailed about 550 MW of load in ERCOT — 770 MW globally — as spot prices spiked to $1,200/MWh. Across the system, an estimated 12 GW of mining load was shed.

MARA framed it as civic virtue: "Bitcoin mining is interruptible, we can power down our facilities in minutes, freeing up substantial capacity on the grid." That's true. It's also true that getting paid nothing while the grid charges everyone else $1,200 per megawatt-hour is not exactly a business model you pitch to growth investors.

Which is why the Bitfarms-to-Keel rebrand matters beyond the name change. Gagnon isn't just chasing a trend — he's following a survival instinct shared by every public miner watching their margins compress in real time. Core Scientific got there first with its CoreWeave deal. IREN, CleanSpark, and TeraWulf are all at various stages of the same pivot.

The pitch is simple: these companies hold land, power interconnections, and transmission access in a market where hyperscalers are desperate for all three. The hard part is converting a mining site into something a Google or a Microsoft would actually lease. That takes capital, engineering, and time — three things miners are short on.

The Hyperscalers Are Writing Checks That Would Make Defense Contractors Blush

The sheer volume of capital committed to Texas data centers this week borders on parody. Except these aren't concept decks — they're signed contracts.

Google's $40 billion Texas commitment by 2027 got a tangible milestone on February 9, when TotalEnergies announced the 1 GW solar PPA. TotalEnergies SVP Marc-Antoine Pignon called it the largest renewable PPA volume the company has ever signed in the United States. Google is also in negotiations with Bolt Data — the data center company backed by former Alphabet CEO Eric Schmidt — for a 250 MW deal at a West Texas campus that could eventually scale to 5 GW. That's not a typo. Five gigawatts. For one campus.

Oracle's Stargate project near Abilene is targeting 1.2 GW with $38 billion in financing, though word on the street is JPMorgan is having trouble syndicating the debt. That's worth watching — a $38 billion deal that can't find enough lenders tells you something about risk appetite at the margins.

Constellation Energy and CyrusOne locked in 1,100+ MW across two Texas sites — Freestone County and Thad Hill. Constellation CEO Joe Dominguez offered the obligatory patriotic framing: "Constellation is helping lay the foundation that will keep America at the forefront of AI and digital technology." Fine. More relevantly, Constellation is positioning itself as the go-to power provider for data centers at a scale that makes its nuclear fleet look purpose-built for this moment.

And the pipeline keeps growing. Amp Z wants to build a $1B+ campus on 1,000 acres near Lufkin. Black Mountain's $10 billion Fort Worth megaproject is stuck in city council approvals. Rick Perry's Fermi Energy has an 11 GW fantasy planned for Amarillo, except Amazon just pulled a $150 million advance — not a great sign. And in a move that captures the surreal tenor of the moment, the U.S. Army is leasing Fort Hood and Fort Bliss to data center developers on 50-year terms. Proposals are due February 23.

Morgan Stanley put a number on the overall picture: the Big 4 hyperscalers are projected to spend roughly $700 billion in 2026 capex, and the bank expects "upward pressure on hyperscaler capex estimates" to continue.

Curt Holcomb at JLL laid it out: "Texas, and ERCOT in particular, is experiencing more demand and requests for power capacity than any other region in the country." No kidding.

ERCOT's Doom Loop: Too Much Demand, Not Enough Process

Here's where the optimism runs headlong into physics. ERCOT's demand forecast now projects 145 GW by 2031. The grid currently has about 85 GW of installed capacity. That's a 70% gap, and the timeline is five years.

Jeff Billo, ERCOT's VP of grid planning, told Houston Public Media this week that the interconnection queue has devolved into a recursive nightmare: "We are continually having to restudy those large loads." Every time a multi-hundred-megawatt data center enters the queue, it triggers restudies of the projects already in line.

ERCOT is now switching to a batch study process to try to break the cycle and may revisit 8.2 GW of previously approved load. Billo acknowledged what everyone in the Texas energy world already knows: "All that AI magic happens at a data center... a lot of those data centers are being built in Texas."

SB6 is trying to add financial collateral requirements — essentially making developers put real money behind their interconnection applications to weed out the speculators from the builders.

Nationally, 252 GW of gas-fired generation is in planning stages, a lot of it aimed at Texas. But "planned" and "operating" are very different words in power development.

The irony isn't lost on anyone: the Bitcoin miners who already have grid connections — the ones pivoting to AI — may end up holding the most valuable asset in the state. Not because of what they built, but because of the queue position they're sitting on. In a market where getting plugged in might take years, being plugged in already is worth more than the facility itself.

What to Watch Next Week

February 23 brings the deadline for Army data center proposals at Fort Hood and Fort Bliss — the bidder list will reveal how seriously the defense establishment is taking this play.

Keep an eye on JPMorgan's progress syndicating Oracle/Stargate's $38 billion. If that deal doesn't come together, it reshuffles the deck in West Texas.

ERCOT's batch study details will start defining winners and losers in the interconnection queue.

And if hashprice stays pinned below $35/TH/s, expect at least one more public miner to drop the word "Bitcoin" from its investor deck before the month is out.

Barrio Energy provides independent analysis of Texas power markets, data center development, and digital infrastructure. This is not investment advice.

Andi

Andi

Market Intelligence Analyst | Barrio Energy

Andi covers Texas power infrastructure, AI data center development, and digital energy markets. She tracks the intersection of compute demand and grid capacity across ERCOT and beyond.